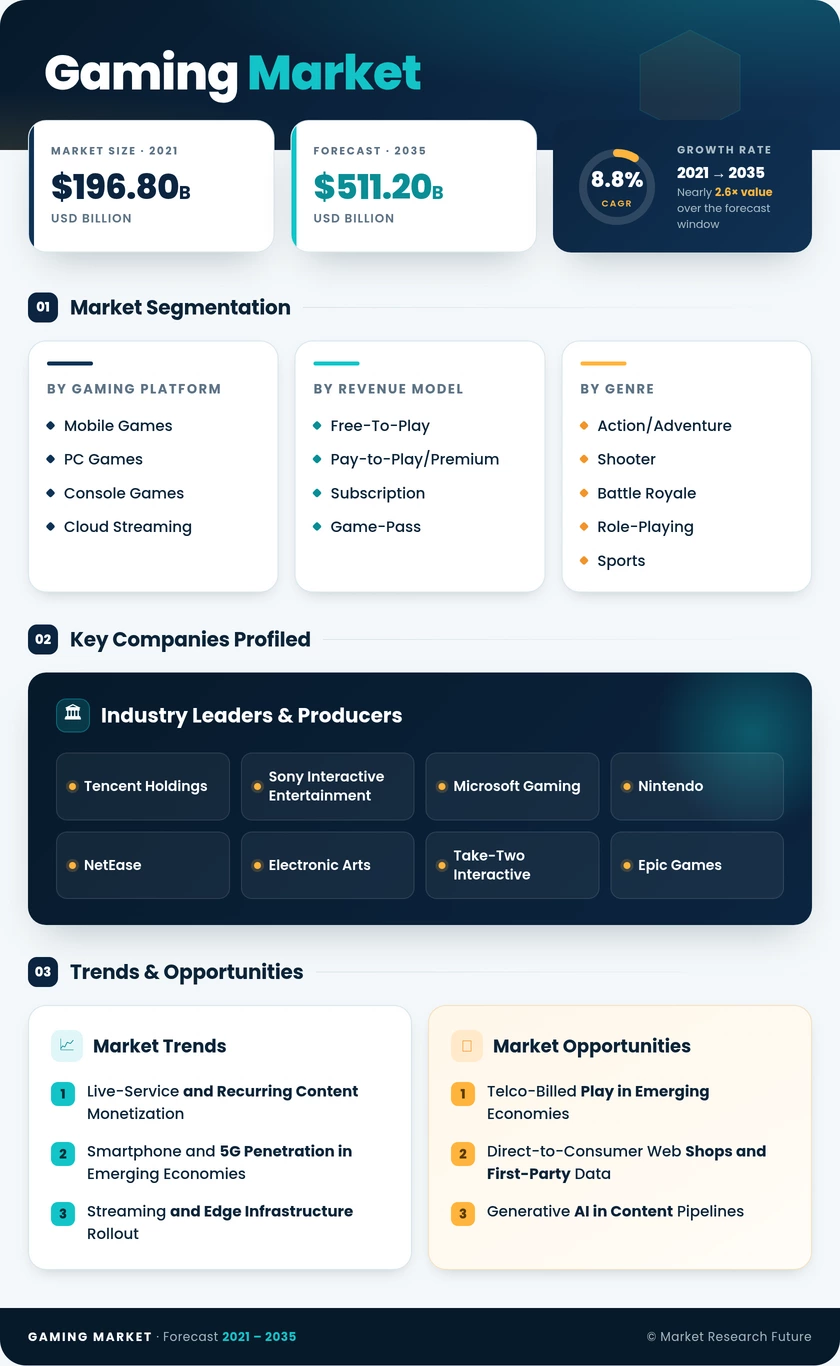
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Gaming Platform | Mobile Games, PC Games, Console Games, Cloud Streaming | Mobile Games (46.4% share) | Cloud Streaming (24.6% CAGR) |
| By Revenue Model | Free-To-Play, Pay-to-Play/Premium, Subscription and Game-Pass | Free-To-Play (79.6% share) | Subscription and Game-Pass (12.9% CAGR) |
| By Genre | Action/Adventure, Shooter and Battle Royale, Role-Playing, Sports and Racing, Strategy and Simulation, Puzzle and Casual, Others | Shooter and Battle Royale (20.4% share) | Shooter and Battle Royale (20.4% share; fastest-expanding genre) |
| By Player Age Group | Under 18 Years, 18-35 Years, 36-50 Years, Above 50 Years | 18-35 Years (47.5% share) | Under 18 Years (8.3% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific (46.1% share) | Middle East & Africa (9.8% CAGR) |
Market Segmentation Overview
By Gaming Platform
| Sub-Segment | Key Trend |
|---|---|
| Mobile Games | Hybrid monetization blending in-app purchases with rewarded ads |
| PC Games | Downloaded/boxed and browser titles serving modding and tournament communities |
| Console Games | Mid-cycle price increases and first-party exclusives |
| Cloud Streaming | Low-price passes and edge nodes removing hardware barriers |
Mobile Games lead the platform mix because a base of more than 3 billion smartphones gives free-to-play catalogs unmatched reach. Cloud Streaming grows fastest as edge infrastructure and telco-bundled passes let players skip a USD 500 console entirely. Console Games keep their premium audience through exclusives but face slower growth as 2025 price increases lengthen upgrade cycles.
By Revenue Model
| Sub-Segment | Key Trend |
|---|---|
| Free-To-Play | Battle passes, cosmetics and web-shop payments |
| Pay-to-Play/Premium | Seasonal passes added to USD 70 base games |
| Subscription and Game-Pass | Day-one releases and carrier-billed bundles |
Free-To-Play dominates because zero-cost entry converts reach into a paying minority that funds the whole economy. Subscription and Game-Pass grows fastest as platform holders put new releases into catalogs on launch day and telcos add libraries to data plans. Pay-to-Play/Premium survives by layering post-launch passes onto full-price releases rather than relying on a single sale.
By Genre
| Sub-Segment | Key Trend |
|---|---|
| Action/Adventure | Seasonal DLC between narrative sequels |
| Shooter and Battle Royale | Live-service seasons, anti-cheat and UGC editing tools |
| Role-Playing | Gacha monetization and open-world franchises |
| Sports and Racing | Annual licensed-league iterations |
| Strategy and Simulation | Long-session PC audiences |
| Puzzle and Casual | Ad-funded mobile play |
| Others | Fitness, music and learning titles |
Shooter and Battle Royale titles both lead the genre mix and expand fastest, because seasonal cosmetics and limited-time modes keep competitive players spending for years. Action/Adventure follows closely, now using DLC to stay relevant between sequels. Sports and Racing relies on licensed leagues for dependable annual revenue, while Puzzle and Casual monetizes mainly through advertising rather than purchases.
By Player Age Group
| Sub-Segment | Key Trend |
|---|---|
| Under 18 Years | Creation-led play on user-generated platforms |
| 18-35 Years | Battle passes, subscriptions and competitive titles |
| 36-50 Years | Remasters, legacy franchises and casual mobile play |
| Above 50 Years | Puzzle, card and brain-training games on tablets |
Players aged 18-35 Years account for the largest share of spending, backed by disposable income and appetite for competitive titles. Under 18 Years grows fastest as Roblox and similar sandboxes turn building into play, though child-privacy and loot-box rules will shape how platforms monetize this cohort. The 36-50 Years group spends steadily on remasters and franchises they played in their youth.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA