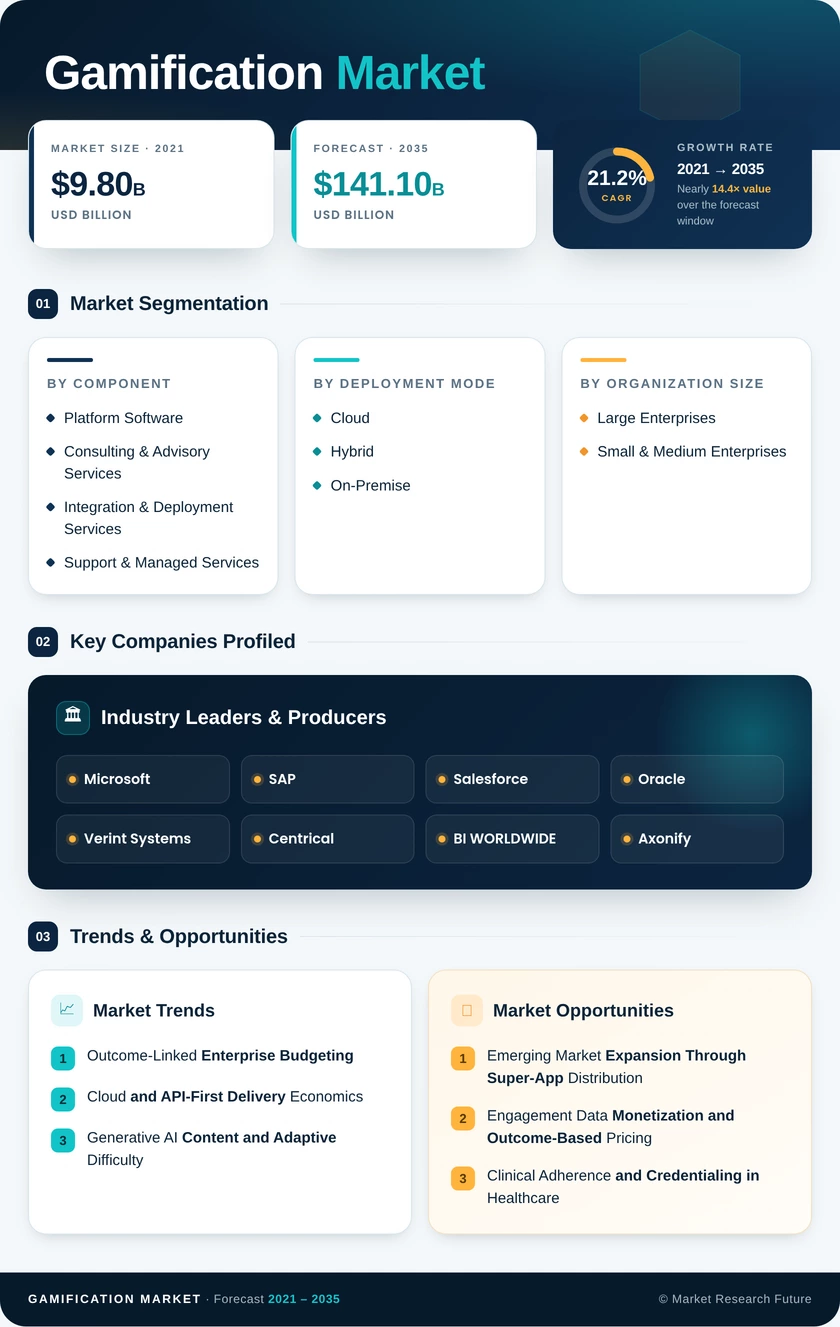
Gamification Market (2026 - 2035)

ID: MRFR/ICT/9793-HCR 200 Pages Aarti Dhapte Last Updated: September 15, 2026
Gamification Market Size, Share and Research Report By Component (Platform Software, Consulting & Advisory Services, Integration & Deployment Services, Support & Managed Services), By Deployment Mode (Cloud, Hybrid, On-Premise), By Organization Size (Large Enterprises, Small & Medium Enterprises), By Application (Marketing & Sales, Training & Development, Customer Onboarding & Loyalty, Workforce Productivity & Performance, Support & Helpdesk), By End-User Industry (Retail & E-commerce, BFSI, IT & Telecom, Healthcare & Life Sciences, Education, Media & Entertainment, Manufacturing, Government & Public Sector) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
Gamification Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)21.2%
2025 Market SizeUSD 20.6 Billion
2035 Market SizeUSD 141.1 Billion
Key Players
Microsoft
SAP
Salesforce
Oracle
Verint Systems
Centrical
Opportunities
  • Emerging Market Expansion Through Super-App Distribution
  • Engagement Data Monetization and Outcome-Based Pricing
  • Clinical Adherence and Credentialing in Healthcare
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Component | |
    2. 2.2 By Deployment Mode | |
    3. 2.3 By Organization Size | |
    4. 2.4 By Application | |
    5. 2.5 By End-User Industry | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Outcome-Linked Enterprise Budgeting | |
    2. 4.2 Cloud and API-First Delivery Economics | |
    3. 4.3 Generative AI Content and Adaptive Difficulty | |
    4. 4.4 Loyalty Economics in Retail and BFSI | |
    5. 4.5 Mandatory Compliance and Safety Training | |
    6. 4.6 Mobile-First Consumer Penetration | |
    7. 4.7 Health and Wellness Behavior Programs | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Engagement Decay and Novelty Effect | |
    2. 5.2 Privacy Regulation on Behavioral Data | |
    3. 5.3 Legacy System Integration Complexity | |
    4. 5.4 Weak Return-on-Investment Measurement | |
    5. 5.5 Workforce Resistance and Cultural Fit | |
  6. 6 Opportunities | |
    1. 6.1 Emerging Market Expansion Through Super-App Distribution | |
    2. 6.2 Engagement Data Monetization and Outcome-Based Pricing | |
    3. 6.3 Clinical Adherence and Credentialing in Healthcare | |
    4. 6.4 Embedded and White-Label Platform Economics | |
    5. 6.5 Public Sector Civic Participation Programs | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Australia | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 United Arab Emirates | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Generative Content and Autonomous Program Operation | |
    2. 8.2 Platform Consolidation and Suite Economics | |
    3. 8.3 Spatial and Immersive Interfaces | |
    4. 8.4 Human Capital Disclosure and Measurement Standards | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Platform Software | | |
      2. 9.1.2 Consulting & Advisory Services | | |
      3. 9.1.3 Integration & Deployment Services | | |
      4. 9.1.4 Support & Managed Services | |
    2. 9.2 By Deployment Mode | | |
      1. 9.2.1 Cloud | | |
      2. 9.2.2 Hybrid | | |
      3. 9.2.3 On-Premise | |
    3. 9.3 By Organization Size | | |
      1. 9.3.1 Large Enterprises | | |
      2. 9.3.2 Small & Medium Enterprises | |
    4. 9.4 By Application | | |
      1. 9.4.1 Marketing & Sales | | |
      2. 9.4.2 Training & Development | | |
      3. 9.4.3 Customer Onboarding & Loyalty | | |
      4. 9.4.4 Workforce Productivity & Performance | | |
      5. 9.4.5 Support & Helpdesk | |
    5. 9.5 By End-User Industry | | |
      1. 9.5.1 Retail & E-commerce | | |
      2. 9.5.2 BFSI | | |
      3. 9.5.3 IT & Telecom | | |
      4. 9.5.4 Healthcare & Life Sciences | | |
      5. 9.5.5 Education | | |
      6. 9.5.6 Media & Entertainment | | |
      7. 9.5.7 Manufacturing | | |
      8. 9.5.8 Government & Public Sector | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Gamification Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Gamification Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Global Gamification Market – Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Global Gamification Market – Restraint Impact Analysis, 2026–2035 | |
  19. TABLE 5 Global Gamification Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Gamification Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Gamification Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Gamification Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Gamification Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Gamification Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Gamification Market Size, by Component, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Gamification Market Size, by Deployment Mode, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Gamification Market Size, by Organization Size, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Gamification Market Size, by Application, 2021–2035 (USD Billion) | |
  29. TABLE 15 Global Gamification Market Size, by End-User Industry, 2021–2035 (USD Billion) | |
  30. TABLE 16 Competitive Benchmarking Matrix – Global Gamification Market, 2026 | |
  31. TABLE 17 Company Profiles – Key Players, Global Gamification Market | |
  32. TABLE 18 Recent Developments & Strategic Announcements, 2023–2025 | |
  33. TABLE 19 Report Scope & Methodology Summary | |
  34. TABLE 20 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  35. FIGURE 1 Global Gamification Market – Market Dynamics Overview | |
  36. FIGURE 2 Global Gamification Market – Industry Value Chain Analysis | |
  37. FIGURE 3 Global Gamification Market – Porter's Five Forces Analysis | |
  38. FIGURE 4 Global Gamification Market Size Trend, 2021–2035 (USD Billion) | |
  39. FIGURE 5 Global Gamification Market – Year-over-Year Growth Trend, 2022–2035 | |
  40. FIGURE 6 Market Share by Component, 2025 vs 2035 | |
  41. FIGURE 7 Market Share by Deployment Mode, 2025 vs 2035 | |
  42. FIGURE 8 Market Share by Organization Size, 2025 vs 2035 | |
  43. FIGURE 9 Market Share by Application, 2025 vs 2035 | |
  44. FIGURE 10 Market Share by End-User Industry, 2025 vs 2035 | |
  45. FIGURE 11 Regional Market Share Distribution, 2025 | |
  46. FIGURE 12 Regional Market Share Distribution, 2035 | |
  47. FIGURE 13 Competitive Landscape – Estimated Revenue Share Positioning, 2026 | |
  48. FIGURE 14 Competitive Positioning Matrix – Capability vs Distribution Reach

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentPlatform Software; Consulting & Advisory Services; Integration & Deployment Services; Support & Managed ServicesPlatform Software (68.4% share, 2025)Support & Managed Services (23.6% CAGR)
By Deployment ModeCloud; Hybrid; On-PremiseCloud (74.6% share, 2025)Hybrid (25.9% CAGR)
By Organization SizeLarge Enterprises; Small & Medium EnterprisesLarge Enterprises (63.2% share, 2025)Small & Medium Enterprises (24.8% CAGR)
By ApplicationMarketing & Sales; Training & Development; Customer Onboarding & Loyalty; Workforce Productivity & Performance; Support & HelpdeskMarketing & Sales (28.4% share, 2025)Workforce Productivity & Performance (24.9% CAGR)
By End-User IndustryRetail & E-commerce; BFSI; IT & Telecom; Healthcare & Life Sciences; Education; Media & Entertainment; Manufacturing; Government & Public SectorRetail & E-commerce (22.6% share, 2025)Healthcare & Life Sciences (25.7% CAGR)


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
Platform SoftwareConfiguration replacing custom development; connector breadth as primary selection criterion
Consulting & Advisory ServicesScarcity of program design expertise sustaining premium day rates
Integration & Deployment ServicesIdentity reconciliation dominating implementation scope and timeline
Support & Managed ServicesOngoing content refresh contracted out as internal design capacity stays thin


Platform software leads this dimension at 68.4% of 2025 revenue because buyers now expect an engine they can configure rather than a project they must build. Support and managed services grow fastest at 23.6% for a related reason: the same buyers who avoid building engines also lack the internal designers needed to refresh challenge content past the first year, so they contract the work out. Integration and deployment services remain sizeable at USD 3.1 billion, held up by identity reconciliation across overlapping enterprise directories rather than by any complexity in the platforms themselves.

By Deployment Mode

Sub-SegmentKey Trend
CloudDefault architecture for new deployments; fastest connector availability
HybridLocal behavioral data storage paired with cloud-hosted progression logic
On-PremiseRetained in defense, government, and network-isolated manufacturing estates


Cloud dominates at 74.6% and will keep the lead throughout the forecast, since connector ecosystems and elastic scaling both favor hosted delivery. Hybrid grows fastest at 25.9% because data residency requirements in Europe, India, and the Gulf force behavioral records to stay within national borders while permitting progression logic to run centrally. On-premise, at USD 3.6 billion, survives only where network isolation is mandated, and vendors without a documented hybrid reference architecture are now routinely excluded from regulated public-sector tenders.

By Organization Size

Sub-SegmentKey Trend
Large EnterprisesMulti-department programs with formal measurement and audit requirements
Small & Medium EnterprisesSelf-serve tiers and templated program libraries removing implementation cost


Large enterprises supply 63.2% of revenue because contract values scale with headcount and because these buyers maintain analytics teams capable of demonstrating effect at renewal. Small and medium enterprises grow faster at 24.8% as entry pricing falls below USD 5 per user monthly and templated libraries eliminate the design cost that previously made adoption uneconomic under roughly 500 employees. Reaching that cohort profitably depends on channel partners and embedded distribution rather than direct enterprise sales motions.

By Application

Sub-SegmentKey Trend
Marketing & SalesTier progression displacing flat discounting to protect margin
Training & DevelopmentRegulatory completion mandates sustaining non-discretionary volume
Customer Onboarding & LoyaltyActivation sequences in banking and telecom targeting product adoption
Workforce Productivity & PerformanceMechanics attached to instrumented operational metrics
Support & HelpdeskAgent proficiency progression and knowledge base contribution incentives


Marketing and sales leads at 28.4% share because it sits nearest to revenue and therefore survives budget scrutiny that internal tooling does not. Workforce productivity and performance grows fastest at 24.9%, concentrated in contact centers and field service organizations where handle time, resolution rate, and safety incidents are already measured, so behavioral lift converts directly into a cost figure a sponsor can defend. Training and development stays large at USD 5.4 billion on the strength of compliance completion obligations rather than voluntary investment.

By End-User Industry

Sub-SegmentKey Trend
Retail & E-commerceLoyalty tier restructuring aimed at basket composition, not just frequency
BFSIProduct activation programs alongside mandatory conduct training
IT & TelecomSubscriber retention mechanics and technical certification pathways
Healthcare & Life SciencesAdherence interventions and clinical credentialing progression
EducationLearner retention in test preparation and higher education platforms
Media & EntertainmentSubscription retention and community contribution incentives
ManufacturingSafety procedure compliance and skills matrix progression
Government & Public SectorCitizen participation programs and workforce nationalization training


Retail and e-commerce hold the largest share at 22.6% because loyalty programs are funded from commercial budgets tied to measurable basket outcomes rather than from discretionary technology allocations. Healthcare and life sciences expand fastest at 25.7% as payers fund adherence interventions with documented claims impact and providers digitize credentialing under continuing-education requirements. BFSI contributes USD 3.4 billion across two distinct demand streams — customer activation and mandatory conduct training — which gives vendors serving banks unusually stable renewal profiles compared with single-use-case verticals.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.