Europe Pipe Market (2026 - 2035)

ID: MRFR/PCM/4761-CR 111 Pages Varsha More Last Updated: September 15, 2026
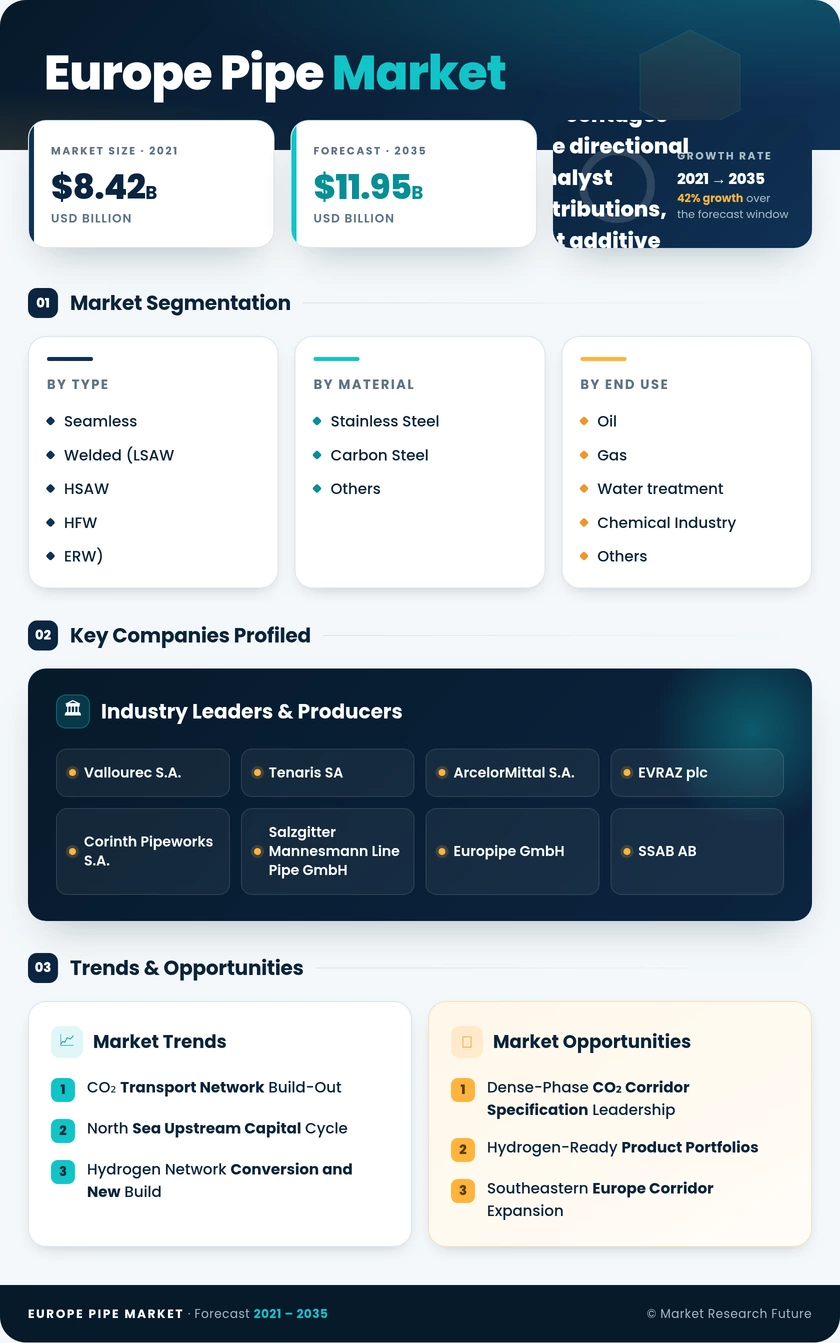
Europe Pipe Market Research Report Information By Type (Seamless, Welded, LSAW, HSAW, HFW, and ERW), By Material (Stainless Steel, Carbon Steel, and Others), and By End Use (Oil and Gas, Water treatment, Chemical Industry, and Others) – Forecast Till 2035
Europe Pipe Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)2.4%
2025 Market SizeUSD 9.42 Billion
2035 Market SizeUSD 11.95 Billion
Key Players
Vallourec S.A.
Tenaris SA
ArcelorMittal S.A.
EVRAZ plc
Corinth Pipeworks S.A.
Salzgitter Mannesmann Line Pipe GmbH
Opportunities
  • Dense-Phase CO₂ Corridor Specification Leadership
  • Hydrogen-Ready Product Portfolios
  • Southeastern Europe Corridor Expansion
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Type | |
    2. 2.2 By Material | |
    3. 2.3 By End Use | |
    4. 2.4 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 CO₂ Transport Network Build-Out | |
    2. 4.2 North Sea Upstream Capital Cycle | |
    3. 4.3 Hydrogen Network Conversion and New Build | |
    4. 4.4 Aging Asset Replacement and Integrity Spend | |
    5. 4.5 Water Network Renewal Mandates | |
    6. 4.6 Carbon Border Adjustment Mechanism | |
    7. 4.7 Offshore Wind Subsea Development | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Volatile Steel and Alloy Input Costs | |
    2. 5.2 Permitting and Environmental Review Delay | |
    3. 5.3 Structural Decline in Gas Throughput | |
    4. 5.4 Import Competition and Safeguard Uncertainty | |
    5. 5.5 Skilled Welding and Laying Capacity Shortage | |
  6. 6 Opportunities | |
    1. 6.1 Dense-Phase CO₂ Corridor Specification Leadership | |
    2. 6.2 Hydrogen-Ready Product Portfolios | |
    3. 6.3 Southeastern Europe Corridor Expansion | |
    4. 6.4 Traceability Data and Integrity Analytics Services | |
    5. 6.5 Low-Carbon Steel Premium Positioning | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Norway | |
    2. 7.2 Germany | |
    3. 7.3 United Kingdom | |
    4. 7.4 Rest of Europe | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Molecule Transition and Asset Repurposing | |
    2. 8.2 Integrity Analytics and Predictive Maintenance | |
    3. 8.3 Embodied Carbon as a Commercial Variable | |
    4. 8.4 Supply Chain Regionalisation | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Type | | |
      1. 9.1.1 Seamless | | |
      2. 9.1.2 Welded | |
    2. 9.2 By Material | | |
      1. 9.2.1 Stainless Steel | | |
      2. 9.2.2 Carbon Steel | | |
      3. 9.2.3 Others | |
    3. 9.3 By End Use | | |
      1. 9.3.1 Oil and Gas | | |
      2. 9.3.2 Water treatment | | |
      3. 9.3.3 Chemical Industry | | |
      4. 9.3.4 Others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | |
  11. 11 Recent News and Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Europe Pipe Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Europe Pipe Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Europe Pipe Market Size, by Country, 2021–2035 (USD Billion) | |
  20. TABLE 6 Norway Pipe Market Size, by Demand Node, 2021–2035 (USD Billion) | |
  21. TABLE 7 Germany Pipe Market Size, by Demand Node, 2021–2035 (USD Billion) | |
  22. TABLE 8 United Kingdom Pipe Market Size, by Demand Node, 2021–2035 (USD Billion) | |
  23. TABLE 9 Rest of Europe Pipe Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Europe Pipe Market Size, by Type, 2021–2035 (USD Billion) | |
  25. TABLE 11 Europe Pipe Market Size, by Welded Sub-Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Europe Pipe Market Size, by Material, 2021–2035 (USD Billion) | |
  27. TABLE 13 Europe Pipe Market Size, by End Use, 2021–2035 (USD Billion) | |
  28. TABLE 14 Norway Pipe Market Size, by Type, 2021–2035 (USD Billion) | |
  29. TABLE 15 Germany Pipe Market Size, by Material, 2021–2035 (USD Billion) | |
  30. TABLE 16 United Kingdom Pipe Market Size, by End Use, 2021–2035 (USD Billion) | |
  31. TABLE 17 Rest of Europe Pipe Market Size, by Type, 2021–2035 (USD Billion) | |
  32. TABLE 18 Competitive Benchmarking Matrix, 2026 | |
  33. TABLE 19 Company Profiles – Key Players | |
  34. TABLE 20 Recent Developments & Strategic Announcements, 2023–2025 | |
  35. TABLE 21 Report Scope & Methodology Summary | |
  36. TABLE 22 Detailed Sources and Citations | | LIST OF FIGURES | |
  37. FIGURE 1 Market Dynamics – Drivers, Restraints and Opportunities | |
  38. FIGURE 2 Industry Value Chain Analysis | |
  39. FIGURE 3 Porter's Five Forces Analysis | |
  40. FIGURE 4 Market Size Trend and Forecast, 2021–2035 (USD Billion) | |
  41. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 | |
  42. FIGURE 6 Share by Type, 2025 vs 2035 | |
  43. FIGURE 7 Welded Sub-Type Share Distribution, 2025 | |
  44. FIGURE 8 Share by Material, 2025 vs 2035 | |
  45. FIGURE 9 Share by End Use, 2025 vs 2035 | |
  46. FIGURE 10 Country Share Distribution, 2025 | |
  47. FIGURE 11 Country CAGR Comparison, 2026–2035 | |
  48. FIGURE 12 Competitive Landscape Positioning Map, 2026 | |
  49. FIGURE 13 Top-Five Supplier Share Concentration, 2026

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypeSeamless; Welded (LSAW, HSAW, HFW, ERW)Welded (62.8% share)Seamless (2.7% CAGR)
By MaterialStainless Steel; Carbon Steel; OthersStainless Steel (46.5% share)Carbon Steel (2.7% CAGR)
By End UseOil and Gas; Water treatment; Chemical Industry; OthersOil and Gas (USD 5.14 Billion)Water treatment (3.1% CAGR)


Market Segmentation Overview

By Type

Sub-SegmentKey Trend
SeamlessSour-service and high-collapse grades gaining share on North Sea tie-back programmes
WeldedLarge-diameter demand concentrated in CO₂, hydrogen and water corridor construction
LSAWDense-phase CO₂ specifications driving tight ovality and fracture-arrest requirements
HSAWCost-efficient choice for lower-pressure water transmission duty
HFWDisplacing ERW on mid-diameter work where seam integrity requirements have tightened
ERWStable standard-grade distribution and utility volume, price-competitive


Welded product leads this dimension at 62.8% share because Europe's active project set is dominated by large-diameter onshore corridors where LSAW and HSAW economics beat seamless decisively. Within that family, LSAW captures the highest-value scope as CO₂ transport specifications impose geometric and fracture-arrest requirements that lower-tier processes cannot meet, while HFW steadily displaces ERW on mid-diameter replacement as operators tighten seam-integrity acceptance criteria. Seamless nonetheless grows fastest at 2.7%, since Norwegian and UK offshore duty requires wall thickness and sour-service qualification that rule welded construction out entirely.

By Material

Sub-SegmentKey Trend
Stainless SteelPreferred for chloride and H₂S exposure across North Sea and process applications
Carbon SteelVolume beneficiary of CO₂ corridor construction under controlled-moisture conditions
OthersClad and lined constructions serving aggressive-service niches at lower cost than solid alloy


Stainless Steel holds the leading 46.5% position because offshore lifecycle economics in Norwegian and UK waters favour corrosion resistance over lower initial cost — replacement in subsea service is prohibitively expensive. Carbon Steel grows fastest at 2.7% for a specific technical reason: dense-phase CO₂ with tightly controlled moisture does not require alloy protection, and the corridor volumes involved are large. The Others category, spanning clad and lined product, occupies the middle ground where neither option performs adequately, typically at 30–40% below solid alloy cost.

By End Use

Sub-SegmentKey Trend
Oil and GasComposition shifting from expansion toward replacement and integrity-driven renewal.
Water treatmentLeakage action plan obligations forcing municipal trunk main replacement
Chemical IndustryTwenty-year corrosion replacement cycle at Antwerp, Rotterdam and Ludwigshafen complexes
OthersPower, district heating and industrial utility duty with modest specification demands


Oil and Gas dominates at USD 5.14 billion, but the character of that demand is changing as declining throughput redirects spending from new capacity toward integrity-driven section replacement on assets commissioned before 1990. Water treatment grows fastest at 3.1%, a direct consequence of member state obligations to submit leakage action plans where losses exceed the 25% threshold — a mandate that binds Italian and German utilities particularly hard. Chemical Industry demand at 16.8% share follows a predictable process-plant renewal rhythm rather than policy triggers.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.