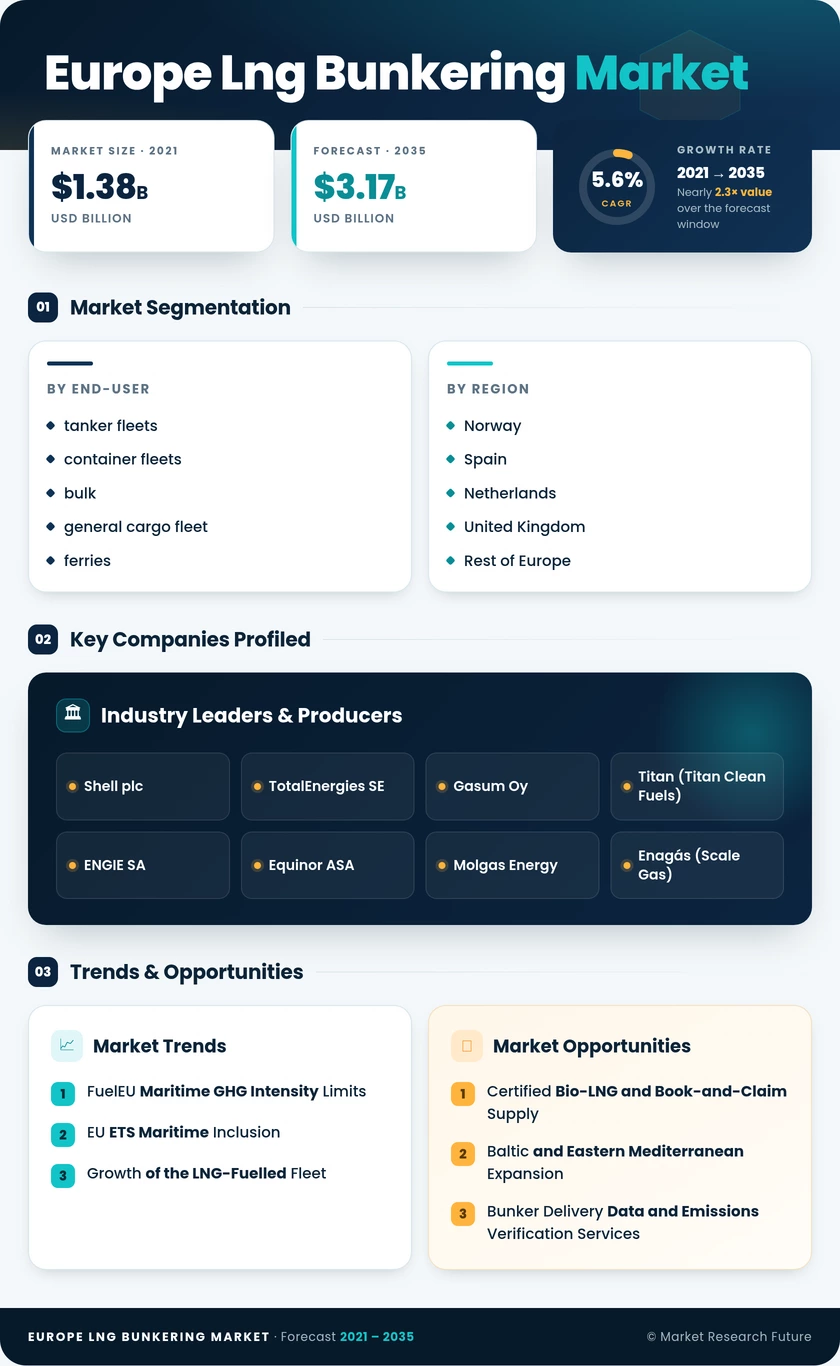
Europe LNG Bunkering Market (2026 - 2035)

ID: MRFR/EnP/11165-HCR 128 Pages Swapnil Palwe Last Updated: October 31, 2026
Europe LNG Bunkering Market Research Report By End-User (Tanker Fleets, Container Fleets, Bulk and General Cargo Fleet, Ferries and OSV, Others) - Forecast to 2035
Europe LNG Bunkering Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.6%
2025 Market SizeUSD 1.84 Billion
2035 Market SizeUSD 3.17 Billion
Key Players
Shell plc
TotalEnergies SE
Gasum Oy
Titan
ENGIE SA
Equinor ASA
Opportunities
  • Certified Bio-LNG and Book-and-Claim Supply
  • Baltic and Eastern Mediterranean Expansion
  • Bunker Delivery Data and Emissions Verification Services
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By End-user | |
    2. 2.2 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 FuelEU Maritime GHG Intensity Limits | |
    2. 4.2 EU ETS Maritime Inclusion | |
    3. 4.3 Growth of the LNG-Fuelled Fleet | |
    4. 4.4 AFIR Core-Port Refuelling Mandate | |
    5. 4.5 Norwegian NOx Fund and Enova Support | |
    6. 4.6 Bio-LNG and Synthetic Methane Pathway | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Methane Slip Concerns | |
    2. 5.2 Infrastructure Gaps Outside Core Hubs | |
    3. 5.3 Gas Price Volatility | |
    4. 5.4 Competing Alternative Fuels | |
    5. 5.5 Capital Cost of Vessels and Bunker Assets | |
  6. 6 Opportunities | |
    1. 6.1 Certified Bio-LNG and Book-and-Claim Supply | |
    2. 6.2 Baltic and Eastern Mediterranean Expansion | |
    3. 6.3 Bunker Delivery Data and Emissions Verification Services | |
    4. 6.4 Cruise and Ro-Pax Newbuild Programmes | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Norway | |
    2. 7.2 Spain | |
    3. 7.3 Netherlands | |
    4. 7.4 United Kingdom | |
    5. 7.5 Rest of Europe | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 From Fossil LNG to Bio-LNG and e-Methane | |
    2. 8.2 Carbon Pricing as the Fuel-Choice Lever | |
    3. 8.3 Digital Bunkering and Port Operations | |
    4. 8.4 Emissions Reporting and Methane Accountability | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By End-user | | |
      1. 9.1.1 tanker fleets | | |
      2. 9.1.2 Container fleets | | |
      3. 9.1.3 Bulk and general cargo fleet | | |
      4. 9.1.4 Ferries and OSV | | |
      5. 9.1.5 others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Overview | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Shell plc | | |
      2. 10.3.2 TotalEnergies SE | | |
      3. 10.3.3 Gasum Oy | | |
      4. 10.3.4 Titan (Titan Clean Fuels) | | |
      5. 10.3.5 ENGIE SA | | |
      6. 10.3.6 Equinor ASA | | |
      7. 10.3.7 Molgas Energy | | |
      8. 10.3.8 Enagás (Scale Gas) | | |
      9. 10.3.9 Barents NaturGass | | |
      10. 10.3.10 KN Energies (Klaipėdos Nafta) | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Report Snapshot — Market Size, CAGR and Leading Regions | |
  16. TABLE 2 European LNG Bunkering Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Year-over-Year Growth Analysis, 2021–2035 | |
  18. TABLE 4 Driver Impact Analysis | |
  19. TABLE 5 Restraints Impact Analysis | |
  20. TABLE 6 Regional Summary, by Country, 2025 | |
  21. TABLE 7 Norway — Market by Hub / Area | |
  22. TABLE 8 Spain — Market by Port | |
  23. TABLE 9 Netherlands — Market by Port | |
  24. TABLE 10 United Kingdom — Market by Port / Area | |
  25. TABLE 11 Rest of Europe — Market by Country / Group | |
  26. TABLE 12 Market Size, by End-user, 2021–2035 (USD Billion) | |
  27. TABLE 13 Norway Market Size, by End-user, 2021–2035 (USD Billion) | |
  28. TABLE 14 Spain Market Size, by End-user, 2021–2035 (USD Billion) | |
  29. TABLE 15 Netherlands Market Size, by End-user, 2021–2035 (USD Billion) | |
  30. TABLE 16 United Kingdom Market Size, by End-user, 2021–2035 (USD Billion) | |
  31. TABLE 17 Rest of Europe Market Size, by End-user, 2021–2035 (USD Billion) | |
  32. TABLE 18 Competitive Benchmarking Matrix, 2025 | |
  33. TABLE 19 Recent News & Developments, 2023–2025 | |
  34. TABLE 20 Report Scope and Methodology | |
  35. TABLE 21 Detailed Sources and Citations | |
  36. TABLE 22 Segmentation Quick Reference | |
  37. TABLE 23 End-user Sub-Segment Key Trends | | LIST OF FIGURES | |
  38. FIGURE 1 Market Dynamics Overview — Drivers, Restraints and Opportunities | |
  39. FIGURE 2 Industry Value Chain — Import Terminal to Ship Delivery | |
  40. FIGURE 3 Porter's Five Forces Analysis | |
  41. FIGURE 4 Market Size Trend, 2021–2035 (USD Billion) | |
  42. FIGURE 5 Year-over-Year Growth Rate, 2021–2035 | |
  43. FIGURE 6 Market Share, by End-user, 2025 | |
  44. FIGURE 7 CAGR Comparison, by End-user, 2026–2035 | |
  45. FIGURE 8 Regional Market Share, by Country, 2025 | |
  46. FIGURE 9 Regional CAGR Comparison, 2026–2035 | |
  47. FIGURE 10 Competitive Landscape — Estimated Revenue Share Ranges, 2025 | |
  48. FIGURE 11 Competitive Positioning Matrix

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By End-usertanker fleets, container fleets, bulk and general cargo fleet, ferries and OSV, othersferries and OSV (36.5% share)container fleets (7.1% CAGR)
By RegionNorway, Spain, Netherlands, United Kingdom, Rest of EuropeNorway (31.5% share)Spain (7.4% CAGR)


Market Segmentation Overview

By End-user

Sub-SegmentKey Trend
tanker fleetsLNG-fuelled crude and product tankers expanding on Rotterdam and Mediterranean trades
container fleetsDual-fuel ultra-large boxships driving high-volume ship-to-ship demand.
bulk and general cargo fleetGradual conversions constrained by irregular trading patterns.
Ferries and OSVsMature Norwegian and Channel fleets shifting toward bio-LNG blends
othersCruise ships and car carriers adding scheduled demand at passenger and vehicle hubs.


Ferries and OSV lead this dimension because fixed routes and Norwegian public procurement made LNG adoption low-risk two decades before other segments moved. Container fleets grow fastest, since each dual-fuel boxship lifts thousands of cubic metres per call and FuelEU penalties scale with vessel energy use. Tanker fleets hold the next-largest revenue base, while the bulk and general cargo fleet lags because unpredictable port rotations make guaranteed LNG supply harder to secure.


 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.