Segmentation Quick Reference
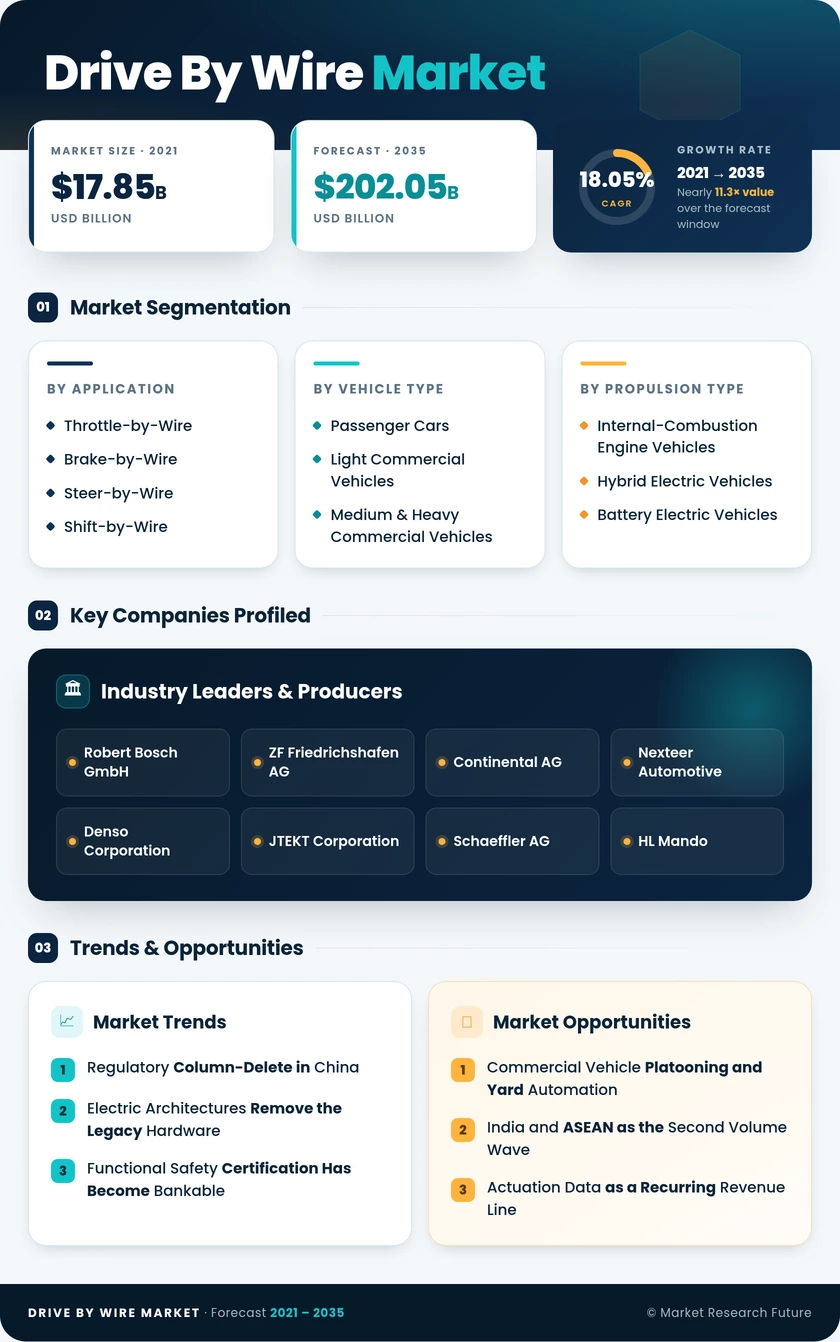
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Application | Throttle-by-Wire, Brake-by-Wire, Steer-by-Wire, Shift-by-Wire | Throttle-by-Wire | Steer-by-Wire |
| By Vehicle Type | Passenger Cars, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles | Passenger Cars | Medium & Heavy Commercial Vehicles |
| By Propulsion Type | Internal-Combustion Engine Vehicles, Hybrid Electric Vehicles, Battery Electric Vehicles | Internal-Combustion Engine Vehicles | Battery Electric Vehicles |
| By Component | Actuators, Sensors, Electronic Control Units, Software & Wiring | Actuators | Electronic Control Units |
| By Actuation Technology | Electromechanical, Electro-Hydraulic | Electromechanical | Electromechanical |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | Asia-Pacific | Europe |
Market Segmentation Overview
By Application
| Sub-Segment | Key Trend |
| Throttle-by-Wire | Saturated fitment; value shifting to integrated powertrain domain controllers |
| Brake-by-Wire | One-box units consolidating boosting, stability control, and regenerative blending |
| Steer-by-Wire | Column-delete regulation converting a niche technology into a platform standard |
| Shift-by-Wire | Rotary and toggle selectors freeing console space for storage and displays. |
Application mix is the clearest lens on where value is migrating. Throttle actuation supplies today's revenue base while steering supplies tomorrow's growth, and braking sits in the middle with the strongest regulatory tailwind attached to particulate limits.
By Vehicle Type
| Sub-Segment | Key Trend |
| Passenger Cars | Content per vehicle rising fastest in C-segment and above BEV programs |
| Light Commercial Vehicles | Last-mile delivery electrification pulling brake and throttle content forward. |
| Medium & Heavy Commercial Vehicles | Platooning and automated yard operations requiring redundant steering |
Passenger cars will remain the volume anchor throughout the forecast, but commercial vehicles deliver the superior growth rate because fleet payback maths tolerates higher upfront content.
By Propulsion Type
| Sub-Segment | Key Trend |
| Internal-Combustion Engine Vehicles | Declining share as new platform investment shifts to electrified architectures |
| Hybrid Electric Vehicles | Complex regenerative blending raising brake control content per vehicle |
| Battery Electric Vehicles | Native by-wire design with roughly 2.4x the content of comparable combustion vehicles |
Propulsion mix functions as the ceiling on total addressable content. Every percentage point of battery electric penetration lifts average per-vehicle by-wire value across the entire production base.
By Component
| Sub-Segment | Key Trend |
| Actuators | Largest revenue pool facing intensifying price competition from Asian suppliers |
| Sensors | Redundancy requirements effectively doubling position and torque sensor counts. |
| Electronic Control Units | Domain consolidation and fault arbitration driving the fastest component growth |
| Software & Wiring | Zonal migration shifting value from copper harness to control software. |
Component economics are diverging. Hardware commoditises while the control stack and safety case retain pricing power, which explains why suppliers are repositioning around software rather than actuator tonnage.
By Actuation Technology
| Sub-Segment | Key Trend |
| Electromechanical | Dry-system simplicity and packaging advantage driving majority adoption |
| Electro-Hydraulic | Retained on heavy-duty and carryover platforms where force density governs |
Electromechanical actuation is the default for new platform designs. Electro-hydraulic persists where mass and force requirements make fluid pressure the more efficient answer, with the medium-duty crossover expected around 2031.
By Geography
| Sub-Segment | Key Trend |
| North America | Redundancy validation for Level 3 pilots pending FMVSS modernisation |
| Europe | Euro 7 and UNECE amendments driving the fastest regional expansion |
| Asia-Pacific | Chinese column-delete regulation and domestic Tier-1 scale-up |
| South America | Flex-fuel throttle content with brake systems localising from 2028 |
| Middle East & Africa | Autonomous fleet pilots and premium import mix |
Regional divergence is regulatory, not technological. The suppliers are largely the same everywhere; what differs is how quickly each jurisdiction permits the mechanical linkage to disappear.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA