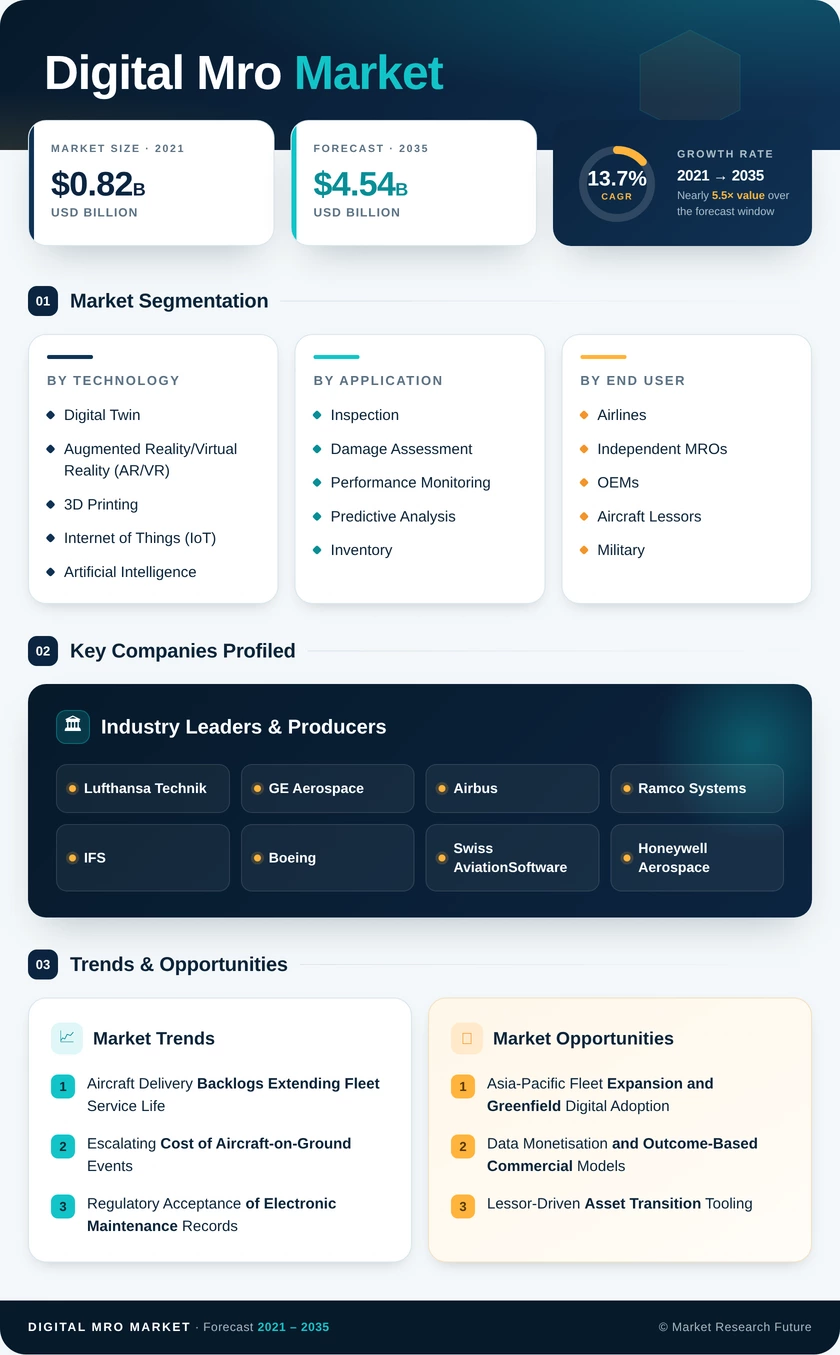
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Technology | Digital Twin; Augmented Reality/Virtual Reality (AR/VR); 3D Printing; Internet of Things (IoT); Artificial Intelligence and Big Data Analytics; Blockchain | Digital Twin (24.4% share, 2025) | Artificial Intelligence and Big Data Analytics (17.5% CAGR, 2026–2035) |
| By Application | Inspection and Damage Assessment; Performance Monitoring; Predictive Analysis; Inventory and Parts Replacement; Mobility and Functionality; Training and Remote Assistance; Documentation and Compliance | Inspection and Damage Assessment (27.3% share, 2025) | Predictive Analysis (17.1% CAGR, 2026–2035) |
| By End User | Airlines; Independent MROs; OEMs; Aircraft Lessors; Military and Defence Operators | Airlines (74.9% share, 2025) | Aircraft Lessors (17.3% CAGR, 2026–2035) |
Market Segmentation Overview
By Technology
| Sub-Segment | Key Trend |
| Digital Twin | Persistent virtual counterparts for engines, airframes, and rotables replacing fleet-average life assumptions |
| Augmented Reality/Virtual Reality (AR/VR) | Head-mounted and tablet-guided repair procedures reducing task-card interpretation error |
| 3D Printing | Certified on-demand production of obsolete cabin and non-critical structural parts |
| Internet of Things (IoT) | Expanded sensor coverage on current-generation powerplants and systems |
| Artificial Intelligence and Big Data Analytics | Automated pattern detection across full-flight parameter streams |
| Blockchain | Immutable provenance records for life-limited and critical rotable parts |
Digital twin leads this dimension because it holds the asset record that AR/VR workflows, analytics models, and inventory forecasts all query — without it, every other layer defaults to fleet averages that regulators increasingly reject for life-extension cases. Artificial intelligence and big data analytics grow fastest as parameter volumes from instrumented engines outrun what reliability engineers can review manually. Internet of Things adoption underpins both, since sensor coverage determines model fidelity. Blockchain and 3D printing stay niche, gated by certification precedent rather than buyer appetite.
By Application
| Sub-Segment | Key Trend |
| Inspection and Damage Assessment | Machine-vision classification of lightning, hail, and corrosion findings |
| Performance Monitoring | Continuous engine and systems trending against fleet benchmarks |
| Predictive Analysis | Remaining-useful-life estimation converting removals into planned shop visits |
| Inventory and Parts Replacement | Forward positioning of high-value rotables ahead of forecast demand |
| Mobility and Functionality | Tablet access to work orders, manuals, and live sensor data at the ramp |
| Training and Remote Assistance | Senior technicians supervising junior staff across multiple line stations |
| Documentation and Compliance | Paperless airworthiness records reducing continuing-airworthiness audit effort |
Inspection and damage assessment leads because condition capture is the precondition for every downstream workflow — predictive analysis models trained on gapped inspection data produce estimates regulators will not accept for programme revision. Predictive analysis grows fastest, since aircraft-on-ground economics running into six figures per hour make even incremental forecasting accuracy commercially decisive for airline buyers. Documentation and compliance hold steady demand tied directly to Part-145 and FAA electronic-records acceptance, while mobility and functionality expand wherever line stations operate away from hangar infrastructure.
By End User
| Sub-Segment | Key Trend |
| Airlines | Fleet-scale scheduling optimisation funded from operational savings |
| Independent MROs | Defensive analytics licensing against bundled OEM service contracts |
| OEMs | Shop throughput improvement and on-wing interval extension |
| Aircraft Lessors | Condition-backed remarketing and redelivery record reconciliation |
| Military and Defence Operators | Sovereign-hosted sustainment platforms under classification constraints |
Airlines dominate this dimension because fleet scale turns a one-percent scheduling improvement into a material annual operating-cost line, and carriers can fund platforms from avoided groundings rather than IT capital. Aircraft lessors grow fastest as leased penetration passes half the global fleet, and each redelivery still triggers a largely manual records reconciliation that digital condition reporting can compress. Independent MROs buy reactively, protecting customer relationships where OEM total-care contracts bundle equivalent tooling, while military and defence operators adopt the slowest because commercial platforms require substantial certification and hosting rework.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA