Diesel Particulate Filter Market (2026 - 2035)

ID: MRFR/AT/4813-HCR 100 Pages Triveni Bhoyar Last Updated: September 15, 2026
Diesel Particulate Filter Market Research Report By Substrate Type (Cordierite, Silicon Carbide, Ceramic Fibre, Aluminium Titanate, Others (Metallic, Sintered)), By Regeneration Process (Passive, Active, Combined Passive-Active), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Off-Highway & Others), By Sales Channel (Original Equipment Manufacturer, Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast to 2035
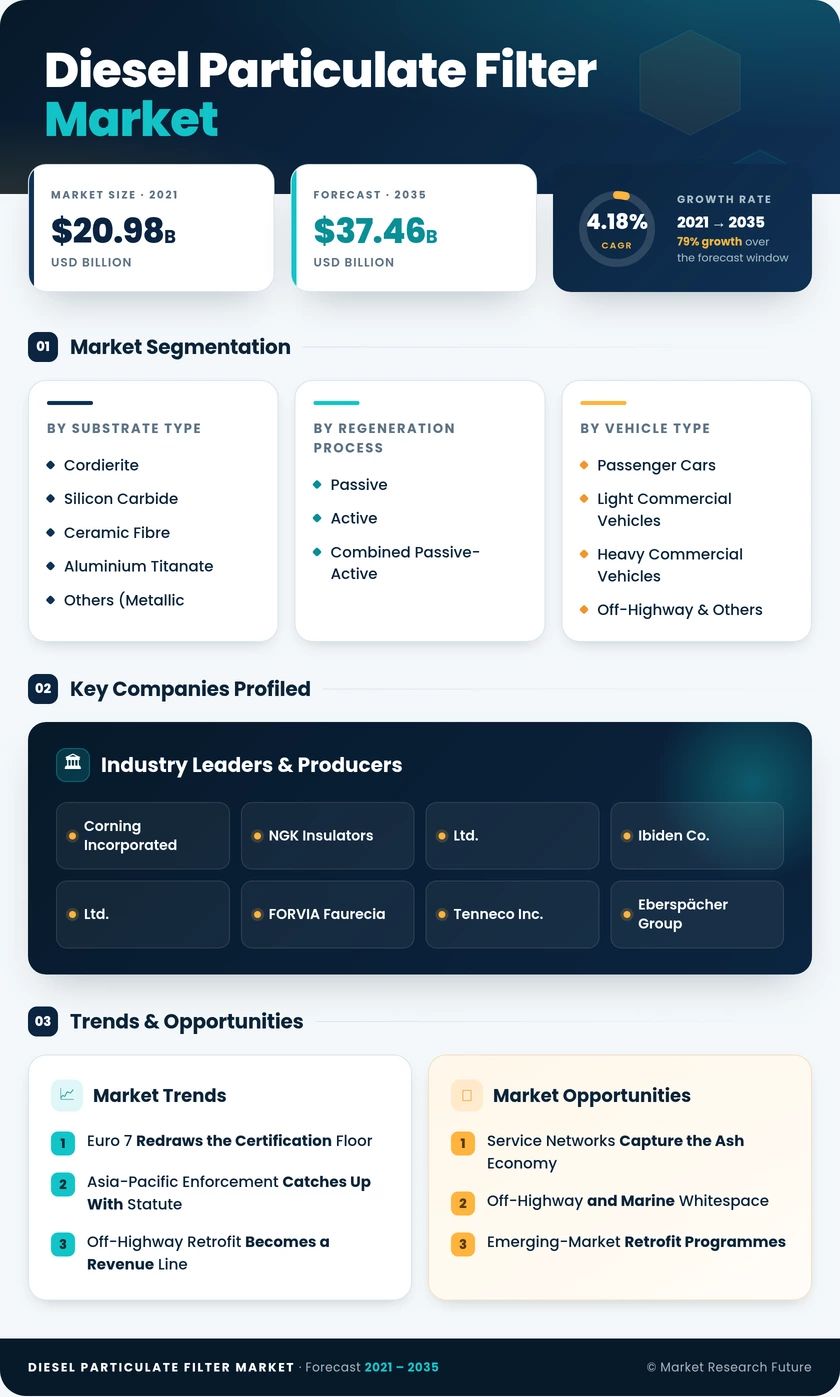
Diesel Particulate Filter Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.18%
2025 Market SizeUSD 24.87 Billion
2035 Market SizeUSD 37.46 Billion
Key Players
Corning Incorporated
NGK Insulators, Ltd.
Ibiden Co., Ltd.
FORVIA Faurecia
Tenneco Inc.
Eberspächer Group
Opportunities
  • Service Networks Capture the Ash Economy
  • Off-Highway and Marine Whitespace
  • Emerging-Market Retrofit Programmes
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Technology |
    2. 2.2 By Sector |
    3. 2.3 By Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Euro 7 Redraws the Certification Floor |
    2. 4.2 Asia-Pacific Enforcement Catches Up With Statute |
    3. 4.3 Off-Highway Retrofit Becomes a Revenue Line |
    4. 4.4 The Replacement Tail Nobody Modelled
  5. 5 Restraints Impact Analysis |
    1. 5.1 Diesel's Retreat From the European Driveway |
    2. 5.2 Zero-Emission Trucking Arrives Unevenly |
    3. 5.3 Precious Metal Exposure Squeezes Coating Margins
  6. 6 Opportunity Analysis |
    1. 6.1 Service Networks Capture the Ash Economy |
    2. 6.2 Off-Highway and Marine Whitespace |
    3. 6.3 Emerging-Market Retrofit Programmes |
    4. 6.4 Telemetry as a Monetisable Asset |
    5. 6.5 Vertical Integration Into Coating |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Predictive Maintenance Displaces Fixed Intervals |
    2. 8.2 Aftermarket Platform Economics |
    3. 8.3 The Electrification Overlay |
    4. 8.4 Sustainability Disclosure Pulls Filtration Into Scope 3
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Substrate Type | |
      1. 9.1.1 Cordierite | |
      2. 9.1.2 Silicon Carbide | |
      3. 9.1.3 Ceramic Fibre | |
      4. 9.1.4 Aluminium Titanate | |
      5. 9.1.5 Others (Metallic, Sintered) |
    2. 9.2 By Regeneration Process | |
      1. 9.2.1 Passive | |
      2. 9.2.2 Active | |
      3. 9.2.3 Combined Passive-Active |
    3. 9.3 By Vehicle Type | |
      1. 9.3.1 Passenger Cars | |
      2. 9.3.2 Light Commercial Vehicles | |
      3. 9.3.3 Heavy Commercial Vehicles | |
      4. 9.3.4 Off-Highway & Others |
    4. 9.4 By Sales Channel | |
      1. 9.4.1 Original Equipment Manufacturer | |
      2. 9.4.2 Aftermarket
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Corning Incorporated | |
      2. 10.3.2 NGK Insulators, Ltd. | |
      3. 10.3.3 Ibiden Co., Ltd. | |
      4. 10.3.4 FORVIA Faurecia | |
      5. 10.3.5 Tenneco Inc. | |
      6. 10.3.6 Eberspächer Group | |
      7. 10.3.7 Denso Corporation | |
      8. 10.3.8 Johnson Matthey plc | |
      9. 10.3.9 Donaldson Company, Inc. | |
      10. 10.3.10 Dinex A/S | |
      11. 10.3.11 Weifu High-Technology Group
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Estimation Framework |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions (FAQs)
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Diesel Particulate Filter Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Market — Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis — Weighting, Geographic Relevance & Timeline |
  19. TABLE 4 Restraint Impact Analysis — Weighting, Geographic Relevance & Timeline |
  20. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Market Size, by Substrate Type, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Market Size, by Regeneration Process, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  29. TABLE 14 Global Market Size, by Sales Channel, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Market Size, by Substrate Type, 2021–2035 (USD Billion) |
  31. TABLE 16 North America Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Market Size, by Substrate Type, 2021–2035 (USD Billion) |
  33. TABLE 18 Europe Market Size, by Sales Channel, 2021–2035 (USD Billion) |
  34. TABLE 19 Asia-Pacific Market Size, by Substrate Type, 2021–2035 (USD Billion) |
  35. TABLE 20 Asia-Pacific Market Size, by Vehicle Type, 2021–2035 (USD Billion) |
  36. TABLE 21 South America Market Size, by Regeneration Process, 2021–2035 (USD Billion) |
  37. TABLE 22 Middle East & Africa Market Size, by Sales Channel, 2021–2035 (USD Billion) |
  38. TABLE 23 Competitive Benchmarking Matrix, 2026 |
  39. TABLE 24 Company Profiles — Key Players |
  40. TABLE 25 Recent Developments & Strategic Announcements, 2023–2025 |
  41. TABLE 26 Report Scope & Methodology Summary |
  42. TABLE 27 Detailed Sources & Citations Index
  43. 16 LIST OF FIGURES |
  44. FIGURE 1 Market Dynamics — Drivers, Restraints, Opportunities & Challenges |
  45. FIGURE 2 Industry Value Chain Analysis |
  46. FIGURE 3 Porter's Five Forces Analysis |
  47. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) |
  48. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 |
  49. FIGURE 6 Market Share by Substrate Type, 2025 vs 2035 |
  50. FIGURE 7 Market Share by Regeneration Process, 2025 vs 2035 |
  51. FIGURE 8 Market Share by Vehicle Type, 2025 vs 2035 |
  52. FIGURE 9 Market Share by Sales Channel, 2025 vs 2035 |
  53. FIGURE 10 Regional Revenue Share Distribution, 2025 |
  54. FIGURE 11 Regional CAGR Comparison, 2026–2035 |
  55. FIGURE 12 Country-Level Revenue Heat Map, 2025 |
  56. FIGURE 13 Competitive Landscape — Revenue Share Positioning, 2026 |
  57. FIGURE 14 Strategic Developments Timeline, 2023–2025 |
  58. FIGURE 15 Regulatory Milestone Roadmap, 2024–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Substrate TypeCordierite; Silicon Carbide; Ceramic Fibre; Aluminium Titanate; Others (Metallic, Sintered)CordieriteSilicon Carbide
By Regeneration ProcessPassive; Active; Combined Passive-ActivePassiveCombined Passive-Active
By Vehicle TypePassenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles; Off-Highway & OthersPassenger CarsHeavy Commercial Vehicles
By Sales ChannelOriginal Equipment Manufacturer; AftermarketOriginal Equipment ManufacturerAftermarket
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaEuropeAsia-Pacific


Market Segmentation Overview

By Substrate Type

Sub-SegmentKey Trend
CordieriteHolds volume leadership on cost, but loses share on high-duty platforms
Silicon CarbideSegmented block designs gain on Euro 7 and Tier 5 thermal requirements.
Ceramic FibrePreferred where low backpressure matters more than filtration efficiency
Aluminium TitanateNear-zero thermal expansion supports compact light-duty packaging.
Others (Metallic, Sintered)Niche marine, rail, and stationary genset installations


Substrate selection is increasingly a duty-cycle decision rather than a price decision. Fleets running predictable highway loads still specify cordierite; anyone facing irregular regeneration behaviour pays the silicon-carbide premium and treats it as insurance against substrate cracking.

By Regeneration Process

Sub-SegmentKey Trend
PassiveContinuous oxidation suits long-haul cycles with sustained exhaust heat
ActiveFuel dosing or burner assistance covers low-load and cold-climate operation.
Combined Passive-ActiveHybrid control logic minimises fuel penalty across mixed urban duty.


Urban logistics growth is the single biggest force behind hybrid regeneration adoption. Delivery duty cycles rarely sustain the exhaust temperatures passive systems require, and pure active dosing costs fuel that operators track closely.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsStructural decline in Europe offset partially by Indian diesel volumes
Light Commercial VehiclesLast-mile fleet expansion sustains steady unit demand.
Heavy Commercial VehiclesExtended useful-life mandates raise content value per vehicle.
Off-Highway & OthersRetrofit rules in construction, agriculture, and mining open new demand


Value migrates upward through the weight classes across this decade. Larger engines require greater filtration volume and premium substrates, so heavy-duty and off-highway categories contribute disproportionately to revenue growth even where unit counts grow modestly.

By Sales Channel

Sub-SegmentKey Trend
Original Equipment ManufacturerBundled aftertreatment supply tied to type-approval relationships
AftermarketAsh saturation, inspection failures, and remanufacturing drive replacement


Channel economics are inverting. New-vehicle fitment plateaus with diesel's declining share of light-vehicle sales, while the ageing installed base generates a widening replacement and service pool that independent networks are best positioned to capture.

By Geography

Sub-SegmentKey Trend
North AmericaOff-road Tier 5 and 2027 heavy-duty durability rules lead demand
EuropeLargest installed base; Euro 7 and inspection reform sustain volumes
Asia-PacificFastest expansion on Chinese and Indian heavy-duty enforcement
South AmericaProconve P8 brings filtration into mainstream heavy-duty specification.
Middle East & AfricaMining exposure limits and construction fleets create niche pull demand.


Regional balance shifts steadily eastward. Europe's leadership rests on legacy density that erodes each year, while Asia-Pacific converts regulatory enforcement into genuine incremental fitment across the world's largest commercial-vehicle production base.



Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.