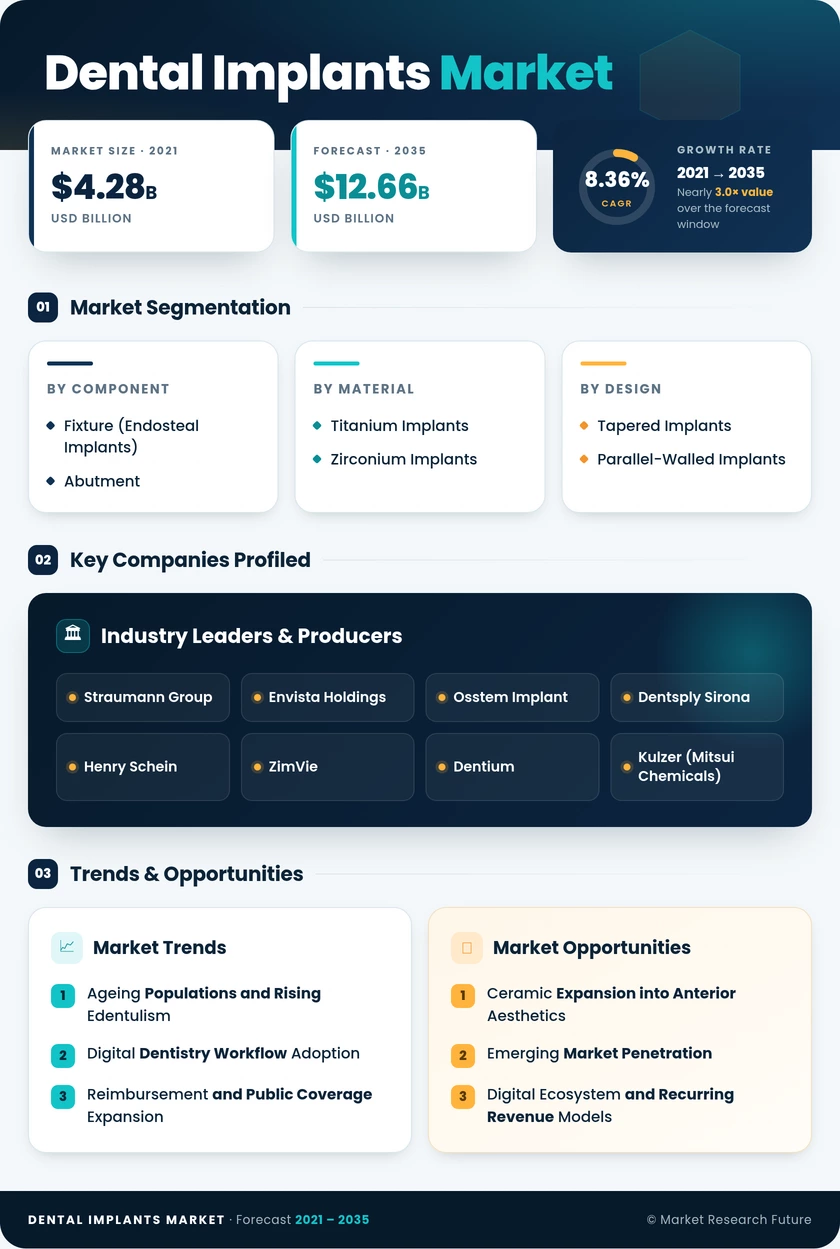
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Component | Fixture (Endosteal Implants), Abutment | Fixture — 71.0% share (2025) | Abutment — 9.90% CAGR (2026–2035) |
| By Material | Titanium Implants, Zirconium Implants | Titanium Implants — 80.4% share (2025) | Zirconium Implants — 11.61% CAGR (2026–2035) |
| By Design | Tapered Implants, Parallel-Walled Implants | Tapered Implants — 65.5% share (2025) | Parallel-Walled Implants — 9.49% CAGR (2026–2035) |
| By Procedure Type | Immediate-Load Implant, Conventional | Conventional — 61.2% share (2025) | Immediate-Load Implant — 12.52% CAGR (2026–2035) |
| By End User | Dental Hospitals & Clinics, Dental Laboratories, Other End Users | Dental Hospitals & Clinics — 51.8% share (2025) | Dental Laboratories — 10.38% CAGR (2026–2035) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
| Fixture (Endosteal Implants) | Surface chemistry differentiation shortens osseointegration timelines |
| Abutment | Centralised five-axis milling replaces stock component inventories. |
Fixtures lead this dimension at 71.0% share because every restoration requires an endosteal anchor, and subperiosteal alternatives survive only in severe atrophy cases where grafting is contraindicated. Abutments grow fastest at a 9.90% CAGR as laboratory hubs mill patient-specific components within hours, eliminating the compromise of stock parts. Screw-retained custom designs also reduce cement-related peri-implant inflammation, giving clinicians a clinical rather than purely economic reason to upgrade.
By Material
| Sub-Segment | Key Trend |
| Titanium Implants | Grade 4 and grade 5 alloys remain the clinical evidence benchmark |
| Zirconium Implants | Yttria-stabilised formulations reduce brittleness and widen indications. |
Titanium holds an 80.4% share in the depth of long-term survival documentation and a manufacturing cost base ceramic cannot yet match. Zirconium implants advance at an 11.61% CAGR because they resolve grey show-through beneath thin gingival biotypes, a limitation titanium cannot engineer away. Hot-isostatic pressing keeps ceramic unit costs materially higher, confining adoption to maxillary anterior indications where patients accept aesthetic premiums.
By Design
| Sub-Segment | Key Trend |
| Tapered Implants | Conical geometry sustains insertion torque for same-day placement |
| Parallel-Walled Implants | Slimmer profiles serve narrow-ridge and root-proximity anatomy. |
Tapered fixtures dominate at 65.5% share because their macro-geometry generates the primary stability immediate loading demands, particularly in softer maxillary bone. Parallel-walled implants grow faster at a 9.49% CAGR as clinicians treat lower incisor and upper premolar sites where inter-radicular space cannot accommodate a flared coronal profile. Hybrid geometries pairing apical taper with coronal parallelism now let manufacturers cover both anatomies while trimming SKU counts.
By Procedure Type
| Sub-Segment | Key Trend |
| Immediate-Load Implant | AI-optimised torque targets and occlusal management reduce failure risk |
| Conventional | Staged healing remains standard in compromised bone and medical risk. |
Conventional two-stage protocols retain 61.2% of volume because they remain the defensible option in Type IV bone, heavy bruxism and uncontrolled diabetes. Immediate-load procedures expand at a 12.52% CAGR, the steepest rate in the report, concentrated in full-arch cases where cross-arch splinting distributes micromotion. Payers favour same-day work because fewer appointments lower total episode cost, and patients avoid the removable interim phase entirely.
By End User
| Sub-Segment | Key Trend |
| Dental Hospitals & Clinics | Chairside scanning and guided surgery expand in-practice capability |
| Dental Laboratories | Regional hubs run 24-hour milling and printing for network practices. |
| Other End Users | Teaching hospitals shape graduating clinicians' platform preferences. |
Dental hospitals and clinics command 51.8% of spend because both surgical placement and prosthetic seating happen chairside. Dental laboratories post the fastest 10.38% CAGR as service organisations route design and fabrication to centralised hubs, converting craft workshops into industrial operations with measurable tolerance control. Academic and military channels stay small in revenue terms but carry outsized influence, since platform familiarity acquired in training persists across a clinician's career.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA