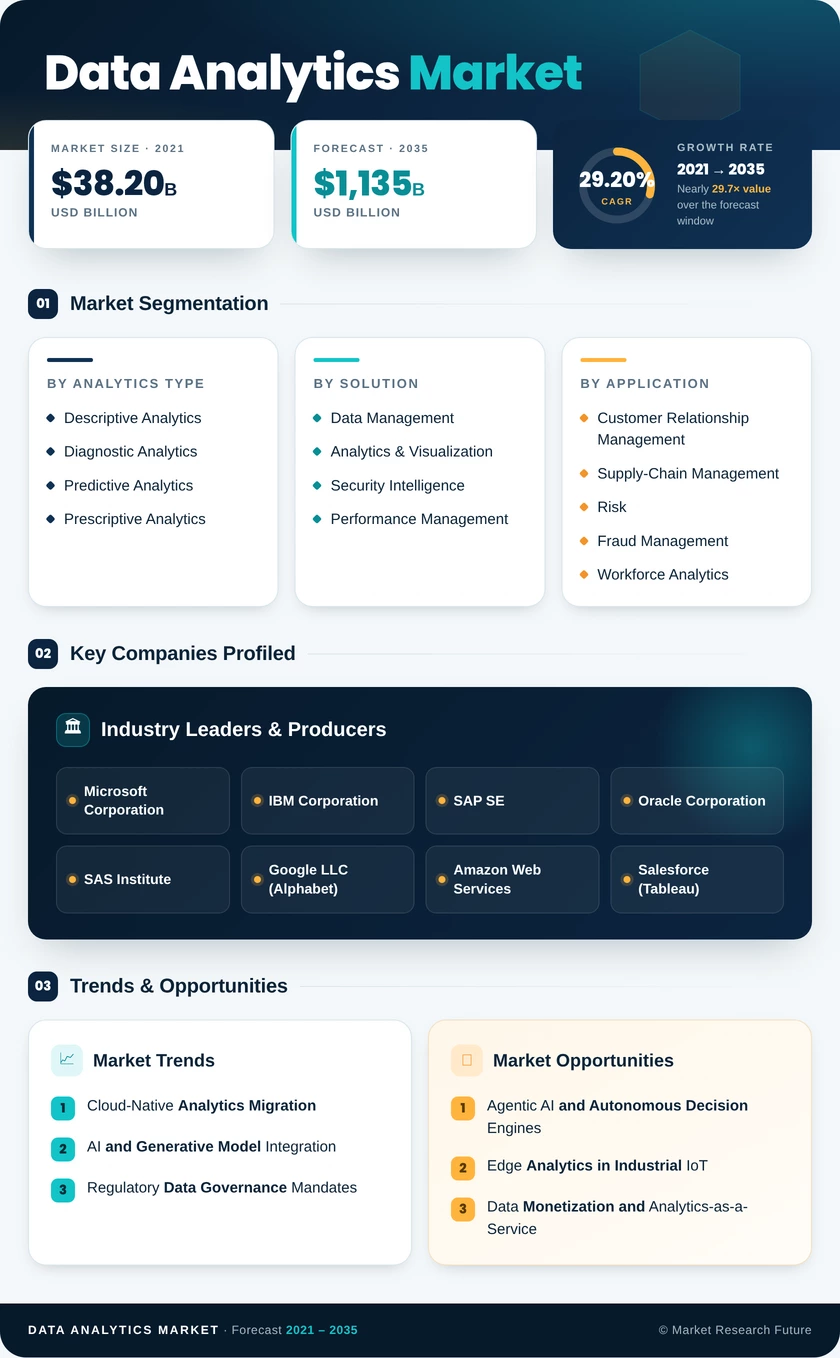
Data Analytics Market (2026 – 2035)

ID: MRFR/ICT/1157-CR 110 Pages Apoorva Priyadarshi Last Updated: September 15, 2026
Data Analytics Market Size, Share and Research Report By Analytics Type (Descriptive Analytics, Diagnostic Analytics, Predictive Analytics, Prescriptive Analytics), By Solution (Data Management, Analytics & Visualization, Security Intelligence, Performance Management), By Application (Customer Relationship Management, Supply-Chain Management, Risk and Fraud Management, Workforce Analytics, Human Resource Management, Marketing and Sales Optimization, Asset and Operations Management, Other Applications), By Deployment Model (On-Premises, Cloud), By Organization Size (Large Enterprises, Small and Medium Enterprises (SMEs)), By End-User Industry (Information Technology and Telecom, Banking, Financial Services, and Insurance (BFSI), Healthcare, Retail, Manufacturing, Government, Energy, Others) and By Regional (North America, Europe, South America, South Africa, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
Data Analytics Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)29.20%
2025 Market SizeUSD 87.50 Billion
2035 Market SizeUSD 1,135.00 Billion
Key Players
Microsoft Corporation
IBM Corporation
SAP SE
Oracle Corporation
SAS Institute
Google LLC
Opportunities
  • Agentic AI and Autonomous Decision Engines
  • Edge Analytics in Industrial IoT
  • Data Monetization and Analytics-as-a-Service
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Cloud-Native Analytics Migration | |
      2. 3.1.2 AI and Generative Model Integration | |
      3. 3.1.3 Regulatory Data Governance Mandates | |
      4. 3.1.4 Real-Time Decision-Support Demand | |
      5. 3.1.5 Enterprise Data Volume Explosion | |
      6. 3.1.6 Digital Twin and IoT Convergence | |
      7. 3.1.7 SME Self-Service Analytics Expansion |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 Data Privacy and Cross-Border Restrictions | |
      2. 3.2.2 Talent Shortage in Data Engineering | |
      3. 3.2.3 Legacy System Integration Complexity | |
      4. 3.2.4 Cybersecurity and Data Breach Risk | |
      5. 3.2.5 Vendor Lock-In and Interoperability Gaps |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Agentic AI and Autonomous Decision Engines | |
      2. 3.3.2 Edge Analytics in Industrial IoT | |
      3. 3.3.3 Data Monetization and Analytics-as-a-Service | |
      4. 3.3.4 Emerging Market Digital Infrastructure Buildout | |
      5. 3.3.5 Sustainability and ESG Analytics |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global Data Analytics Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Analytics Type | |
      1. 5.1.1 Descriptive Analytics | |
      2. 5.1.2 Diagnostic Analytics | |
      3. 5.1.3 Predictive Analytics | |
      4. 5.1.4 Prescriptive Analytics |
    2. 5.2 By Solution | |
      1. 5.2.1 Data Management | |
      2. 5.2.2 Analytics & Visualization | |
      3. 5.2.3 Security Intelligence | |
      4. 5.2.4 Performance Management |
    3. 5.3 By Application | |
      1. 5.3.1 Customer Relationship Management | |
      2. 5.3.2 Supply-Chain Management | |
      3. 5.3.3 Risk and Fraud Management | |
      4. 5.3.4 Workforce Analytics | |
      5. 5.3.5 Human Resource Management | |
      6. 5.3.6 Marketing and Sales Optimisation | |
      7. 5.3.7 Asset and Operations Management | |
      8. 5.3.8 Other Applications |
    4. 5.4 By Deployment Model | |
      1. 5.4.1 On-Premises | |
      2. 5.4.2 Cloud |
    5. 5.5 By Organization Size | |
      1. 5.5.1 Large Enterprises | |
      2. 5.5.2 Small and Medium Enterprises (SMEs) |
    6. 5.6 By End-User Industry | |
      1. 5.6.1 Information Technology and Telecom | |
      2. 5.6.2 Banking, Financial Services, and Insurance (BFSI) | |
      3. 5.6.3 Healthcare | |
      4. 5.6.4 Retail | |
      5. 5.6.5 Manufacturing | |
      6. 5.6.6 Government | |
      7. 5.6.7 Energy | |
      8. 5.6.8 Others
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Microsoft Corporation | |
      2. 7.3.2 IBM Corporation | |
      3. 7.3.3 SAP SE | |
      4. 7.3.4 Oracle Corporation | |
      5. 7.3.5 SAS Institute | |
      6. 7.3.6 Google LLC (Alphabet) | |
      7. 7.3.7 Amazon Web Services | |
      8. 7.3.8 Salesforce (Tableau) | |
      9. 7.3.9 Qlik Technologies | |
      10. 7.3.10 Teradata Corporation | |
      11. 7.3.11 Cloudera | |
      12. 7.3.12 MicroStrategy
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 AI-Native Analytics and Autonomous Insight Generation |
    2. 8.2 Composable Data Architecture and Platform Economics |
    3. 8.3 Sovereign Analytics and Data Localization |
    4. 8.4 Sustainability-Integrated Decision Intelligence
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global Data Analytics Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global Data Analytics Market — Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Global Data Analytics Market — Driver Impact Analysis |
  16. TABLE 4 Global Data Analytics Market — Restraint Impact Analysis |
  17. TABLE 5 Global Data Analytics Market Size, by Analytics Type, 2021–2035 (USD Billion) |
  18. TABLE 6 Global Data Analytics Market Size, by Solution, 2021–2035 (USD Billion) |
  19. TABLE 7 Global Data Analytics Market Size, by Application, 2021–2035 (USD Billion) |
  20. TABLE 8 Global Data Analytics Market Size, by Deployment Model, 2021–2035 (USD Billion) |
  21. TABLE 9 Global Data Analytics Market Size, by Organization Size, 2021–2035 (USD Billion) |
  22. TABLE 10 Global Data Analytics Market Size, by End-User Industry, 2021–2035 (USD Billion) |
  23. TABLE 11 Global Data Analytics Market Size, by Region, 2021–2035 (USD Billion) |
  24. TABLE 12 North America Data Analytics Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 13 Europe Data Analytics Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 14 Asia-Pacific Data Analytics Market Size, by Country, 2021–2035 (USD Billion) |
  27. TABLE 15 South America Data Analytics Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 16 Middle East & Africa Data Analytics Market Size, by Country, 2021–2035 (USD Billion) |
  29. TABLE 17 Competitive Benchmarking Matrix — Global Data Analytics Market, 2025 |
  30. TABLE 18 Company Profiles — Key Players, Global Data Analytics Market |
  31. TABLE 19 Recent Developments & Strategic Announcements, 2024–2025 |
  32. TABLE 20 Report Scope & Methodology Summary |
  33. TABLE 21 Detailed Sources and Citations
  34. 13 LIST OF FIGURES |
  35. FIGURE 1 Global Data Analytics Market Dynamics — Drivers, Restraints, and Opportunities |
  36. FIGURE 2 Industry Value Chain Analysis — Data Analytics Market |
  37. FIGURE 3 Porter's Five Forces Analysis — Data Analytics Market |
  38. FIGURE 4 Global Data Analytics Market Size Trend & Forecast (USD Billion), 2021–2035 |
  39. FIGURE 5 Data Analytics Market Share, by Analytics Type (%), 2025 |
  40. FIGURE 6 Data Analytics Market Share, by Solution (%), 2025 |
  41. FIGURE 7 Data Analytics Market Share, by Application (%), 2025 |
  42. FIGURE 8 Data Analytics Market Share, by Deployment Model (%), 2025 |
  43. FIGURE 9 Data Analytics Market Share, by Organization Size (%), 2025 |
  44. FIGURE 10 Data Analytics Market Share, by End-User Industry (%), 2025 |
  45. FIGURE 11 Data Analytics Market Share, by Region (%), 2025 |
  46. FIGURE 12 North America Data Analytics Market Size, by Country (USD Billion), 2021–2035 |
  47. FIGURE 13 Europe Data Analytics Market Size, by Country (USD Billion), 2021–2035 |
  48. FIGURE 14 Asia-Pacific Data Analytics Market Size, by Country (USD Billion), 2021–2035 |
  49. FIGURE 15 South America Data Analytics Market Size, by Country (USD Billion), 2021–2035 |
  50. FIGURE 16 Middle East & Africa Data Analytics Market Size, by Country (USD Billion), 2021–2035 |
  51. FIGURE 17 Competitive Landscape — Market Share Heatmap, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
Analytics TypeDescriptive Analytics, Diagnostic Analytics, Predictive Analytics, Prescriptive AnalyticsDescriptive AnalyticsPrescriptive Analytics
SolutionData Management, Analytics & Visualization, Security Intelligence, Performance ManagementData ManagementSecurity Intelligence
ApplicationCustomer Relationship Management, Supply-Chain Management, Risk and Fraud Management, Workforce AnalyticsCustomer Relationship ManagementRisk and Fraud Management
Deployment ModelOn-Premises, CloudOn-PremisesCloud
Organization SizeLarge Enterprises, Small and Medium Enterprises (SMEs)Large EnterprisesSmall and Medium Enterprises (SMEs)
End-User IndustryIT and Telecom, BFSI, Healthcare, Retail, Manufacturing, Government, EnergyIT and TelecomHealthcare
GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Analytics Type

Sub-SegmentKey Trend
Descriptive AnalyticsCommoditizing as embedded dashboards become standard in SaaS platforms
Diagnostic AnalyticsGrowing demand for root-cause analysis in manufacturing quality control
Predictive AnalyticsMachine-learning model integration accelerating adoption in finance and retail
Prescriptive AnalyticsAgentic AI enabling closed-loop automated decision execution


Descriptive and Diagnostic Analytics remain the operational backbone of most enterprise analytics stacks, serving compliance, reporting, and retrospective analysis needs. Predictive and Prescriptive Analytics are gaining share as AI-model deployment matures and organizations seek forward-looking decision support.

By Solution

Sub-SegmentKey Trend
Data ManagementData fabric and mesh architectures replacing centralized ETL pipelines
Analytics & VisualizationNatural-language querying expanding self-service user base
Security IntelligenceBehaviour-based threat detection replacing signature-based approaches
Performance ManagementCFO-office adoption of integrated financial planning analytics


Data Management continues to anchor enterprise analytics spending as data governance, cataloguing, and quality assurance become regulatory imperatives. Security Intelligence is the fastest-growing solution category, driven by increasing cyber-threat sophistication and SOC automation requirements.

By Application

Sub-SegmentKey Trend
Customer Relationship ManagementReal-time personalization engines driving retention and upsell
Supply-Chain ManagementPost-pandemic resilience analytics and multi-tier visibility platforms
Risk and Fraud ManagementDigital payments growth fuelling real-time fraud-detection demand
Workforce AnalyticsHybrid and remote work models increasing demand for productivity measurement


Customer Relationship Management holds the largest application share, supported by the proliferation of omnichannel customer-engagement strategies. Risk and Fraud Management is growing fastest as digital transaction volumes and regulatory scrutiny escalate simultaneously.

By Deployment Model

Sub-SegmentKey Trend
On-PremisesRetained in defense, intelligence, and highly regulated banking environments
CloudMulti-cloud and hybrid strategies becoming default enterprise procurement model


On-Premises deployments maintain majority share in verticals where data-sovereignty and air-gapped security requirements prohibit cloud migration. Cloud deployment is rapidly expanding as hyperscale providers offer consumption-based pricing, serverless query engines, and built-in AI services.

By Organization Size

Sub-SegmentKey Trend
Large EnterprisesMulti-department analytics center-of-excellence models becoming standard
Small and Medium Enterprises (SMEs)Low-code/no-code platforms reducing analytics adoption barriers


Large Enterprises dominate by revenue share due to complex, multi-geography analytics requirements. SMEs represent the fastest-growing segment as affordable cloud-based platforms and embedded analytics modules democratize access to advanced capabilities.

By End-User Industry

Sub-SegmentKey Trend
Information Technology and TelecomNetwork optimization and customer-experience analytics at scale
Banking, Financial Services, and Insurance (BFSI)Regulatory reporting automation and credit-scoring model refinement
HealthcareClinical decision support and population-health management expansion
RetailOmnichannel analytics unifying in-store, online, and mobile channels
ManufacturingPredictive maintenance and digital-twin analytics adoption
GovernmentCitizen-services optimization and open-data transparency initiatives
EnergyGrid optimization, carbon-tracking, and asset-performance monitoring


IT and Telecom leads by share given the sector's inherent data intensity and dual role as both analytics consumer and provider. Healthcare is the fastest-growing vertical, propelled by electronic health record maturation, genomic analytics, and the transition to value-based care reimbursement models.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.