Customer Journey Analytics Market (2026 - 2035)

Customer Journey Analytics Market Size, Share and Research Report By Identity Resolution Decay in Browser-Restricted Environments, By Data Sovereignty and Residency Constraints, By Consumption Pricing Unpredictability, By Journey Analytics Engineering Talent Scarcity and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/3118-HCR 200 Pages Aarti Dhapte Last Updated: September 10, 2026
Customer Journey Analytics Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)17.10%
2025 Market SizeUSD 19.62 Billion
2035 Market SizeUSD 95.90 Billion
Key Players
Adobe
Salesforce
Google
Microsoft
Oracle
SAS Institute
Opportunities
  • Agentic Orchestration as a Premium Tier
  • Warehouse-Native Deployment for Regulated Buyers
  • Emerging-Market SME Adoption

Customer Journey Analytics Market Summary

The Customer Journey Analytics Market was valued at USD 19.62 Billion in 2025 and opens the forecast window at USD 23.17 Billion in 2026, reaching USD 95.90 Billion by 2035 at a 17.10% CAGR. Two catalysts sit underneath that curve. India's Digital Personal Data Protection Rules, notified on November 13, 2025, with full compliance due May 13, 2027, have forced consent architecture onto capital plans across Asian consumer businesses [13]. Enterprise AI budgets have done the rest, pulling journey intelligence out of marketing and into shared data infrastructure.

Warehouse-native platforms that combine digital and non-digital events into person-level profiles are replacing legacy web analytics stacks, which are session-scoped, cookie-dependent, and isolated from the contact center. At Dreamforce 2025, Salesforce rebranded Data Cloud as Data 360 and positioned it as the foundation for its agentic offerings [8]. Omnichannel consumer touchpoint tracking spanning web, app, call center, and in-store records is now included in Adobe's platform [5].

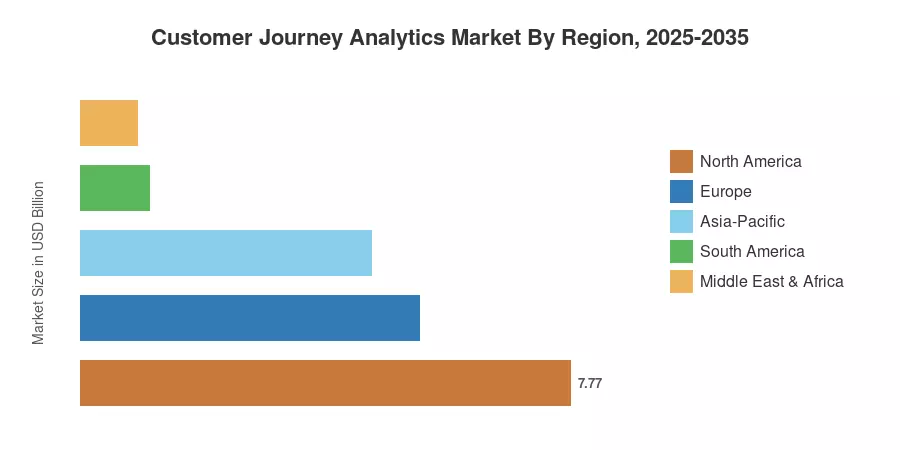
Due to established retail media economics and platform vendor concentration, North America commands 39.6% of the Customer Journey Analytics Market. Asia-Pacific compounds at the greatest rate (23.5%) through 2035, driven by digital-first banking and consent-manager mandates. Europe is in second with a share of 27.4%, as GDPR enforcement has turned auditable consent lineage from a compliance afterthought into a purchasing criterion. Vendor differentiation will depend more on how well a platform absorbs regulated, non-digital data than on visualization.


Key Report Takeaways

• By Technology

  • Cloud deployment captured 57.9% of the Customer Journey Analytics Market in 2025 as elastic compute became a prerequisite for sub-second decisioning
  • Services will expand at a 21.7% CAGR through 2035 as implementation complexity outpaces internal capability.
  • Hybrid architectures account for USD 3.08 Billion of 2025 spend, concentrated in regulated verticals.

• By End-user

  • BFSI held 24.2% share in 2025, the largest single vertical in the Customer Journey Analytics Market
  • Retail and eCommerce grows fastest at a 26.3% CAGR to 2035
  • Small and medium enterprises will post a 24.4% CAGR as packaged SaaS tiers lower entry cost

• By Region

  • North America contributed USD 7.77 billion in 2025
  • Asia-Pacific advances at 23.5% CAGR, the fastest of any region
  • Europe holds 27.4% share, anchored by consent-governance investment


Market Size and Forecast (2021–2035)

Estimates combine vendor revenue disclosures from public filings, channel-partner interviews, and bottom-up event-volume modelling calibrated against published platform pricing. Historical years reflect reported subscription and services revenue attributable to journey analytics workloads; forecast years apply consumption-growth assumptions tested against enterprise IT budget surveys. The Customer Journey Analytics Market series below is expressed in USD Billion throughout.
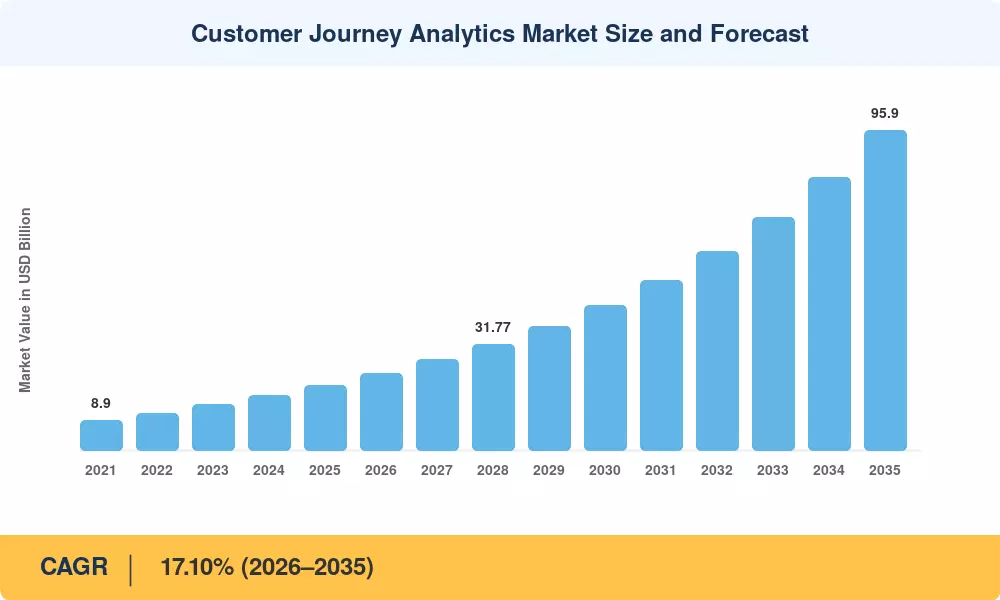
Customer Journey Analytics Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Agentic and generative AI embedded in CX platforms 3.1 Global Short-term (≤2 yr)
First-party data consolidation and consent infrastructure 2.6 Global Medium-term (2–4 yr)
Warehouse-native and zero-copy federation architectures 2.3 North America, Europe Medium-term (2–4 yr)
Contact-centre and digital channel convergence 1.9 Global Medium-term (2–4 yr)
Retail media and commerce personalisation economics 1.7 Asia-Pacific, North America Long-term (≥4 yr)
Regulatory consent mandates 1.4 Asia-Pacific, Europe Long-term (≥4 yr)
SME adoption via packaged SaaS tiers 1.1 Asia-Pacific, South America Long-term (≥4 yr)


Agentic AI Moves Journey Analytics From Reporting to Action

Salesforce brought Agentforce to general availability in October 2024 and made its unified data layer the grounding substrate for every agent, then formalised the architecture as Data 360 at Dreamforce 2025 [8][9]. That shift changes what buyers purchase. Analytics that only describe behaviour lose budget to platforms that trigger the next action within the same runtime. Adobe made the same argument when it was named a Leader in the inaugural March 2026 Magic Quadrant, framing analytics and orchestration as one discipline [3]. Vendors in the Customer Journey Analytics Market without a decisioning layer now compete as feature suppliers.

Consent Infrastructure Became a Budget Line, Not a Legal Task

Regulatory build-out is now measurable capital expenditure. India's DPDP Rules established the Data Protection Board on November 13, 2025, opened Consent Manager registration from November 13, 2026 and impose full substantive compliance by May 13, 2027, with penalties reaching ₹250 crore per breach category [13][14]. Enterprises serving Indian consumers must reconcile legacy data against valid notice and consent — a data-lineage problem that journey platforms are being bought to solve. European buyers face the equivalent question under GDPR, where consent provenance must survive audit.

The Cookie Reversal Reshaped, Rather Than Removed, Demand

Google confirmed on April 22 2025, that Chrome would keep third-party cookies and abandon the planned choice prompt, then retired the remaining Privacy Sandbox APIs in October 2025, with Chrome removal targeted through July 2026 [1][2][20]. Deprecation did not arrive. Fragmentation did. Safari has blocked third-party cookies by default since 2020, so measurement gaps persist across the browser estate even with Chrome unchanged. Buyers responded by investing in authenticated first-party identity rather than waiting for a replacement standard.

Non-Digital Channels Widened the Addressable Workload

Journeys rarely stay online. Branch visits, contact-centre calls, loyalty scans and partner channels generate the events that explain abandonment, and platforms able to ingest them command premium pricing. CSG cited a US bank deployment delivering a 12% reduction in inbound calls, a 25% drop in fraud cases and USD 30 million in financial impact [4]. Results of that shape justify enterprise licence tiers, and they depend entirely on stitching non-digital records to digital identity.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Identity resolution decay in browser-restricted environments −1.8 Global Short-term (≤2 yr)
Data sovereignty and residency constraints on cloud migration −1.5 Asia-Pacific, Middle East Medium-term (2–4 yr)
Consumption pricing unpredictability and TCO overruns −1.3 Global Short-term (≤2 yr)
Scarcity of journey analytics engineering talent −1.1 Global Medium-term (2–4 yr)
Post-Privacy Sandbox attribution credibility gap −0.9 North America, Europe Long-term (≥4 yr)


Measurement Confidence Has Not Recovered

Marketers reported material difficulty tracking behaviour across channels and attributing outcomes during the Privacy Sandbox transition, with roughly two-thirds citing cross-channel tracking as a primary obstacle and a comparable share flagging attribution and measurement problems [19]. Retiring the APIs resolved the uncertainty without resolving the underlying gap. Deals now stall in proof of concept when vendors cannot demonstrate defensible match rates on unauthenticated traffic.

Residency Rules Slow the Cloud Default

Elastic compute suits real-time scoring, yet regulated buyers cannot always use it. Indian financial institutions preparing for the May 2027 DPDP deadline, Gulf public-sector entities, and European insurers frequently require in-country processing, which pushes deployments toward hybrid topologies that cost more and ship slower [13][14]. Vendors without local cloud regions lose on procurement screening before capability review begins.

Consumption Billing Creates Budget Variance

Event-volume pricing rewards vendors when adoption succeeds. Finance teams experience the same success as an overrun. Platforms billing on profiles, events and compute units produce year-two invoices that routinely exceed the modelled case, and the resulting renegotiations lengthen sales cycles across the mid-market [17].


Customer Journey Analytics Market Opportunities

Agentic Orchestration as a Premium Tier

Platforms that propose journey logic — rather than execute logic a marketer defines — represent a distinct product category with distinct pricing power. Vendors converting descriptive dashboards into autonomous next-best-action engines can defend enterprise pricing as commodity analytics deflates.

Warehouse-Native Deployment for Regulated Buyers

Zero-copy federation onto Snowflake, Databricks and BigQuery lets data stay where governance already lives [7] for banks and insurers, which removes the residency objection that blocks conventional SaaS ingestion. Suppliers offering credible federated architectures gain access to the segment of the Customer Journey Analytics Market that has resisted cloud migration entirely.

Emerging-Market SME Adoption

India, ASEAN and Brazil host large populations of digitally native mid-market retailers and lenders that cannot fund enterprise licences. Packaged tiers priced against a capped event ceiling open a segment growing at 24.4% CAGR. Consent-manager interoperability requirements in India from November 2026 give these buyers a compliance reason to purchase rather than a marketing one [13].

Data Collaboration and Retail Media Monetisation

Retailers and telecom operators sit on authenticated first-party data that advertisers will pay to reach. Clean-room collaboration turns journey infrastructure from a cost centre into a revenue line, and platforms supporting privacy-preserving joins capture a share of that economics [10]. Real-time customer behaviour analytics underpins the audience quality these networks sell.

Non-Digital Event Ingestion

Voice transcripts, branch systems and field-service records remain the largest unstitched data class in most deployments. Vendors solving schema mapping for these sources unlock verticals — insurance, healthcare, utilities — where the majority of decisive interactions never touch a browser [4].


Customer Journey Analytics Market Future Outlook

Autonomous Journey Operations

By the early 2030s, the meaningful distinction will sit between platforms that surface insight and platforms that act on it without human staging. Salesforce made unified data the grounding layer for autonomous agents, and Adobe built its 2026 Leader position on merging analytics with orchestration [3][8]. The Customer Journey Analytics Market will reprice accordingly: descriptive dashboards deflate toward commodity, while decisioning runtimes hold enterprise margin.

Platform Economics and Consolidation

Consolidation has been continuous rather than episodic. Contentsquare absorbed Hotjar in 2021 and Heap in 2023; Contentstack acquired Lytics in December 2024 [11]. Ecosystem depth creates switching costs, and switching costs concentrate spend among a small set of suite vendors. Expect independent point solutions to be acquired into orchestration platforms rather than to scale alone.

Privacy Architecture as Durable Infrastructure

Google's retreat from Privacy Sandbox did not restore the pre-2020 measurement environment; it confirmed that no industry-wide replacement is arriving [2][20]. Enterprises will keep building authenticated identity graphs, consent ledgers and clean rooms because those assets work regardless of browser policy. Regulatory timetables in India and the EU give this investment a compliance floor independent of advertising economics.

Outcome-Based Commercial Models

Vendors publishing quantified impact — CSG's disclosed 12% call reduction and USD 30 million financial impact at a US bank is representative — invite outcome-linked contracting [4]. Buyers will push a portion of licence value onto measured results, and the Customer Journey Analytics Market will develop shared measurement conventions to make those contracts enforceable.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 39.6% share Agentic orchestration, retail media, contact-centre convergence
Europe 27.4% share Consent lineage, GDPR audit readiness, sovereign cloud
Asia-Pacific 23.5% CAGR (2026–2035) DPDP compliance, digital banking, mobile-first commerce
South America USD 1.10 Billion Retail personalisation, fintech onboarding journeys
Middle East & Africa USD 0.90 Billion Government CX programmes, telecom digitisation
Total USD 19.62 Billion

Regional performance in the Customer Journey Analytics Market tracks two variables: platform vendor proximity and the maturity of domestic consent regulation. North America benefits from both. Asia-Pacific compounds fastest because regulation arrived after digital scale, forcing retrofit investment across large installed bases.


North America

Country Metric Key Driver
US USD 6.41 Billion Platform vendor concentration and retail media buildout
Canada 11.9% share of region Banking CX modernisation under federal privacy reform
Mexico 18.9% CAGR Nearshoring-driven eCommerce expansion


United States demand is unusual in that supply and demand share a geography. Adobe, Salesforce, Google, Microsoft and Oracle are headquartered here, and their largest reference accounts do too, which compresses the gap between roadmap and deployment. The Customer Journey Analytics Market in this region is also the first to absorb agentic pricing models, since consumption billing on AI inference was piloted with North American enterprise accounts before wider release [8].

Europe

Country Metric Key Driver
Germany 22.6% share of region Manufacturing and insurance CX programmes
UK USD 1.19 Billion Financial services personalisation
France 16.4% share of region Domestic experience analytics vendor base
Italy 15.1% CAGR Retail banking digitisation
Spain 8.7% share of region Telecom and travel journey optimisation
Nordic Countries 15.9% CAGR Public-sector digital service design
Russia 3.1% share of region Localised deployment under domestic data rules
Rest of Europe USD 0.61 Billion Cross-border eCommerce


European buying behaviour is shaped by audit exposure. GDPR obliges controllers to evidence lawful basis for processing, so platforms must reconstruct consent state at the moment each event was captured — a materially harder requirement than storing a consent flag. France also supplies domestic capability: Contentsquare, founded in Paris, expanded from digital experience into product analytics by completing its acquisition of Heap in December 2023 [11]. That combination of regulatory pressure and local supply keeps European share resilient despite slower headline growth.

Asia-Pacific

Country Metric Key Driver
China 28.4% share of region Super-app commerce journey optimisation
India 26.9% CAGR DPDP Rules compliance and consent manager mandate
Japan USD 0.71 Billion Retail and automotive loyalty programmes
South Korea 11.2% share of region Telecom and gaming personalisation
ASEAN 24.8% CAGR Digital banking licence expansion
Rest of Asia-Pacific 6.4% share of region Cross-border marketplace growth


India anchors the region's growth in the Customer Journey Analytics Market. Consent Manager registration opens November 13, 2026, and full DPDP compliance falls due May 13, 2027, with no grace period expected and penalties stacking per violation category [13][14][21]. That timetable converts a discretionary marketing purchase into a board-level remediation programme, particularly for banks and insurers holding legacy customer data collected without conforming notice. ASEAN follows a similar pattern as new digital banking licences bring greenfield stacks that specify journey infrastructure from day one.

South America

Country Metric Key Driver
Brazil 62.8% share of region LGPD compliance and fintech onboarding journeys
Argentina USD 0.19 Billion Retail and telecom digitisation
Rest of South America 18.4% CAGR Regional marketplace expansion


Brazil dominates regional spend because LGPD gave the market an early compliance framework and because its fintech sector runs entirely on digital acquisition funnels. Onboarding abandonment is the operative metric — a lender losing applicants between identity verification and first deposit can attribute lost revenue precisely, which makes the business case unusually clean.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.7% share of region Vision 2030 government service experience programmes
UAE USD 0.24 Billion Banking and aviation loyalty personalisation
South Africa 16.8% share of region Retail and telecom analytics adoption
Egypt 21.4% CAGR Mobile money and digital lending growth
Rest of MEA 9.3% share of region Public-sector digitisation


Gulf demand originates from government rather than retail. National transformation programmes measure citizen service satisfaction as a policy outcome, which funds journey instrumentation across ministries and state-owned carriers. Residency requirements are strict, so vendors compete on local cloud region availability as much as on analytical capability.


Customer Journey Analytics Market By Region, 2025-2035

Customer Journey Analytics Market Segmentation

By Component

Segment Metric (2025) Primary Demand Driver
Solutions 51.6% share Platform licence consolidation
Services 21.7% CAGR (2026–2035) Implementation and integration complexity


Solutions retain the majority of spend in the Customer Journey Analytics Market, but the growth story belongs to services. Deployments fail on schema design, identity strategy and non-digital ingestion far more often than on visualisation, and few enterprises hold that capability internally. Systems integrators have responded by building dedicated journey engineering practices, which in turn accelerates licence consumption.

By Deployment Mode

Segment Metric (2025) Primary Demand Driver
Cloud 57.9% share Elastic compute for real-time scoring
On-Premises USD 5.18 Billion Legacy regulated infrastructure
Hybrid 23.6% CAGR (2026–2035) Data residency and sovereignty requirements


Cloud dominance in the Customer Journey Analytics Market reflects a technical necessity rather than a preference — sub-second decisioning cannot run on fixed capacity. Hybrid grows fastest because regulated buyers refuse to choose between latency and residency, and zero-copy federation onto existing warehouses now offers a credible third path [7].

By Application

Segment Metric (2025) Primary Demand Driver
Journey Mapping and Visualization 30.6% share Baseline diagnostic requirement
Campaign and Journey Orchestration 23.9% CAGR (2026–2035) Shift from insight to automated action
Customer Segmentation and Targeting 18.3% share First-party audience activation
Predictive and Behavioural Analytics USD 2.96 Billion Churn and propensity modelling
Voice of Customer and Feedback Analytics 11.2% share Contact-centre quality programmes


Mapping remains the entry workload across the Customer Journey Analytics Market because organisations must see the journey before they can change it. Orchestration is where budget migrates once that baseline exists, and its growth rate reflects the category convergence formalised in 2026 [3]. Buyers increasingly refuse to license the two capabilities separately.

By End-User Enterprise Size

Segment Metric (2025) Primary Demand Driver
Large Enterprises 62.7% share Multi-channel complexity and compliance exposure
Small and Medium Enterprises 24.4% CAGR (2026–2035) Packaged SaaS tiers and lower entry pricing


The market is segmented by end-user enterprise size, with Large Enterprises serving as the dominating segment with a 62.7% share driven by multi-channel complexity and compliance exposure. Meanwhile, Small and Medium Enterprises represent an expanding category growing at 24.4% CAGR, propelled by packaged SaaS tiers and lower entry pricing.

By End-User Industry

Segment Metric (2025) Primary Demand Driver
BFSI 24.2% share Onboarding abandonment and regulatory consent
Retail and eCommerce 26.3% CAGR (2026–2035) Retail media and personalisation economics
Telecom and Media USD 3.06 Billion Churn reduction and bundled service journeys
Healthcare and Life Sciences 12.1% share Patient access and adherence programmes
Travel and Hospitality 9.8% share Loyalty and disruption recovery journeys
IT and Professional Services 8.5% share B2B buying-group analytics
Others 8.4% share Public sector and utilities


Banking leads the Customer Journey Analytics Market with24.2% share on the strength of measurable loss. Application abandonment, fraud friction and call deflection all carry known unit economics, and CSG's disclosed bank outcomes illustrate the scale of recoverable value [4]. Retail grows faster because personalisation directly compounds margin and because retail media networks convert journey data into an external revenue stream [10].


Competitive Benchmarking

Concentration sits in the medium band. The top five vendors hold an estimated 44–52% of revenue, producing an approximate HHI of 640–760 — consolidated enough that suite economics dominate, open enough that specialists still win on depth. Ecosystem integration creates the switching costs that sustain this structure: once identity graphs, consent state and orchestration logic live in one platform, migration cost exceeds licence savings. The inaugural 2026 evaluation covered eight vendors, a narrower field than the vendor count implies, because analytics-only suppliers no longer meet the category definition [3].

Company Est. Revenue Share Range Key Offerings for Customer Journey Analytics Market Strategic Positioning
Adobe ~13–16% Customer Journey Analytics, Real-Time CDP, Journey Optimizer 2026 Leader; analytics plus orchestration in one stack [3][5]
Salesforce ~11–14% Data 360, Agentforce Marketing, Agentforce Agent-grounded data layer across CRM estate [8][9]
Google ~7–10% Google Analytics 4, BigQuery, Google Cloud CDP Warehouse-anchored measurement and activation [1]
Microsoft ~6–9% Dynamics 365 Customer Insights, Fabric Bundled with enterprise data platform commitments
Oracle ~5–8% Unity CDP, CX Cloud Deep vertical CX for regulated industries
SAS Institute ~4–6% Customer Intelligence 360 Statistical rigour for BFSI and telecom
NICE ~4–6% Enlighten, CXone journey capabilities Contact-centre-native journey intelligence
Genesys ~3–5% Genesys Cloud CX journey management Service-led orchestration across voice and digital
CSG Systems International ~2–4% Xponent 2026 Leader; real-time action in telecom and banking [4]
Contentsquare ~2–4% Experience Analytics, Heap product analytics Digital experience plus product analytics convergence [11]
Verint Systems ~2–4% Open CX platform, behavioural analytics Workforce and experience data integration
Quantum Metric ~1–3% Felix AI, session intelligence Engineering-oriented friction detection


Recent News & Developments

Contentsquare (December, 2024)--completed the strategic acquisition of Heap to combine digital analytics and user feedback capabilities into an expanded experience platform.

Contentstack (December 2024)--announced the official acquisition of Lytics to integrate real-time customer data platform capabilities into its composable digital experience architecture.


  • Salesforce(October 2024)--brought Agentforce to general availability, establishing a unified data layer to power autonomous agent workflows across customer relationship management operations.


Customer Journey Analytics Market Report Scope

Parameter Detail
Market Scope Global market for customer journey analytics and orchestration software, platforms and associated professional services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 17.10% (2026–2035)
Market Size Checkpoints USD 19.62 Billion (2025); USD 23.17 Billion (2026); USD 51.01 Billion (2031); USD 95.90 Billion (2035)
Fastest Growing Segments Services (component); Hybrid (deployment); Campaign and Journey Orchestration (application); SMEs (enterprise size); Retail and eCommerce (industry); Asia-Pacific (geography)
Companies Profiled Adobe, Salesforce, Google, Microsoft, Oracle, SAS Institute, NICE, Genesys, CSG Systems International, Contentsquare, Verint Systems, Quantum Metric
Valuation Currency USD Billion

FAQs

How should procurement teams structure a Customer Journey Analytics Market platform contract?
Negotiate consumption floors against measured event volume rather than vendor-projected growth. Insist on price protection for profile and compute overages beyond year one, since consumption billing is where budget variance concentrates [17].
Is a warehouse-native build cheaper than buying a packaged platform?
Rarely below roughly 500 million monthly events, where engineering and maintenance costs exceed licence savings. Above that threshold, zero-copy federation onto Snowflake or Databricks often wins on cost and control. The Customer Journey Analytics Market now supports both patterns [7].
What identity resolution match rate should buyers expect in the Customer Journey Analytics Market?
Deterministic matching on authenticated traffic typically resolves a majority of sessions; probabilistic stitching lifts coverage but introduces false merges. Demand that vendors disclose precision and recall separately during proof of concept [5].
Which internal roles determine deployment success?
A data engineer owning schema governance and a business analyst owning journey definitions. Programmes that fund both reach production materially faster than those treating the platform as a marketing tool alone [12].
How do data residency rules affect Customer Journey Analytics Market deployments?
Regulated buyers in India, the EU and the Gulf increasingly require in-country processing, which pushes architectures toward hybrid. Vendors without local cloud regions lose deals at procurement screening before capability is assessed [14].
What ROI evidence should buyers demand before signing?
Ask for a controlled holdout test, not a published case-study uplift figure. Vendor-commissioned economic impact studies overstate benefit when baseline personalisation maturity is ignored [6].
Can these platforms analyse contact-centre and in-store interactions?
Yes, provided event schemas accept non-digital records with reliable timestamps and identifiers. Voice transcripts and branch visits remain the most common gaps in first-generation deployments [4].    
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















