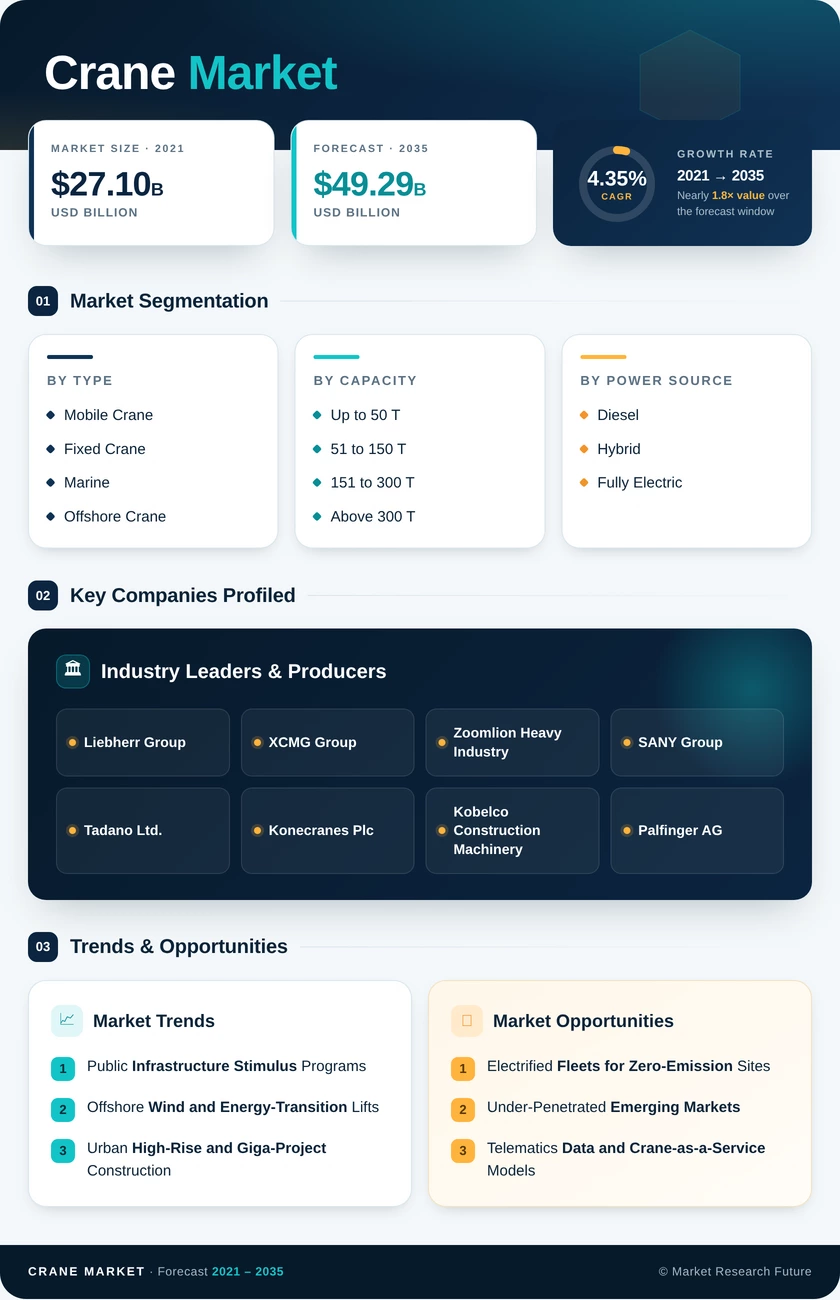
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Type | Mobile Crane; Fixed Crane; Marine and Offshore Crane | Mobile Crane (47.6% share) | Marine and Offshore Crane (6.6% CAGR) |
| By Capacity | Up to 50 T; 51 to 150 T; 151 to 300 T; Above 300 T | 51 to 150 T (31.4% share) | Above 300 T (7.2% CAGR) |
| By Power Source | Diesel; Hybrid; Fully Electric | Diesel (74.3% share) | Fully Electric (12.9% CAGR) |
| By Boom Type | Lattice Boom; Telescopic Boom | Telescopic Boom (58.5% share) | Lattice Boom (6.1% CAGR) |
| By Application | Construction and Mining; Energy and Utilities; Shipbuilding and Ports; Industrial Manufacturing; Logistics and Warehousing | Construction and Mining (41.7% share) | Energy and Utilities (5.9% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East and Africa | Asia-Pacific (42.6% share) | Middle East and Africa (5.6% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Mobile Crane | Rental fleets favor all-terrain and truck-mounted units for multi-site flexibility |
| Fixed Crane | Tower and overhead systems tied to high-rise and factory investment |
| Marine and Offshore Crane | Larger vessel cranes needed for next-generation offshore turbines |
Mobile Crane leads with a 47.6% share because all-terrain and truck-mounted models let contractors redeploy one machine across several jobs in a week. Marine and Offshore Crane grows fastest at a 6.6% CAGR, since offshore turbine components now exceed the lifting limits of many existing installation vessels. Fixed Crane demand tracks high-rise construction in the Gulf and Asia alongside overhead systems in manufacturing plants.
| Sub-Segment | Key Trend |
|---|
| Up to 50 T | Utilities and maintenance crews prioritize compact, road-legal units |
| 51 to 150 T | Core range for commercial and industrial construction |
| 151 to 300 T | Bridge and infrastructure module placement |
| Above 300 T | Modular nuclear, refinery, and wind lifts push capacity upward |
The 51 to 150 T class leads with a 31.4% share because it covers most commercial building and plant work while remaining transportable on public roads. Above 300 T grows fastest at a 7.2% CAGR as modular reactor, refinery, and turbine components grow heavier. The 151 to 300 T range sits between these, serving bridge girders and industrial modules.
| Sub-Segment | Key Trend |
|---|
| Diesel | Stage V and Tier 4 Final engines extend combustion relevance |
| Hybrid | Transitional option reducing fuel use and idle emissions |
| Fully Electric | Zero-emission site mandates and port rules drive adoption |
Diesel holds a 74.3% share because remote sites lack charging capacity and service networks remain built around combustion engines. Fully Electric grows fastest at a 12.9% CAGR, pulled by California port rules and European zero-emission site requirements. Hybrid systems give fleet owners a lower-risk step toward electrification while retaining full-day range.
| Sub-Segment | Key Trend |
|---|
| Lattice Boom | Preferred for heavy-lift wind, nuclear, and petrochemical work |
| Telescopic Boom | Rapid setup suits rental and general construction fleets |
Telescopic Boom leads with a 58.5% share because it deploys in minutes on mobile carriers, matching rental and general contracting workflows. Lattice Boom grows faster at a 6.1% CAGR, as wind erection and modular plant lifts demand capacity and stability at extreme heights. OEMs are narrowing the gap with telescoping crawler designs that combine elements of both.
| Sub-Segment | Key Trend |
|---|
| Construction and Mining | Infrastructure stimulus and mine expansions sustain fleet use |
| Energy and Utilities | Renewables, grid upgrades, and nuclear multiply heavy lifts |
| Shipbuilding and Ports | Terminal expansion and electrified harbor equipment |
| Industrial Manufacturing | Overhead systems support automated production lines |
| Logistics and Warehousing | Intermodal hubs and distribution centers add lifting demand |
Construction and Mining leads with a 41.7% share, supported by US and Indian infrastructure programs and steady mine development. Energy and Utilities grows fastest at a 5.9% CAGR, as wind, transmission, and nuclear projects require frequent heavy lifts. Shipbuilding and Ports and Logistics and Warehousing gain from trade growth and terminal electrification.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA