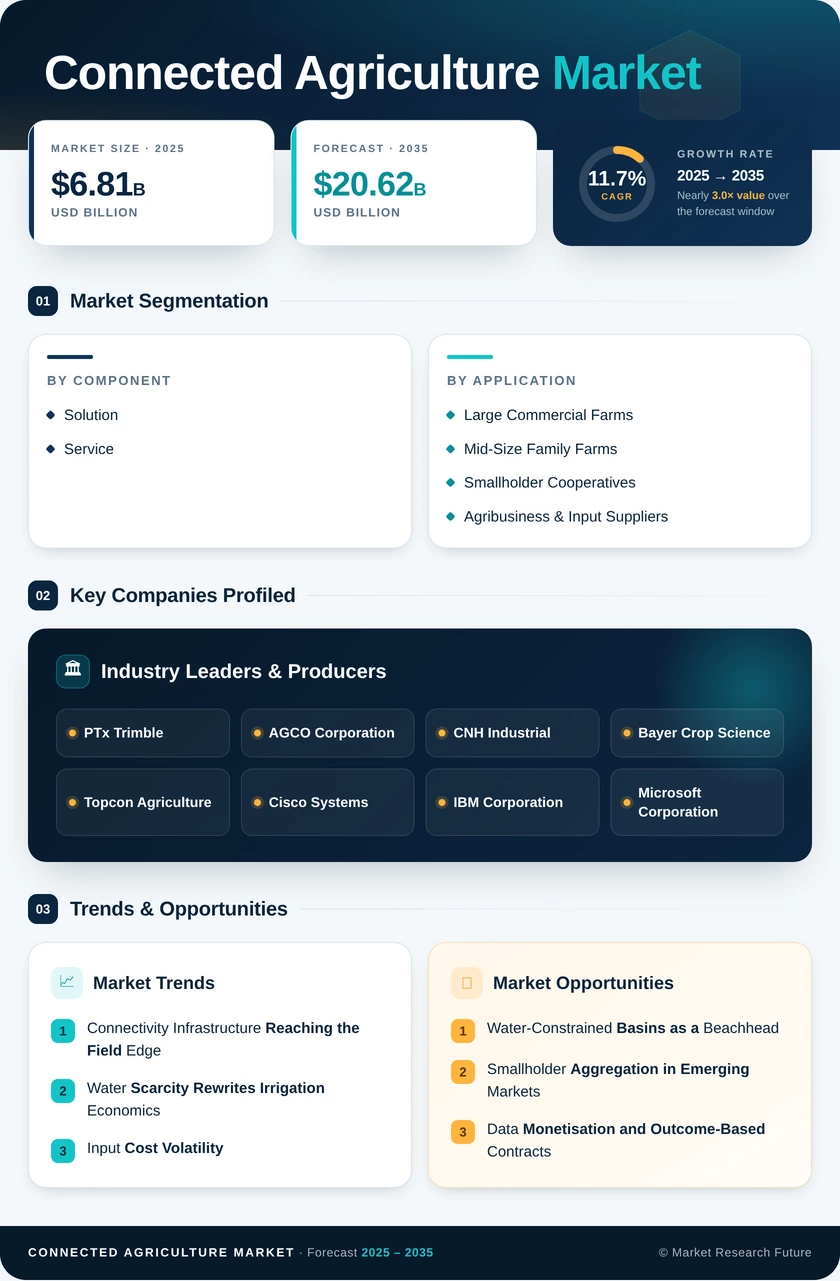
Connected Agriculture Market (2026 - 2035)

ID: MRFR/ICT/3780-HCR 200 Pages Aarti Dhapte Last Updated: September 15, 2026
Connected Agriculture Market Size, Share and Research Report By Interoperability and Data Standards, By Capital Intensity Against Farm Margins, By Data Ownership and Privacy Uncertainty and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
Connected Agriculture Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.7%
2025 Market SizeUSD 6.81 Billion
2035 Market SizeUSD 20.62 Billion
Key Players
PTx Trimble
AGCO Corporation
CNH Industrial
Bayer Crop Science
Topcon Agriculture
Cisco Systems
Opportunities
  • Water-Constrained Basins as a Beachhead
  • Smallholder Aggregation in Emerging Markets
  • Data Monetisation and Outcome-Based Contracts
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Report Takeaways |
    1. 2.1 Key Takeaways by Component |
    2. 2.2 Key Takeaways by Application |
    3. 2.3 Key Takeaways by Geography
  3. 3 Global Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Market Dynamics — Drivers |
    1. 4.1 Connectivity Infrastructure Reaching the Field Edge |
    2. 4.2 Water Scarcity and Irrigation Economics |
    3. 4.3 Input Cost Volatility |
    4. 4.4 Public Digitisation Programmes
  5. 5 Market Dynamics — Restraints |
    1. 5.1 Interoperability and Data Standards |
    2. 5.2 Capital Intensity Against Farm Margins |
    3. 5.3 Data Ownership and Privacy Uncertainty
  6. 6 Market Opportunity Analysis |
    1. 6.1 Water-Constrained Basins |
    2. 6.2 Smallholder Aggregation in Emerging Markets |
    3. 6.3 Data Monetisation and Outcome-Based Contracts |
    4. 6.4 Protein Traceability |
    5. 6.5 Autonomy-Ready Fleet Retrofits |
    6. 6.6 Industry Value Chain Analysis |
    7. 6.7 Porter's Five Forces Analysis
  7. 7 Regional Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of MEA
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Autonomy Adoption Pathway |
    2. 8.2 Platform Economics and Service Migration |
    3. 8.3 Climate Reporting and Supply Chain Conditionality |
    4. 8.4 Connectivity Commoditisation
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Component | |
      1. 9.1.1 Solution | |
      2. 9.1.2 Service |
    2. 9.2 By Application | |
      1. 9.2.1 Smart Logistics | |
      2. 9.2.2 Smart Irrigation | |
      3. 9.2.3 Farming Planning and Management |
    3. 9.3 By End User | |
      1. 9.3.1 Large Commercial Farms | |
      2. 9.3.2 Mid-Size Family Farms | |
      3. 9.3.3 Smallholder Cooperatives | |
      4. 9.3.4 Agribusiness & Input Suppliers
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Deere & Company | |
      2. 10.3.2 PTx Trimble | |
      3. 10.3.3 AGCO Corporation | |
      4. 10.3.4 CNH Industrial | |
      5. 10.3.5 Bayer Crop Science | |
      6. 10.3.6 Topcon Agriculture | |
      7. 10.3.7 Cisco Systems | |
      8. 10.3.8 IBM Corporation | |
      9. 10.3.9 Microsoft Corporation | |
      10. 10.3.10 SAP SE | |
      11. 10.3.11 Vodafone Group | |
      12. 10.3.12 Yara International
  11. 11 Recent News & Developments (2023–2025)
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Valuation Currency & Conventions |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Connected Agriculture Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Connected Agriculture Market — Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Connected Agriculture Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Connected Agriculture Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Connected Agriculture Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Connected Agriculture Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Connected Agriculture Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Connected Agriculture Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Connected Agriculture Market Size, by Component, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Connected Agriculture Market Size, by Application, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Connected Agriculture Market Size, by End User, 2021–2035 (USD Billion) |
  29. TABLE 14 North America Connected Agriculture Market Size, by Component, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Connected Agriculture Market Size, by Application, 2021–2035 (USD Billion) |
  31. TABLE 16 Europe Connected Agriculture Market Size, by Component, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Connected Agriculture Market Size, by Application, 2021–2035 (USD Billion) |
  33. TABLE 18 Asia-Pacific Connected Agriculture Market Size, by Component, 2021–2035 (USD Billion) |
  34. TABLE 19 Asia-Pacific Connected Agriculture Market Size, by Application, 2021–2035 (USD Billion) |
  35. TABLE 20 South America Connected Agriculture Market Size, by Component, 2021–2035 (USD Billion) |
  36. TABLE 21 Middle East & Africa Connected Agriculture Market Size, by Component, 2021–2035 (USD Billion) |
  37. TABLE 22 Competitive Benchmarking Matrix — Global Connected Agriculture Market, 2026 |
  38. TABLE 23 Company Profiles — Key Players, Global Connected Agriculture Market |
  39. TABLE 24 Recent Developments & Strategic Announcements, 2023–2025 |
  40. TABLE 25 Report Scope & Methodology Summary |
  41. TABLE 26 Detailed Sources & Citations Index
  42. 16 LIST OF FIGURES |
  43. FIGURE 1 Global Connected Agriculture Market Dynamics — Drivers, Restraints & Opportunities |
  44. FIGURE 2 Industry Value Chain Analysis |
  45. FIGURE 3 Porter's Five Forces Analysis |
  46. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) |
  47. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) |
  48. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) |
  49. FIGURE 7 Market Share by Application, 2025 vs 2035 (%) |
  50. FIGURE 8 Market Share by End User, 2025 (%) |
  51. FIGURE 9 Regional Market Share Distribution, 2025 (%) |
  52. FIGURE 10 Regional CAGR Comparison, 2026–2035 (%) |
  53. FIGURE 11 North America Country-Level Share Breakdown, 2025 (%) |
  54. FIGURE 12 Asia-Pacific Country-Level Growth Comparison, 2026–2035 (%) |
  55. FIGURE 13 Competitive Landscape — Estimated Revenue Share Ranges, 2026 |
  56. FIGURE 14 Competitive Positioning Matrix — Capability vs Geographic Reach |
  57. FIGURE 15 Technology Adoption S-Curve by Farm Size Cohort, 2021–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentSolution, ServiceSolutionService
By ApplicationSmart Logistics, Smart Irrigation, Farming Planning and ManagementFarming Planning and ManagementSmart Irrigation
By End UserLarge Commercial Farms, Mid-Size Family Farms, Smallholder Cooperatives, Agribusiness & Input SuppliersLarge Commercial FarmsMid-Size Family Farms
By GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
SolutionConsolidation of point tools into unified farm operating platforms with open API layers
ServiceGrowth of managed agronomy, integration consulting and connectivity-as-a-service contracts


Component economics are inverting. Hardware and licence margin compresses as sensing components commoditise, while recurring service revenue carries higher retention and better lifetime value. Vendors that fail to build service delivery capability will find themselves selling depreciating hardware into a price-competitive field.

By Application

Sub-SegmentKey Trend
Smart LogisticsCold-chain telemetry and geo-referenced consignment tracking driven by export compliance
Smart IrrigationCloud-linked controllers and soil-moisture networks tied to abstraction licensing regimes
Farming Planning and ManagementSeason-long agronomic decision support integrated with subsidy and sustainability reporting


Application demand splits along regulatory lines. Where water is metered, irrigation leads; where subsidies are conditional, planning and management leads; where exports face traceability audits, logistics leads. Vendors selling a single application into a mismatched regulatory environment consistently underperform.

By End User

Sub-SegmentKey Trend
Large Commercial FarmsIn-house agronomy teams demanding raw data access and custom model integration
Mid-Size Family FarmsDealer-bundled financing converting capex barriers into per-season operating cost.
Smallholder CooperativesAggregated licensing and mobile-first advisory reaching fragmented landholdings
Agribusiness & Input SuppliersPlatform ownership as a customer retention and demand-forecasting mechanism


End-user segmentation determines channel strategy more than product strategy. Large farms buy direct and negotiate hard on data rights. Mid-size operations buy through equipment dealers. Smallholders reach the market only through cooperatives, input dealers or mobile operators, which makes partnership depth the decisive competitive variable in emerging geographies.

By Geography

Sub-SegmentKey Trend
North AmericaScale economics plus LEO satellite connectivity extending coverage to remote acreage
EuropeSubsidy conditionality and nutrient regulation forcing documented practice records
Asia-PacificState-funded digital public infrastructure lowering vendor customer acquisition cost
South AmericaDeforestation-free sourcing requirements driving geo-referenced plot compliance
Middle East & AfricaBifurcated demand between Gulf capital-intensive systems and donor-funded smallholder services


Geographic strategy in this market is really regulatory strategy. Each region's adoption curve is shaped less by farm technology readiness than by the specific compliance obligation that makes digital record-keeping unavoidable.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.