Connected Agriculture Market (2026 - 2035)

Connected Agriculture Market Size, Share and Research Report By Interoperability and Data Standards, By Capital Intensity Against Farm Margins, By Data Ownership and Privacy Uncertainty and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
ID: MRFR/ICT/3780-HCR 200 Pages Aarti Dhapte Last Updated: September 10, 2026
Connected Agriculture Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.7%
2025 Market SizeUSD 6.81 Billion
2035 Market SizeUSD 20.62 Billion
Key Players
PTx Trimble
AGCO Corporation
CNH Industrial
Bayer Crop Science
Topcon Agriculture
Cisco Systems
Opportunities
  • Water-Constrained Basins as a Beachhead
  • Smallholder Aggregation in Emerging Markets
  • Data Monetisation and Outcome-Based Contracts

Connected Agriculture Market Summary

The Connected Agriculture Market was valued at USD 6.81 billion in 2025 and opens the forecast window at USD 7.61 billion in 2026, climbing to USD 20.62 billion by 2035 at a 11.7% CAGR. Two catalysts anchor that trajectory. The United States Department of Agriculture's ReConnect Program has obligated billions in rural broadband loans and grants since 2019, closing the coverage gap that once made farm telemetry impractical [1]. India's Digital Agriculture Mission, cleared by the Union Cabinet in September 2024 with an outlay of roughly INR 2,817 crore, pushes a national farmer registry and digital crop survey into 400,000-plus villages [2].

The old way of doing things is quickly disappearing. Telematics-equipped gear, variable-rate controllers, and cloud agronomy platforms are replacing paper agronomy logs, manual gate valves and calendar-based spraying. Agriculture must increase output by almost 50% by 2050 versus stagnant arable land, a gap only data can fill, according to the Food and Agriculture Organization [3]. This pressure helps to ensure that money continues to flow to the Connected Agriculture Market even in sluggish commodity cycles.


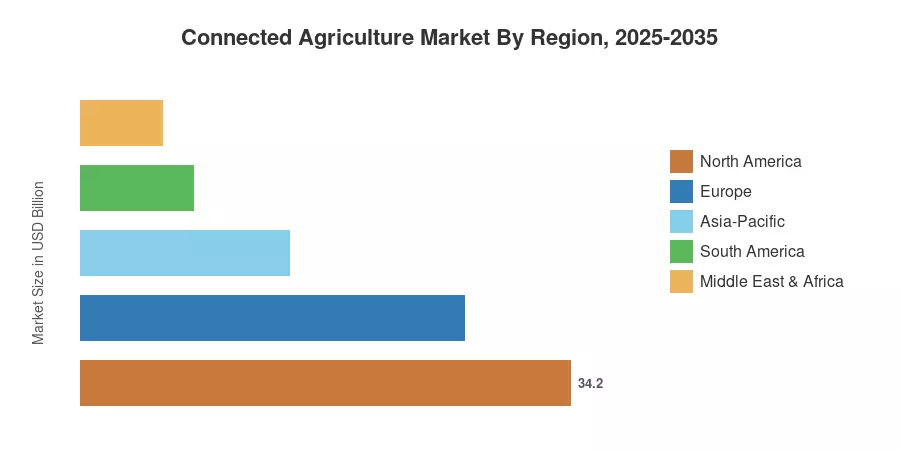
North America accounts for 34.2 percent of 2025 revenue from large-acreage row-crop economics. The Asia-Pacific region is the fastest growing at 14.6%, with state-driven digitization in China and India. Europe follows with 26.8%, where subsidy payments under Common Agricultural Policy conditionality need to be linked to verified practice data [4]. Through 2035, the Connected Agriculture market is shifting from selling hardware to selling recurring data services.


Key Report Takeaways

• By Component

  • Solutions command 62.4% of 2025 revenue as farm management software and sensor platforms bundle into single subscriptions within the Connected Agriculture Market.
  • Services expand at a 12.9% CAGR through 2035 as agronomy-as-a-service and managed connectivity displace one-time installation work.

• By Application

  • Farming Planning and Management contributes USD 2.85 billion in 2025, the largest application block in the Connected Agriculture Market.
  • Smart Irrigation grows at 13.4% CAGR as water-scarce basins price abstraction more aggressively.
  • Smart Logistics holds 24.7% share, lifted by cold-chain traceability mandates.

• By Geography

  • North America leads with 34.2% share of the Connected Agriculture Market in 2025
  • Asia-Pacific posts the fastest regional CAGR at 14.6%
  • Middle East & Africa reaches USD 1.24 billion by 2035 on desert-agriculture investment


Market Size and Forecast (2021–2035)

Figures below are a combination of a bottom-up build based on installed connected-acre counts and spend per acre, reconciled against a top-down review of vendor agriculture-segment revenue declarations, national agri-tech subsidy budgets and cellular IoT connection registries. Historical years are calibrated to audited company filings. Forecast years are based on adoption-curve modeling per farm size cohort.
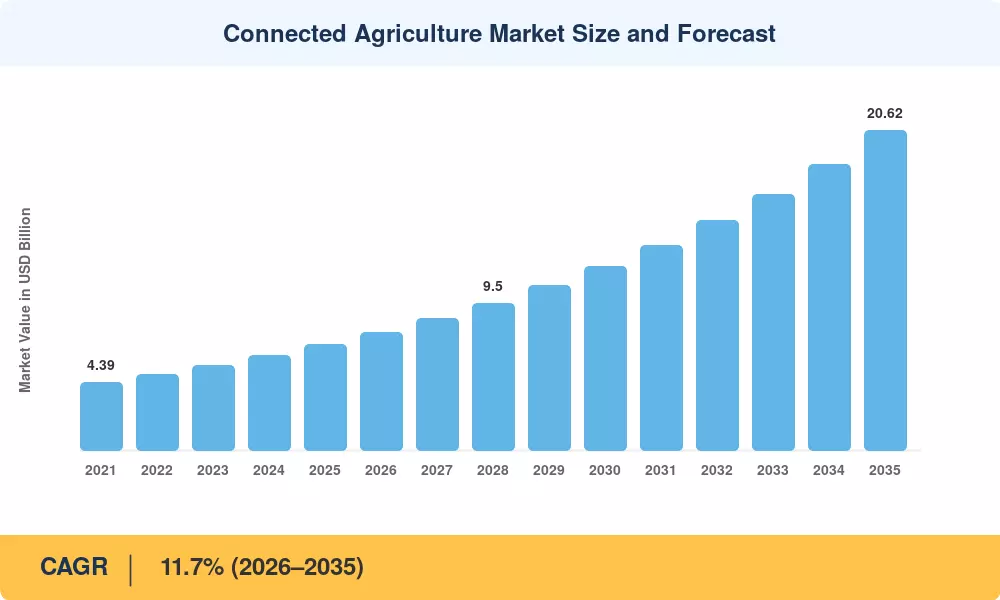
Connected Agriculture Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rural broadband and cellular coverage expansion 22 North America, Europe, India Short-term (≤2 yr)
Water scarcity and abstraction pricing 19 MEA, Australia, US West, India Medium-term (2–4 yr)
Input-cost inflation driving variable-rate adoption 17 Global Short-term (≤2 yr)
Government digital-agriculture subsidy programmes 15 Asia-Pacific, Europe Medium-term (2–4 yr)
Traceability and food-safety compliance 11 Europe, North America Medium-term (2–4 yr)
Agricultural labour shortages 9 Japan, Europe, North America Long-term (≥4 yr)
Carbon and sustainability outcome markets 7 Global Long-term (≥4 yr)


Connectivity Infrastructure Reaching the Field Edge

Coverage was the binding constraint for a decade. The Federal Communications Commission's Task Force for Reviewing the Connectivity and Technology Needs of Precision Agriculture documented that a meaningful share of United States cropland lacked the reliable broadband needed for real-time machine data [14]. USDA's ReConnect Program has since committed billions across successive funding rounds to close that gap [1]. The economics changed sharply once low-earth-orbit capacity entered the picture, extending satellite-connected agriculture for remote farms into territory terrestrial networks were never going to reach profitably. For the Connected Agriculture Market, coverage expansion converts previously unaddressable acreage into billable subscriptions.

Water Scarcity Rewrites Irrigation Economics

Agriculture accounts for roughly 70% of global freshwater withdrawals, according to the Food and Agriculture Organization [9]. Where regulators meter and price abstraction, payback on soil-moisture probes and controller retrofits compresses to two seasons or less. California's Sustainable Groundwater Management Act pushes basins toward measured sustainable yield, and Gulf states subsidise closed-loop systems outright. Growth in the Connected Agriculture Market tracks these regulatory clocks closely.

Input Cost Volatility

Fertiliser prices spiked severely through 2022, and OECD-FAO analysis continues to flag elevated input-to-output price ratios [6]. Variable-rate application typically trims nitrogen use by a measurable margin without yield penalty. That saving alone funds most platform subscriptions, which is why adoption held through the 2024 commodity downturn.

Public Digitisation Programmes

China's Ministry of Agriculture and Rural Affairs has run successive digital-village and smart-agriculture pilot programmes. At the same time, India's Agristack framework builds farmer, land-parcel and crop-sown registries as public digital infrastructure [2]. Subsidised onboarding lowers customer acquisition cost dramatically for vendors operating in the Connected Agriculture Market.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Fragmented data standards and vendor lock-in 24 Global Medium-term (2–4 yr)
High upfront capex versus thin farm margins 21 South America, Africa, South Asia Short-term (≤2 yr)
Data ownership and privacy uncertainty 18 Europe, North America Medium-term (2–4 yr)
Digital skills gap among operators 16 Global Long-term (≥4 yr)
Persistent connectivity dead zones 13 Africa, Rest of Asia-Pacific Medium-term (2–4 yr)


Interoperability Remains Unsolved

A grower running one brand of tractor, another brand of irrigation controller, and a third agronomy platform still burns hours reconciling files. AgGateway and ISOBUS working groups have advanced common data exchange, yet adoption is uneven and proprietary telemetry formats persist [10]. Buyers hesitate when switching costs look permanent, and that hesitation is the single largest brake on the Connected Agriculture Market.

Capital Intensity Against Compressed Margins

USDA Economic Research Service projections showed net farm income declining materially from its 2022 peak [7]. When margins compress, sensor networks and controller retrofits move down the capex queue behind seed, chemistry and debt service. Financing structures that convert capex into per-acre operating cost are the practical workaround, and vendors that lack them lose deals in the Connected Agriculture Market.

Who Owns the Agronomic Record

Growers increasingly ask where field data goes and whether it can surface in land valuation, insurance pricing or input marketing. The European Union's code of conduct on agricultural data sharing was drafted precisely because contractual clarity lagged practice [15]. Unresolved ownership questions slow enterprise-scale rollouts.


Connected Agriculture Market Opportunities

Water-Constrained Basins as a Beachhead

Regions pricing water aggressively offer the cleanest ROI story available. Retrofit programmes targeting existing pivot and drip infrastructure convert quickly because the hardware base already exists.

Smallholder Aggregation in Emerging Markets

Africa and South Asia hold hundreds of millions of sub-two-hectare holdings that cannot individually fund a platform licence. Cooperative and input-dealer aggregation models spread cost across thousands of members, and GSMA has tracked the scale-up of mobile-enabled agricultural services across these geographies [16]. This is the largest unaddressed volume pool in the Connected Agriculture Market.

Data Monetisation and Outcome-Based Contracts

Anonymised, geo-referenced agronomic records carry direct value to crop insurers, lenders, commodity traders and carbon registries. Vendors are shifting from licence fees toward revenue-share arrangements on verified outcomes, which reprices the relationship entirely.

Protein Traceability

Farm-to-fork traceability requirements in export markets create demand for auditable animal-level records. Connected livestock monitoring systems generate exactly the provenance trail that premium meat and dairy buyers now specify in contracts [11].

Autonomy-Ready Fleet Retrofits

Full autonomy remains years from broad deployment, but the connectivity and positioning layer it requires can be sold today on existing machinery. That retrofit path de-risks the purchase and seeds the Connected Agriculture Market for the autonomy upgrade cycle.


Connected Agriculture Market Future Outlook

Autonomy Arrives Incrementally

Full driverless field operations will remain a minority of acres through 2030, constrained by liability frameworks more than by technology. What scales first is supervised autonomy — an operator managing several machines from a cab or an office. Each autonomous pass generates far denser telemetry than a manned one, expanding data volumes across the Connected Agriculture Market by an order of magnitude.

Platform Economics Overtake Hardware Margin

Sensor and controller hardware is commoditising as component costs fall. Value migrates to the agronomic recommendation layer and to the integrations that push those recommendations into machinery, procurement and finance systems. Expect service revenue to approach parity with solution revenue by the mid-2030s.

Climate Reporting Becomes Contractual

Scope 3 emissions disclosure pressure is moving from voluntary to contractual in food supply chains. The International Energy Agency and allied bodies have documented the reporting infrastructure gap in land-based sectors, and field-level activity data is the only credible input [19]. Buyers will increasingly specify data provision as a supply condition.

Connectivity Ceases to Be a Differentiator

By the early 2030s, ubiquitous coverage combining terrestrial 5G, LPWAN and LEO satellite will make connectivity a commodity input. Competition in the Connected Agriculture Market will then turn entirely on model accuracy, agronomic credibility and integration depth.


Connected Agriculture Market Segmentation

By Component

Segment Metric (2025) Primary Demand Driver
Solution 62.4% share Bundled farm management software and sensor platforms
Service 12.9% CAGR (2026–2035) Managed agronomy, integration and connectivity contracts


Solutions dominate today because buyers still purchase capability as a product — a platform licence, a controller, a guidance receiver. That framing is eroding. Growers increasingly want the outcome rather than the tool, and services grow faster as a result. The Connected Agriculture Market is following the same trajectory enterprise software took a decade earlier, where implementation and managed operations eventually rivalled licence revenue.

By Application

Segment Metric (2025) Primary Demand Driver
Farming Planning and Management USD 2.85 billion Agronomic decision support and compliance recording
Smart Irrigation 13.4% CAGR (2026–2035) Water pricing, abstraction limits, drought frequency
Smart Logistics 24.7% share Cold-chain integrity and export traceability


Farming Planning and Management leads because it is where the recurring relationship lives — seasonal planning, in-season scouting, harvest reconciliation and regulatory reporting all run through the same platform. Smart Irrigation grows fastest for a blunter reason: water is becoming a metered, priced and legally constrained input across an expanding share of global cropland, and manual scheduling cannot demonstrate compliance. Smart Logistics holds a steady quarter of the Connected Agriculture Market, anchored by perishable export flows where a single temperature excursion destroys consignment value.

By End User

Segment Metric (2025) Primary Demand Driver
Large Commercial Farms 44.6% share Scale economics and dedicated agronomy staff
Mid-Size Family Farms 12.2% CAGR (2026–2035) Dealer-financed retrofit packages
Smallholder Cooperatives USD 1.04 billion Aggregated licensing and donor-funded programmes
Agribusiness & Input Suppliers 11.9% share Customer advisory services and demand forecasting


Large commercial operations remain the revenue core of the Connected Agriculture Market. Still, the incremental growth story sits with mid-size family farms, where equipment dealers now bundle connectivity into machinery financing and remove the upfront decision entirely.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 34.2% share Row-crop telematics, groundwater compliance, LEO connectivity
Europe 26.8% share CAP conditionality, nutrient-runoff limits, traceability
Asia-Pacific 14.6% CAGR (2026–2035) State digitisation, smallholder aggregation, rice-water management
South America 7.9% share Soy and sugarcane logistics, deforestation-free sourcing
Middle East & Africa 5.7% share Desert agriculture, food-security sovereignty programmes
Total 100.0%


North America

Country Metric Key Driver
US 71.4% of region Large-acreage row crop economics and ReConnect funding [1]
Canada 12.6% CAGR Prairie grain telematics and variable-rate nitrogen
Mexico USD 0.29 billion (2025) Export horticulture traceability requirements


Scale is what makes North America work. A single Midwest operation running several thousand acres amortises a platform subscription across enough hectares that per-acre cost disappears into rounding. Groundwater regulation adds a compliance layer on top: California's Sustainable Groundwater Management Act forces basin-level reporting that manual records cannot satisfy [9]. Combined with federal broadband capital, these conditions keep North America the anchor of the Connected Agriculture Market.

Europe

Country Metric Key Driver
Germany 21.3% of region Nutrient-application recording obligations
UK 16.4% of region Environmental Land Management scheme evidence requirements
France USD 0.31 billion (2025) Viticulture and cereal precision spraying
Italy 11.7% CAGR Irrigation efficiency in the Po basin
Spain 12.4% CAGR Olive and citrus deficit irrigation
Nordic Countries 8.2% of region Dairy herd analytics
Russia USD 0.11 billion (2025) Grain export logistics tracking
Rest of Europe 9.6% of region Cross-border cooperative platforms


Europe's growth is compliance-led rather than yield-led. Common Agricultural Policy strategic plans for 2023–2027 tie direct payments to verifiable environmental conditions, and the Farm to Fork strategy sets nutrient and pesticide reduction targets that require documented application records [4]. Growers adopt digital tools to keep subsidy eligibility intact, which produces steadier but less explosive uptake than Asia-Pacific.

Asia-Pacific

Country Metric Key Driver
China 33.8% of region State smart-agriculture demonstration zones [17]
India 17.9% CAGR Agristack registries and drone subsidy schemes [2]
Japan USD 0.24 billion (2025) Acute farm labour shortage and ageing operators [12]
South Korea 9.1% of region Smart greenhouse and vertical farming build-out
ASEAN 13.8% CAGR Palm, rubber and rice plantation digitisation
Rest of Asia-Pacific 7.4% of region Australian broadacre and water-trading systems


Session Source: Market Research Future (MRFR) Analysis

Asia-Pacific compounds fastest because public money underwrites the onboarding cost. China's rural revitalisation programmes fund demonstration zones that de-risk vendor entry, while India's national farmer registry creates a shared identity layer that private platforms can build on without reacquiring each user [2][17]. Japan's driver is different and starker: the average farmer is well past retirement age, making automation a continuity requirement rather than an efficiency choice [12].

South America

Country Metric Key Driver
Brazil 62.7% of region Soy and sugarcane fleet telematics, ABC+ low-carbon plan [13]
Argentina USD 0.11 billion (2025) No-till precision seeding on Pampas grain
Rest of South America 12.9% CAGR Andean horticulture export traceability


Brazil's advantage is farm scale rivalling anything in North America, paired with a genuine commercial imperative: European buyers now require deforestation-free supply chain evidence under the EU Deforestation Regulation, and geo-referenced plot data is the accepted proof [18]. Logistics telemetry matters disproportionately here because harvest-to-port distances are long and infrastructure constrained.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 24.6% of region Vision 2030 food-security and closed-loop irrigation
UAE 15.9% CAGR Controlled-environment agriculture investment
South Africa 19.3% of region Commercial fruit and wine export compliance
Egypt USD 0.06 billion (2025) Nile delta water-allocation efficiency
Rest of MEA 14.7% CAGR Donor-funded smallholder digital services [16]


Two distinct economies operate side by side here. Gulf states deploy capital-intensive controlled-environment systems where water is the binding constraint and cost is secondary to sovereignty. Sub-Saharan Africa runs the opposite model — low-cost mobile advisory and aggregation services reaching millions of smallholders, often with donor or mobile-operator subsidy [16]. Both expand the Connected Agriculture Market, but through entirely different unit economics.


Connected Agriculture Market By Region, 2025-2035

Competitive Benchmarking

Concentration is important, but it is not the only thing. The top five are projected to control roughly a 40–42% share and have a Herfindahl-Hirschman Index of some 760, a somewhat concentrated structure with incumbents in the machinery space owning the hardware and telematics layer and software, cloud and connection specialists fighting for the analytics layer above. Fragmentation is most pronounced in regional agronomy software, with hundreds of tiny providers focused on specific crops and regions. The ranges below for share are approximations and do not add up exactly.

Company Est. Revenue Share Range Key Offerings for Connected Agriculture Market Strategic Positioning
Deere & Company ~9–12% JDLink telematics, Operations Center, See & Spray Machinery-anchored ecosystem with direct satellite connectivity
PTx Trimble ~6–9% GNSS guidance, displays, mixed-fleet correction services Brand-agnostic positioning and precision hardware depth
AGCO Corporation ~5–8% Fuse smart farming, PTx retrofit portfolio Retrofit-first strategy targeting mixed equipment fleets
CNH Industrial ~4–7% AFS Connect, Raven autonomy, Hemisphere GNSS Vertical integration of positioning and autonomy assets
Bayer Crop Science ~4–6% Climate FieldView agronomy platform Input-linked agronomy with seed and chemistry pull-through
Topcon Agriculture ~3–5% Machine control, sensing, workflow software Precision-component supplier to multiple OEMs
Cisco Systems ~3–5% Industrial IoT gateways, rural network infrastructure Connectivity backbone and edge compute layer
IBM Corporation ~2–4% Environmental Intelligence Suite, weather analytics Data and forecasting services sold to agribusiness
Microsoft Corporation ~2–4% Azure Data Manager for Agriculture Cloud substrate enabling third-party agri-platforms
SAP SE ~2–4% Rural sourcing and agricultural contract management Enterprise back-office integration for agribusiness
Vodafone Group ~1–3% Agricultural IoT connectivity and managed SIM estates Carrier-side connectivity aggregation
Yara International ~1–3% Atfarm nitrogen management, digital agronomy tools Nutrient-optimisation specialist tied to fertiliser sales


Recent News & Developments

  • Deere & Company (January 2024): Announced a satellite communications collaboration to deliver connectivity to machinery operating outside cellular coverage, materially expanding the addressable acreage for real-time telemetry [8].
  • AGCO and Trimble (April 2024): Closed the joint venture forming PTx Trimble, with AGCO holding the majority stake — the largest structural consolidation in precision agriculture technology in recent years, reshaping share dynamics across the Connected Agriculture Market [20].
  • Government of India (September 2024): Union Cabinet approved the Digital Agriculture Mission with an outlay of approximately INR 2,817 crore to build farmer, land and crop registries as national digital public infrastructure [2].
  • Deere & Company (October 2024): Acquired aerial imagery and sensing firm Sentera, strengthening in-house capability across the plant-sensing stack [21].
  • CNH Industrial (2023): Completed acquisition of Hemisphere GNSS, bringing satellite positioning technology in-house and reducing dependence on third-party correction services [22].
  • European Commission (2023–2024): Common Agricultural Policy strategic plans for 2023–2027 entered force across member states, tying direct payments to conditionality requirements that increase demand for verifiable field-level records [4].
  • USDA (2024–2025): Successive ReConnect Program funding rounds continued obligating rural broadband loans and grants, extending service to farms and agricultural businesses in previously unserved areas [1].
  • European Union (2024–2025): Implementation timelines for the EU Deforestation Regulation drove geolocation data requirements into soy, palm, cocoa and cattle supply chains, creating compliance-led demand across South American producers [18].


Connected Agriculture Market Report Scope

Parameter Detail
Market Scope Global connected agriculture solutions and services across crop and livestock production, covering hardware-enabled sensing, connectivity, platform software and managed services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 11.7% (2026–2035)
Market Size Checkpoints USD 6.81 billion (2025); USD 7.61 billion (2026); USD 11.85 billion (2030); USD 20.62 billion (2035)
Fastest Growing Segments Service (Component); Smart Irrigation (Application); Mid-Size Family Farms (End User); Asia-Pacific (Geography)
Companies Profiled 12 major players including Deere & Company, PTx Trimble, AGCO, CNH Industrial, Bayer Crop Science, Topcon, Cisco, IBM, Microsoft, SAP, Vodafone, Yara
Valuation Currency USD Billion, constant 2025 prices

FAQs

What contract structures should procurement teams prioritise when buying into the Connected Agriculture Market?
Per-acre subscription pricing with annual exit rights beats perpetual licences for most buyers. Insist on data portability clauses and defined API access before signing, since extraction rights are far harder to negotiate after deployment [15].
How should a buyer compare LPWAN against cellular for field sensor deployment?
LPWAN suits low-bandwidth, battery-critical sensing across wide areas at minimal recurring cost. Cellular fits bandwidth-heavy applications like imagery upload and machine telemetry. Most mature farms run both, segmented by data volume [23].
What integration failures most commonly derail Connected Agriculture Market deployments?
Boundary file mismatches between platforms cause the majority of failed rollouts, followed by inconsistent product naming across input inventories. Resolving field geometry and naming conventions before go-live prevents most of it [10].
Do agri-tech investments qualify for green finance instruments?
Several sustainability-linked loan frameworks now recognise measurable input-efficiency gains as qualifying use of proceeds. Brazilian low-carbon agriculture credit lines are the clearest example, offering concessional rates against verified practice adoption [13].
How do buyers evaluate vendor agronomic model accuracy in the Connected Agriculture Market?
Request back-tested performance against the buyer's own historical yield maps, not vendor case studies. Two seasons of local validation data is the minimum credible evidence base for a purchase decision [24].
What is the realistic replacement cycle for connected field hardware?
Soil and weather sensors typically need replacement every five to seven years; GNSS receivers and displays run eight to ten years. Budget refresh capex from year one rather than treating deployment as one-time spend [25].
Which emerging use case is most underestimated?
Insurance underwriting. Field-level activity records let insurers price parametric crop cover with far tighter loss ratios, and several reinsurers are already sourcing this data commercially [3].    
Author
Author
Author Profile
Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, agricultural technology journals, peer-reviewed publications, and authoritative agricultural organizations. Key sources included:

Government & Regulatory Sources:

US Department of Agriculture (USDA) – Agricultural Research Service and National Agricultural Statistics Service

European Commission – Directorate-General for Agriculture and Rural Development (DG AGRI)

Food and Agriculture Organization (FAO) of the United Nations

National Institute of Food and Agriculture (NIFA)

US Environmental Protection Agency (EPA) – Office of Water and Agriculture Division

EU Open Data Portal – Agricultural Statistics

USDA National Agricultural Library (NAL) – Ag Data Commons

US Geological Survey (USGS) – Earth Resources Observation and Science (EROS) Center

National Oceanic and Atmospheric Administration (NOAA) – National Weather Service Climate Prediction Center

Indian Ministry of Agriculture & Farmers Welfare – National e-Governance Plan in Agriculture (NeGP-A)

China Ministry of Agriculture and Rural Affairs

Brazil Ministry of Agriculture, Livestock and Food Supply (MAPA)

Industry & Standards Organizations:

International Society of Precision Agriculture (ISPA)

Association of Equipment Manufacturers (AEM) – Agriculture Sector

AgGateway – Agricultural Data Standards (ADAPT protocol, SPADE project)

IEEE Standards Association – IoT in Agriculture Working Group

LoRa Alliance – Smart Agriculture Use Cases

GSM Association (GSMA) – AgriTech program and mAgri initiatives

Open Geospatial Consortium (OGC) – Agriculture Domain Working Group

American Society of Agricultural and Biological Engineers (ASABE)

European Agricultural Machinery Association (CEMA)

International Society for Agricultural Engineering (CIGR)

Technology & Research Databases:

IEEE Xplore Digital Library – Smart Agriculture and IoT systems

ScienceDirect – Precision Agriculture and Computer Electronics in Agriculture journals

Web of Science – Agricultural technology and remote sensing

Google Scholar – Digital agriculture and big data analytics

MDPI – Agriculture, Sensors, and Remote Sensing journals

National Center for Biotechnology Information (NCBI) – Agricultural biotechnology

arXiv – Computer vision and machine learning in agriculture

Market Intelligence & Industry Reports:

International Data Corporation (IDC) – Worldwide Agriculture IT Spending

GSMA Intelligence – Mobile for Development in Agriculture

Research Institute of Organic Agriculture (FiBL) – Global Organic Farming Statistics

International Food Policy Research Institute (IFPRI)

McKinsey Global Institute – Agriculture and Food Systems

World Economic Forum – Food Systems Initiative

CGIAR – Big Data in Agriculture Platform

These sources were used to collect adoption statistics, technology deployment data, regulatory frameworks, precision agriculture metrics, IoT sensor market data, satellite imagery usage trends, and digital farming infrastructure analysis across Internet of Things, Big Data Analytics, Cloud Computing, Drone Technology, and Satellite Imagery segments.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, CTOs, VPs of Agricultural Technology, Chief Digital Officers, heads of product development, directors of regulatory affairs, and commercial leads from companies that make precision agriculture equipment, IoT sensors, agri-tech software, drone/UAV manufacturers, satellite imagery providers, and cloud infrastructure vendors were among the supply-side sources. Agricultural enterprise CIOs, farm operation managers, directors of agricultural cooperatives, agronomists, precision agriculture consultants, supply chain managers from food processing companies, and sustainability officers from large-scale farming operations were examples of demand-side suppliers.

Market segmentation across technology types (IoT, Big Data, Cloud, Drones, Satellite), deployment models (On-Premises, Cloud-Based, Hybrid), application areas (Precision Farming, Livestock Monitoring, Greenhouse Automation, Supply Chain Management, Farm Management Software), and end-use sectors (Farms, Agricultural Cooperatives, Food Processing Enterprises, Research Institutions) was validated by primary research. In addition to gathering information on adoption hurdles, pricing models, interoperability issues, data privacy concerns, and ROI expectations for linked agriculture investments, research validated product development roadmaps.


Primary Respondent Breakdown

By Company Tier:

Tier 1 (>USD 50B revenue): 38%

Tier 2 (USD 5B-50B revenue): 32%

Tier 4 (

[Note: Tier 1 includes diversified technology conglomerates and major agricultural equipment manufacturers; Tier 2 includes established agri-tech and precision agriculture specialists; Tier 3 includes emerging IoT and drone technology providers; Tier 4 includes niche software and sensor startups as of 2024]

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.