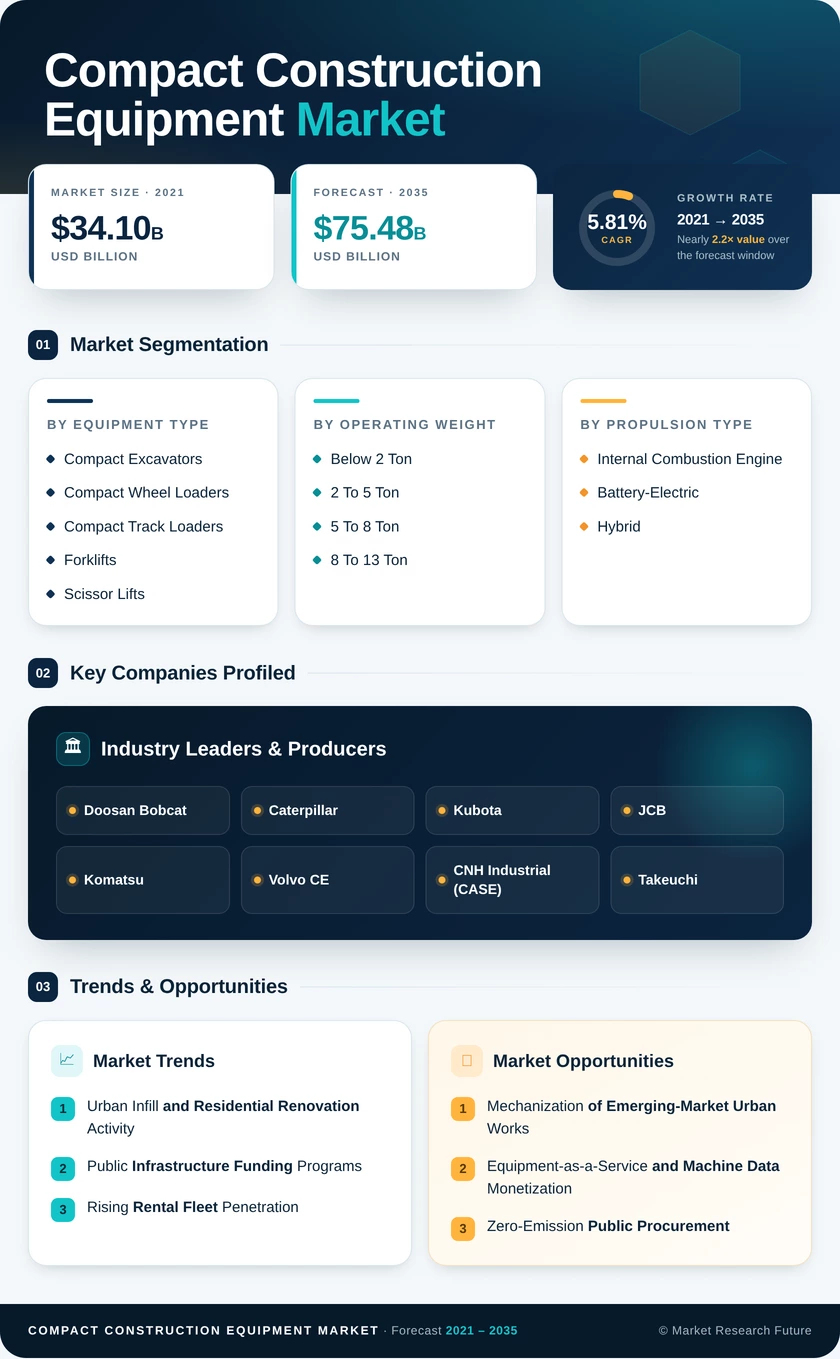
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Equipment Type | Compact Excavators, Compact Wheel Loaders, Compact Track Loaders, Forklifts, Scissor Lifts | Compact Track Loaders (33.10% share) | Compact Excavators (9.75% CAGR) |
| By Operating Weight | Below 2 Ton, 2 To 5 Ton, 5 To 8 Ton, 8 To 13 Ton | 2 To 5 Ton (44.60% share) | Below 2 Ton (7.06% CAGR) |
| By Propulsion Type | Internal Combustion Engine, Battery-Electric, Hybrid | Internal Combustion Engine (87.40% share) | Battery-Electric (16.02% CAGR) |
| By End-User Vertical | Residential Construction, Commercial Construction, Infrastructure, Utilities and Energy, Industrial and Others | Residential Construction (31.20% share) | Utilities and Energy (7.15% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America (43.70% share (2025)) | Europe (7.45% CAGR (2026–2035)) |
Market Segmentation Overview
By Equipment Type
| Sub-Segment | Key Trend |
|---|---|
| Compact Excavators | Zero-tail-swing designs and early battery-electric launches |
| Compact Wheel Loaders | Steady demand in aggregate, recycling, and snow operations |
| Compact Track Loaders | High-flow hydraulics expand year-round attachment use |
| Forklifts | Vertical material placement on mixed-use developments |
| Scissor Lifts | Electric drive standard for indoor fit-out work |
Compact Track Loaders lead because a sealed undercarriage and low ground pressure let one machine run augers, trenchers, and cold planers across soft terrain. Compact Excavators grow fastest as utility trenching moves into dense streets where reduced tail swing avoids lane closures. Excavators are also the first class where battery duty cycles match a full shift, which reinforces their growth lead.
By Operating Weight
| Sub-Segment | Key Trend |
|---|---|
| Below 2 Ton | Retractable undercarriages for doorway access |
| 2 To 5 Ton | Pickup-towable balance of lift and portability |
| 5 To 8 Ton | Deeper trenching and small bridge repairs |
| 8 To 13 Ton | Hybrid swing-energy recovery to curb fuel burn |
The 2 To 5 Ton class dominates because contractors can move it with standard trucks, which avoids permit and haulage costs. Below 2 Ton machines grow fastest by reaching basements, interiors, and historic districts where European axle-load caps restrict larger units. The 5 To 8 Ton and 8 To 13 Ton classes serve power-intensive utility work but face slower electrification.
By Propulsion Type
| Sub-Segment | Key Trend |
|---|---|
| Internal Combustion Engine | Stage V after-treatment raises ownership costs |
| Battery-Electric | LFP chemistry and falling pack prices drive adoption |
| Hybrid | Fuel savings without charging-infrastructure dependence |
Internal Combustion Engine units dominate because remote sites and heavy duty cycles still exceed practical battery capacity. Battery-Electric grows fastest as zero-emission site mandates and a 20% pack-price decline in 2024 improve the economics. Hybrid systems appeal where charging access is uncertain, but they remain a bridge technology rather than an end state.
By End-User Vertical
| Sub-Segment | Key Trend |
|---|---|
| Residential Construction | Infill, remodeling, and accessory dwelling units |
| Commercial Construction | Site preparation and material staging |
| Infrastructure | Water mains, sidewalks, and rail maintenance |
| Utilities and Energy | Solar, wind, grid, and fiber trenching |
| Industrial and Others | Plant maintenance, agriculture, and landscaping |
Residential Construction leads because tight lots, noise limits, and short job durations suit sub-5-ton machines rented by small builders. Utilities and Energy grows fastest as grid and broadband programs fund trenching on sensitive terrain where low-impact machines reduce restoration costs. Infrastructure and Commercial Construction provide steady base demand that is less exposed to housing cycles.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA