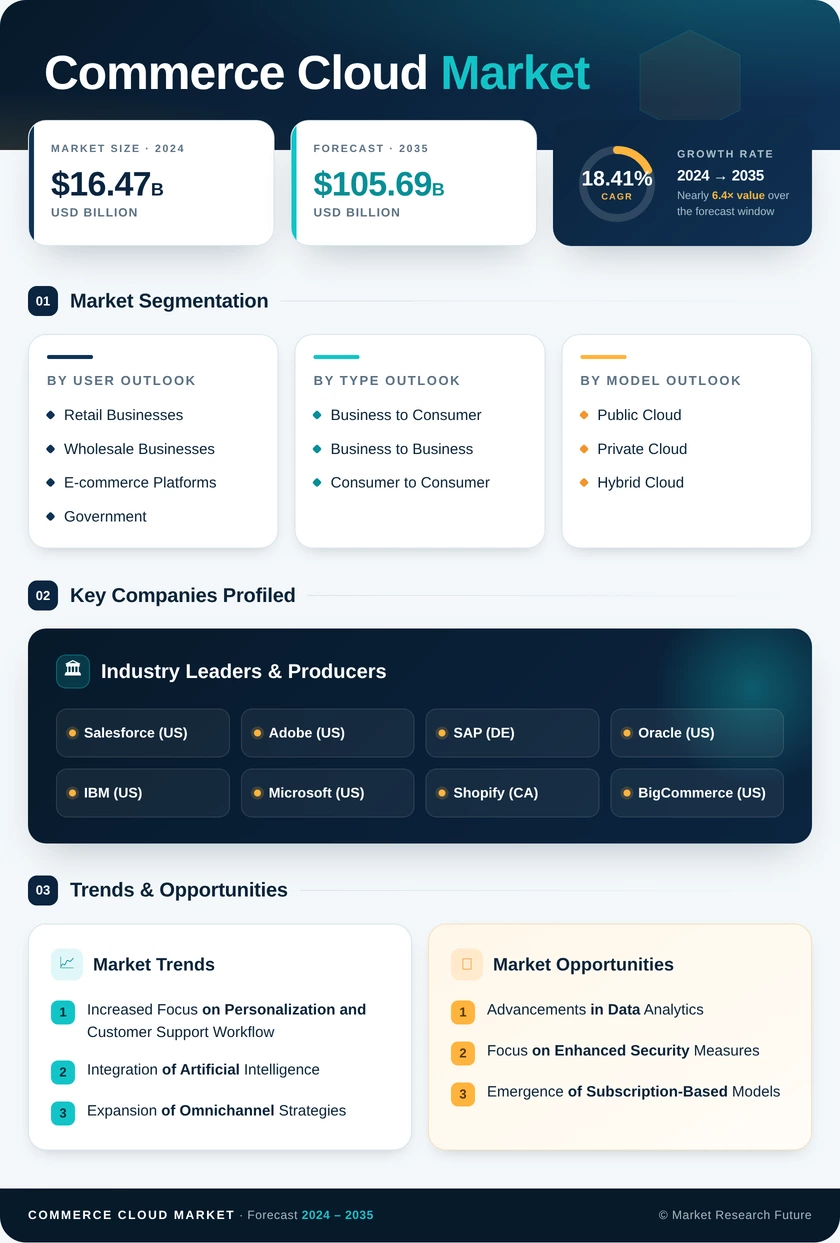
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| End-User Industry | Fashion and Apparel; Travel and Tourism; Food and Beverage; Grocery and Pharmaceuticals; Others | Fashion and Apparel | Grocery and Pharmaceuticals |
| Platform | B2C Commerce; B2B Commerce; Marketplace-as-a-Service | B2C Commerce | Marketplace-as-a-Service |
| Deployment Model | Public Cloud; Private Cloud; Composable / Hybrid | Public Cloud | Composable / Hybrid |
| Organization Size | Small and Medium Enterprises; Large Enterprises | Small and Medium Enterprises | Large Enterprises |
| Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By End-User Industry
| Sub-Segment | Key Trend |
| Fashion and Apparel | Visual AI-driven merchandising and composable storefront proliferation |
| Travel and Tourism | Dynamic bundling of ancillary services at checkout |
| Food and Beverage | Rapid-delivery and subscription-model integration |
| Grocery and Pharmaceuticals | Regulated checkout compliance and cold-chain API adoption |
| Others | Industrial B2B catalog digitization and electronics D2C expansion |
Fashion and Apparel remains the largest vertical, driven by the industry's inherent need for fast seasonal launches, rich visual experiences, and multi-region localization. Grocery and Pharmaceuticals is the fastest-growing segment, propelled by regulatory complexity and consumer demand for same-day delivery.
By Platform
| Sub-Segment | Key Trend |
| B2C Commerce | Hyper-personalization engines and social-commerce integrations |
| B2B Commerce | Self-service procurement portals with ERP-native connectivity |
| Marketplace-as-a-Service | First-party brands onboarding curated third-party sellers for incremental margin |
B2C Commerce dominates platform-level revenue, but Marketplace-as-a-Service is gaining share rapidly as enterprise retailers realize the margin potential of hosting third-party sellers on their owned digital properties.
By Deployment Model
| Sub-Segment | Key Trend |
| Public Cloud | Pay-as-you-go scalability for peak-season traffic elasticity |
| Private Cloud | Data-sovereign deployments for regulated industries |
| Composable / Hybrid | MACH-certified multi-vendor stack architectures |
Public Cloud remains the default deployment model, though composable and hybrid architectures are growing fastest as enterprises seek best-of-breed flexibility and reduced vendor lock-in.
By Organization Size
| Sub-Segment | Key Trend |
| Small and Medium Enterprises | Low-code, subscription-priced platform adoption |
| Large Enterprises | Multi-brand, multi-region composable commerce stacks |
SMEs account for the majority of Commerce Cloud Market adoption by volume, drawn by affordable subscription models and pre-built templates. Large Enterprises drive higher per-deal contract values through complex, multi-vendor implementations.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA