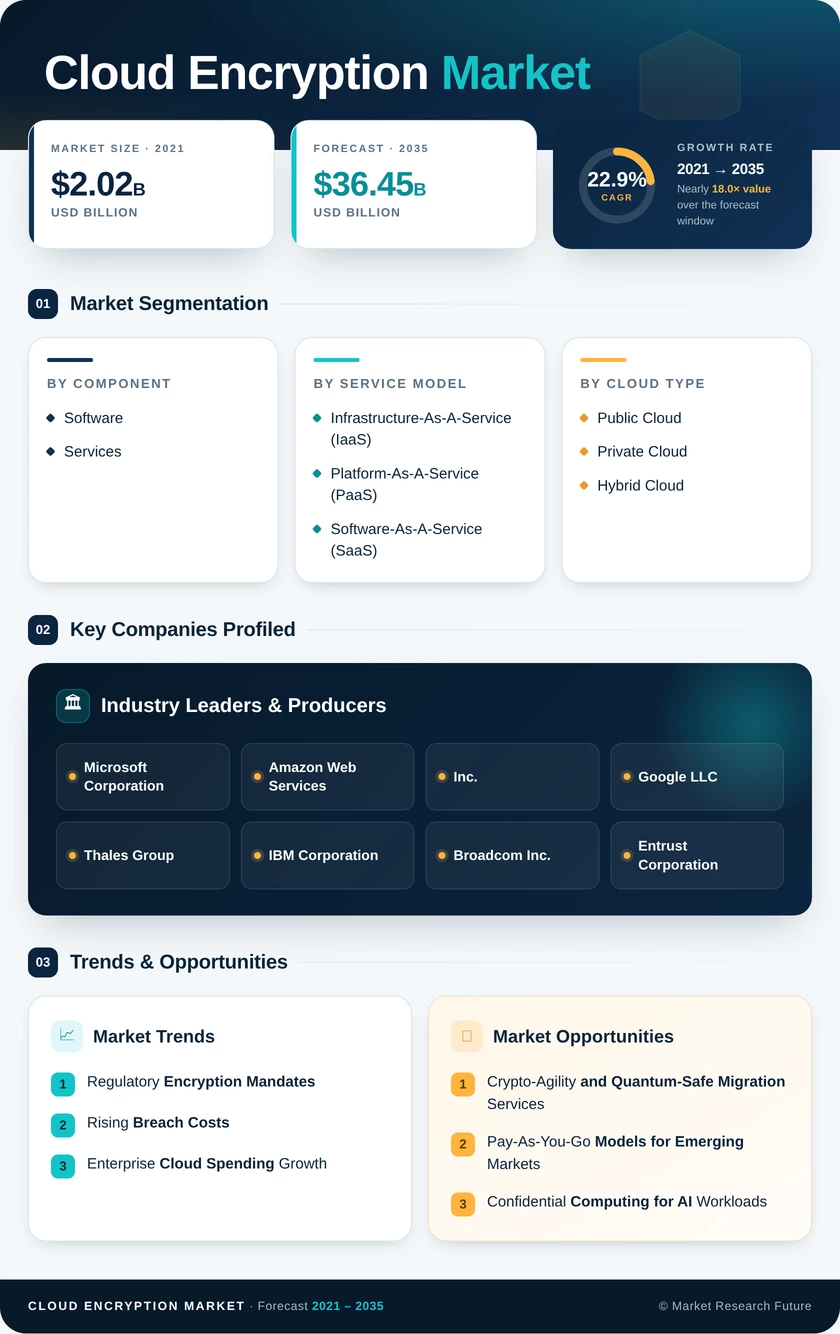
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Component | Software; Services | Software (60.0% share) | Services (27.2% CAGR) |
| By Service Model | Infrastructure-As-A-Service (IaaS); Platform-As-A-Service (PaaS); Software-As-A-Service (SaaS) | Infrastructure-As-A-Service (IaaS) (43.0% share) | Software-As-A-Service (SaaS) (29.3% CAGR) |
| By Cloud Type | Public Cloud; Private Cloud; Hybrid Cloud | Public Cloud (55.0% share) | Hybrid Cloud (30.9% CAGR) |
| By End-user Industry | BFSI; Healthcare and Life Sciences; IT and Telecom; Government and Public Sector; Retail and E-commerce; Manufacturing; Other End-user Industries | BFSI (26.2% share) | Healthcare and Life Sciences (26.5% CAGR) |
| By Enterprise Size | Large Enterprises; Small and Medium Enterprises (SMEs) | Large Enterprises (66.5% share) | Small and Medium Enterprises (SMEs) (25.4% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America (39.0% share) | Asia-Pacific (26.1% CAGR) |
Market Segmentation Overview
By Component
| Sub-Segment | Key Trend |
|---|---|
| Software | Policy engines with hardware offload and post-quantum algorithm support |
| Services | Managed key operations and crypto-agility consulting |
Software leads because cipher libraries, key vaults, and policy engines are the first purchase in any encryption rollout across storage, virtual machines, and containers. Services grow fastest as firms lacking cryptographic engineers outsource key ceremonies, audits, and quantum-readiness planning. The widening skills gap keeps shifting incremental spend from licenses toward expert-delivered operations.
By Service Model
| Sub-Segment | Key Trend |
|---|---|
| Infrastructure-As-A-Service (IaaS) | Customer-managed keys for block, object, and boot storage |
| Platform-As-A-Service (PaaS) | Transparent encryption in managed databases and container platforms |
| Software-As-A-Service (SaaS) | Field-level encryption and customer-held keys in business applications |
Infrastructure-As-A-Service (IaaS) leads because every higher service depends on encrypted compute, storage, and network layers, often linked to customer HSMs. Software-As-A-Service (SaaS) grows fastest as CRM, health record, and treasury applications move to subscriptions and buyers demand key control without workflow changes. Platform-as-a-Service (PaaS) sits between the two, driven by managed database adoption.
By Cloud Type
| Sub-Segment | Key Trend |
|---|---|
| Public Cloud | Native hyperscaler key services bundled into platform pricing |
| Private Cloud | On-premises HSMs for classified and critical workloads |
| Hybrid Cloud | Unified key planes spanning sovereign and hyperscale estates |
Public Cloud leads on sheer workload volume and bundled key services. Hybrid Cloud grows fastest because regulated firms keep sensitive data in private or sovereign locations while using public capacity for analytics, which requires a single key custody layer across both. Private Cloud remains the choice for defense and critical infrastructure where external hosting is restricted.
By End-user Industry
| Sub-Segment | Key Trend |
|---|---|
| BFSI | DORA and PCI DSS-driven key governance |
| Healthcare and Life Sciences | Mandatory ePHI encryption proposals and IoMT data growth |
| IT and Telecom | Multi-tenant platform encryption |
| Government and Public Sector | Zero-trust and post-quantum migration mandates |
| Retail and E-commerce | Payment and customer profile protection |
| Manufacturing | IP and operational data protection in cloud |
| Other End-user Industries | Education, media, and energy cloud adoption |
BFSI leads because transaction integrity and dual-control key requirements under DORA and PCI DSS make encryption mandatory across banking workloads. Healthcare and Life Sciences grows fastest as electronic health records and connected medical devices multiply, breach costs peak, and proposed HIPAA rules move encryption from optional to required. Government and Public Sector demand accelerates with federal post-quantum deadlines.
By Enterprise Size
| Sub-Segment | Key Trend |
|---|---|
| Large Enterprises | Layered protection including confidential computing and PQC pilots |
| Small and Medium Enterprises (SMEs) | Consumption-priced key services and prebuilt policy templates |
Large Enterprises lead because sprawling IT estates, complex data classification, and heavy compliance penalties justify multi-layer encryption investments. Small and Medium Enterprises (SMEs) grow fastest as pay-as-you-go key services and automated templates remove the need for in-house security staff. Asia-Pacific digital-commerce firms account for much of that SME momentum.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA