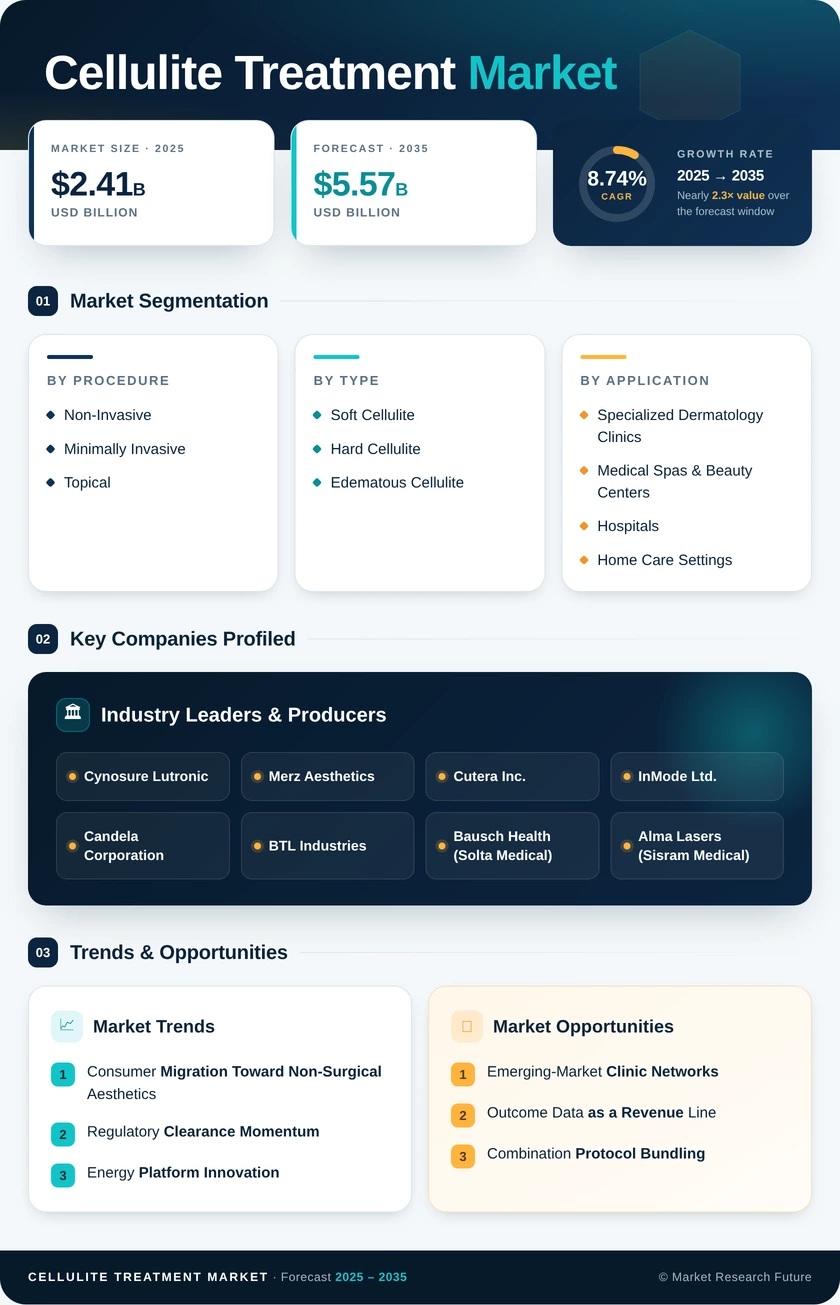
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Procedure | Minimally Invasive, Non-Invasive, Topical | Non-Invasive | Minimally Invasive |
| By Cellulite Type | Soft Cellulite, Hard Cellulite, Edematous Cellulite | Soft Cellulite | Edematous Cellulite |
| By End User | Hospitals, Specialized Dermatology Clinics, Medical Spas & Beauty Centers, Home Care Settings | Specialized Dermatology Clinics | Home Care Settings |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Procedure
| Sub-Segment | Key Trend |
| Minimally Invasive | Premium pricing supported by the longest documented outcome persistence |
| Non-Invasive | Highest procedure volume; multi-modality consoles compressing session times |
| Topical | Retail and clinic-resale channel growth; positioned as maintenance adjunct |
Procedure choice is increasingly driven by evidence duration rather than price. Practices are building tiered menus that route structurally tethered cases toward subcision while reserving energy-based sessions for broader, lower-severity presentations.
By Cellulite Type
| Sub-Segment | Key Trend |
| Soft Cellulite | Largest treated cohort; standard energy protocols dominate |
| Hard Cellulite | Younger patient base; demand for deeper septal remodelling |
| Edematous Cellulite | Fastest expansion as lymphatic-driven presentations gain clinical recognition. |
Diagnostic differentiation is the quiet story here. As clinicians formally classify presentation type before treatment, protocol selection is becoming more precise and reported satisfaction scores are improving accordingly.
By End User
| Sub-Segment | Key Trend |
| Hospitals | Bundled into broader aesthetic surgery pathways; modest growth |
| Specialized Dermatology Clinics | Credibility centre; sets protocol norms and captures premium cases. |
| Medical Spas & Beauty Centers | Volume engine; chain procurement reshaping supplier pricing |
| Home Care Settings | Fastest-growing channel via clinic-resold maintenance units |
Channel economics diverge sharply. Dermatology clinics defend margin through clinical positioning while spas compete on throughput, and the home segment is emerging less as a substitute than as a retention tool that keeps patients engaged between clinic visits.
By Geography
| Sub-Segment | Key Trend |
| North America | Private-capital clinic consolidation compressing console pricing |
| Europe | MDR Annex XVI compliance concentrating supply among larger manufacturers |
| Asia-Pacific | Korean export momentum and Chinese tier-2 city clinic buildout |
| South America | Instalment financing sustaining volumes through currency volatility. |
| Middle East & Africa | Sovereign health-city investment and medical tourism licensing growth |
Regional divergence is widening rather than converging. Developed markets are consolidating around evidence and service quality, while emerging regions are being won on affordable platform tiers and financing structures.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA