Cannula Market (2026 - 2035)

ID: MRFR/MED/5472-HCR 90 Pages Rahul Gotadki Last Updated: October 27, 2026
Cannula Market Research Report By Type (Conventional Cannula, Specialized Cannula, Safety Cannula, Angled Cannula), By Material (Plastic, Metal, Silicone, Polymer), By Application (Drug Delivery, Blood Transfusions, Fluid Management, Surgery), By End Use (Hospitals, Clinics, Home Care Settings, Ambulatory Surgical Centers) and By Regional (North America, Europe, South America, Asia-Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
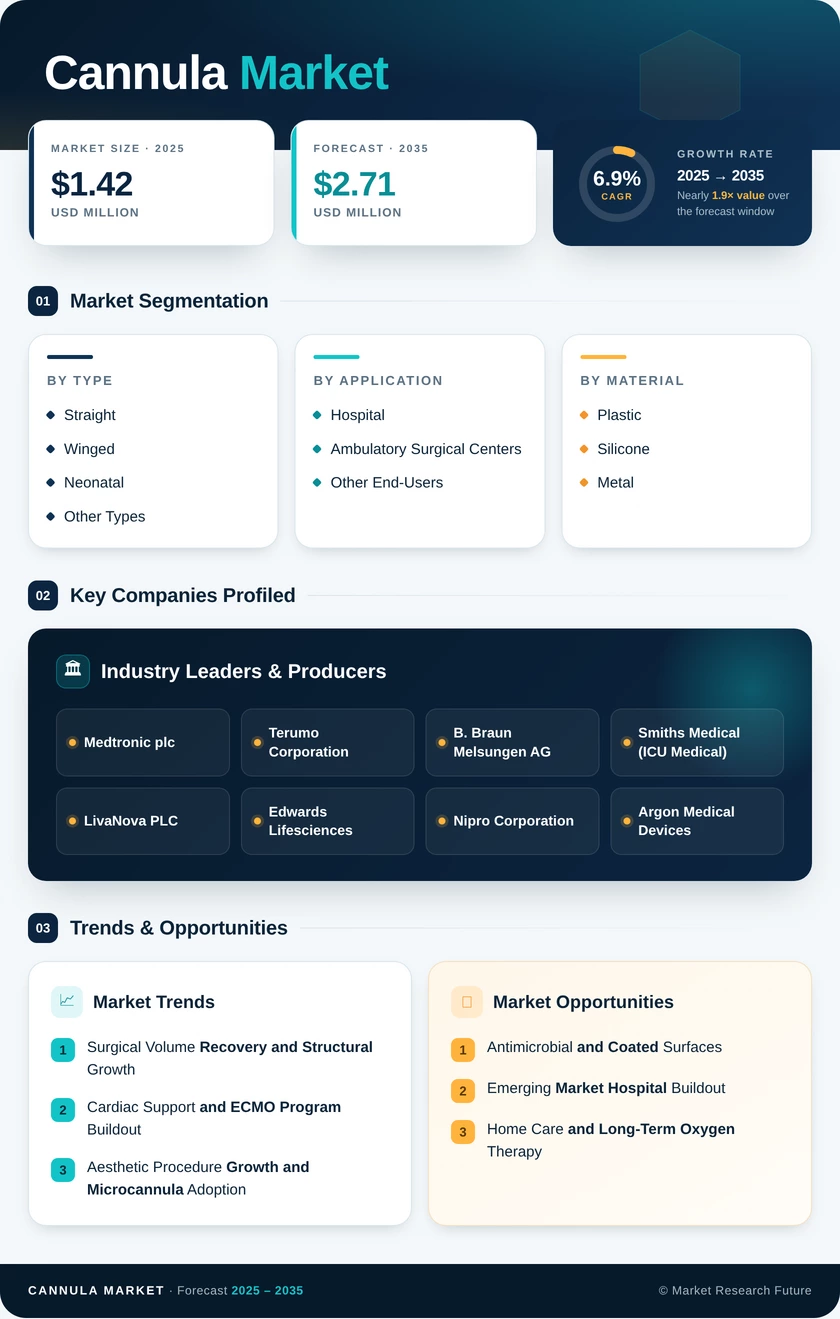
Cannula Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.90%
2025 Market SizeUSD 1.42 Billion
2035 Market SizeUSD 2.71 Billion
Key Players
Medtronic plc
Terumo Corporation
B. Braun Melsungen AG
Smiths Medical
LivaNova PLC
Edwards Lifesciences
Opportunities
  • Antimicrobial and Coated Surfaces
  • Emerging Market Hospital Buildout
  • Home Care and Long-Term Oxygen Therapy
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 Takeaways by Product |
    2. 2.2 Takeaways by End User |
    3. 2.3 Takeaways by Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2025) |
    2. 3.2 Current & Forecast Market Size (2026–2035) |
    3. 3.3 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Surgical Volume Recovery and Structural Growth |
    2. 4.2 Cardiac Support and ECMO Program Buildout |
    3. 4.3 Aesthetic Procedure Growth and Microcannula Adoption
  5. 5 Restraints Impact Analysis |
    1. 5.1 Tender-Driven Price Compression |
    2. 5.2 Regulatory Cost Under EU MDR
  6. 6 Opportunities |
    1. 6.1 Antimicrobial and Coated Surfaces |
    2. 6.2 Emerging Market Hospital Buildout |
    3. 6.3 Home Care and Long-Term Oxygen Therapy |
    4. 6.4 Digital Traceability and Data-Enabled Service Models |
    5. 6.5 Paediatric and Neonatal Specialization
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of MEA
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Materials Reformulation |
    2. 8.2 Manufacturing Regionalization |
    3. 8.3 Robotic and Precision Delivery |
    4. 8.4 Sustainability and Single-Use Scrutiny
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Product | |
      1. 9.1.1 Cardiac | |
      2. 9.1.2 Vascular | |
      3. 9.1.3 Arthroscopy | |
      4. 9.1.4 Nasal | |
      5. 9.1.5 Other Products |
    2. 9.2 By Type | |
      1. 9.2.1 Neonatal | |
      2. 9.2.2 Straight | |
      3. 9.2.3 Winged | |
      4. 9.2.4 Other Types |
    3. 9.3 By Application | |
      1. 9.3.1 Cardiovascular | |
      2. 9.3.2 Oxygen Therapy | |
      3. 9.3.3 Orthopaedic | |
      4. 9.3.4 Neurology | |
      5. 9.3.5 Other Applications |
    4. 9.4 By Material | |
      1. 9.4.1 Silicone | |
      2. 9.4.2 Plastic | |
      3. 9.4.3 Metal |
    5. 9.5 By End-User | |
      1. 9.5.1 Hospital | |
      2. 9.5.2 Ambulatory Surgical Centers | |
      3. 9.5.3 Other End-Users
  10. 10 Competitive Landscape |
    1. 10.1 Market Share Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Becton, Dickinson and Company | |
      2. 10.3.2 Medtronic plc | |
      3. 10.3.3 Terumo Corporation | |
      4. 10.3.4 B. Braun Melsungen AG | |
      5. 10.3.5 Smiths Medical (ICU Medical) | |
      6. 10.3.6 LivaNova PLC | |
      7. 10.3.7 Edwards Lifesciences | |
      8. 10.3.8 Nipro Corporation | |
      9. 10.3.9 Argon Medical Devices | |
      10. 10.3.10 Teleflex Incorporated | |
      11. 10.3.11 Romsons Group
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Citations |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Cannula Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Cannula Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Cannula Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Cannula Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Cannula Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Cannula Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Cannula Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Cannula Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Cannula Market Size, by Product, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Cannula Market Size, by Type, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Cannula Market Size, by Application, 2021–2035 (USD Billion) |
  29. TABLE 14 Global Cannula Market Size, by Material, 2021–2035 (USD Billion) |
  30. TABLE 15 Global Cannula Market Size, by End-User, 2021–2035 (USD Billion) |
  31. TABLE 16 North America Cannula Market Size, by Product, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Cannula Market Size, by Product, 2021–2035 (USD Billion) |
  33. TABLE 18 Asia-Pacific Cannula Market Size, by Product, 2021–2035 (USD Billion) |
  34. TABLE 19 North America Cannula Market Size, by End-User, 2021–2035 (USD Billion) |
  35. TABLE 20 Europe Cannula Market Size, by End-User, 2021–2035 (USD Billion) |
  36. TABLE 21 Asia-Pacific Cannula Market Size, by End-User, 2021–2035 (USD Billion) |
  37. TABLE 22 Competitive Benchmarking Matrix – Global Cannula Market, 2026 |
  38. TABLE 23 Company Profiles – Key Players, Global Cannula Market |
  39. TABLE 24 Recent Developments & Strategic Announcements, 2023–2025 |
  40. TABLE 25 Report Scope & Methodology Summary |
  41. TABLE 26 Detailed Sources & Citations Index
  42. 16 LIST OF FIGURES |
  43. FIGURE 1 Global Cannula Market Dynamics – Drivers, Restraints & Opportunities |
  44. FIGURE 2 Industry Value Chain Analysis – Cannula Manufacturing to Clinical Use |
  45. FIGURE 3 Porter's Five Forces Analysis – Global Cannula Market |
  46. FIGURE 4 Global Cannula Market Size Trend, 2021–2035 (USD Billion) |
  47. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) |
  48. FIGURE 6 Market Share by Product, 2026 vs 2035 (%) |
  49. FIGURE 7 Market Share by Type, 2026 vs 2035 (%) |
  50. FIGURE 8 Market Share by Application, 2026 vs 2035 (%) |
  51. FIGURE 9 Market Share by Material, 2026 vs 2035 (%) |
  52. FIGURE 10 Market Share by End-User, 2026 vs 2035 (%) |
  53. FIGURE 11 Regional Share Distribution, 2025 (%) |
  54. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) |
  55. FIGURE 13 North America Country-Level Share Breakdown (%) |
  56. FIGURE 14 Asia-Pacific Country-Level Growth Comparison (%) |
  57. FIGURE 15 Competitive Landscape – Estimated Revenue Share Bands, 2026 |
  58. FIGURE 16 Strategic Positioning Matrix – Scale vs Specialization

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ProductCardiac, Vascular, Arthroscopy, Nasal, Other ProductsCardiacNasal
By TypeNeonatal, Straight, Winged, Other TypesStraightNeonatal
By ApplicationCardiovascular, Oxygen Therapy, Orthopaedic, Neurology, Other ApplicationsCardiovascularOxygen Therapy
By MaterialSilicone, Plastic, MetalPlasticSilicone
By End-UserHospital, Ambulatory Surgical Centers, Other End-UsersHospitalAmbulatory Surgical Centers
By GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Product

Sub-SegmentKey Trend
CardiacWire-reinforced designs expanding with ECMO program permanence
VascularSafety-engineered variants displacing conventional access devices
ArthroscopySmaller-gauge instruments enabling day-case orthopaedic surgery
NasalHigh-flow and comfort-optimized designs entering home care channels
Other ProductsAesthetic microcannulas growing on non-surgical procedure volumes


Product mix within the Cannula Market is bifurcating. High-specification cardiac devices carry engineering barriers that protect margin, while vascular access has become a scale business where distribution reach matters more than design.

By Type

Sub-SegmentKey Trend
NeonatalSub-3 Fr sizing driving specialized materials investment
StraightVolume backbone under sustained tender price pressure
WingedSecurement and needlestick-prevention features becoming standard.
Other TypesProcedure-specific geometries supporting niche premium pricing.


Straight configurations retain the largest volume position, but neonatal designs attract disproportionate development attention because clinical protocols increasingly specify device characteristics rather than accepting adult-derived substitutes.

By Application

Sub-SegmentKey Trend
CardiovascularHighest revenue intensity per procedure across all applications
Oxygen TherapyMigration from hospital to home distribution channels
OrthopaedicArthroscopic case growth in ambulatory settings
NeurologyNeurointerventional expansion in tertiary centres
Other ApplicationsDiagnostic and aesthetic uses broadening the base


Cardiovascular applications anchor value in the Cannula Market while oxygen therapy drives unit growth. The two demand different commercial models — one clinical-specialist selling, the other consumer-adjacent distribution.

By Material

Sub-SegmentKey Trend
SiliconePhthalate substitution accelerating adoption across clinical categories
PlasticCost leadership sustained despite regulatory pressure on PVC.
MetalConfined to rigid-access and reusable instrument applications


Material selection is now a regulatory decision as much as an engineering one, with REACH restrictions reshaping formulation roadmaps across supplier portfolios.

By End-User

Sub-SegmentKey Trend
HospitalConsolidated purchasing through group contracting organizations
Ambulatory Surgical CentersFaster procurement cycles favoring responsive suppliers
Other End-UsersHome care and specialty clinics emerging as distinct channels


End-user structure explains much of the competitive dynamic within the Cannula Market: hospitals reward scale and contract depth, while ambulatory and home channels reward service responsiveness and product differentiation.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.