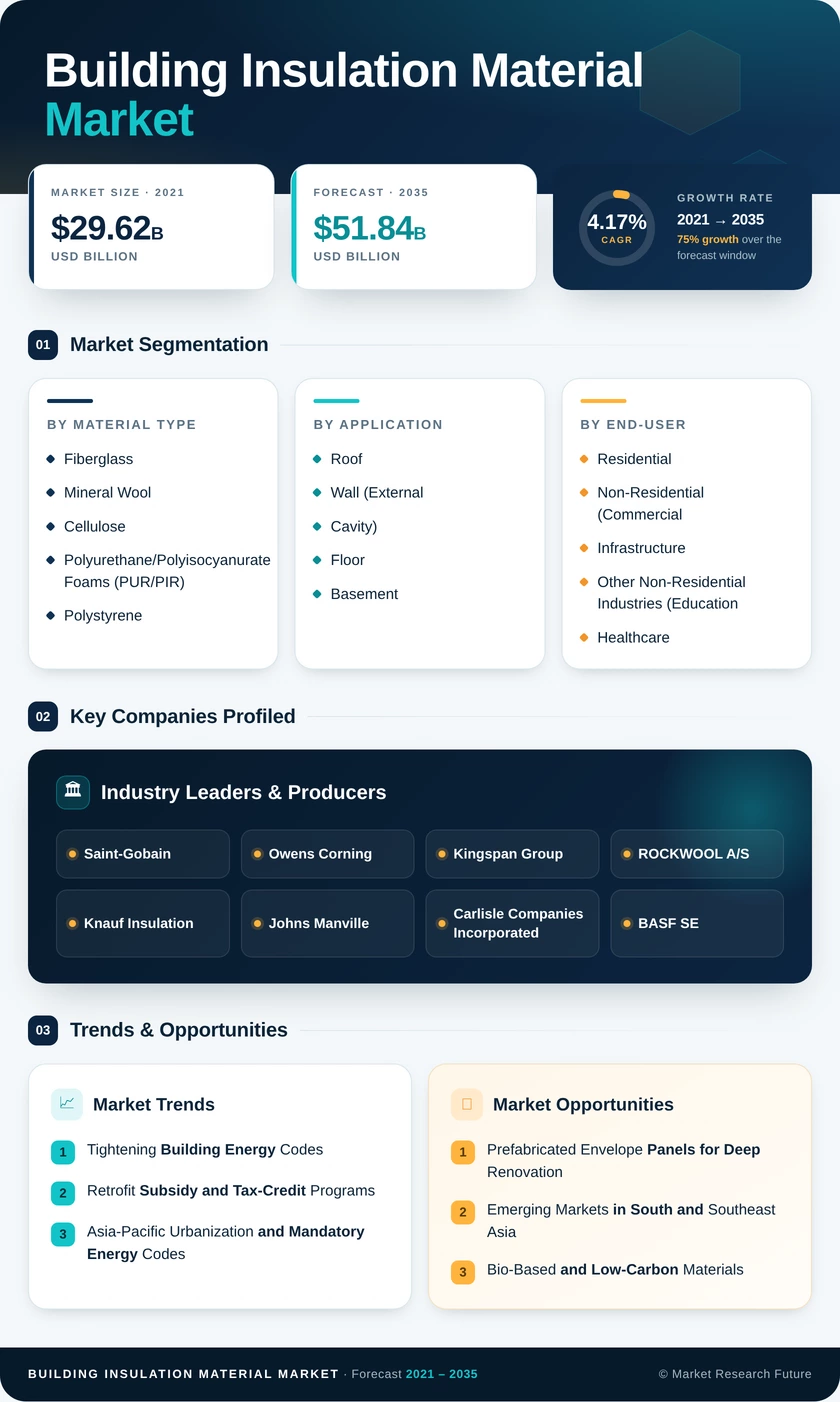
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Material Type | Fiberglass; Mineral Wool; Cellulose; Polyurethane/Polyisocyanurate Foams (PUR/PIR); Polystyrene; Other Materials (Cork, Aerogel and Vacuum Insulation Panels, Spray Foams, Hemp, Calcium-Silicate, etc.) | Fiberglass (32.6% share) | Polystyrene (4.4% CAGR) |
| By Application | Roof; Wall (External and Cavity); Floor and Basement; Ceiling and Attic; Acoustic Partition and HVAC Duct | Roof (27.4% share) | Acoustic Partition and HVAC Duct (5.1% CAGR) |
| By End-User | Residential; Non-Residential (Commercial, Infrastructure, Other Non-Residential Industries (Education, Healthcare, Civic and Religious,etc.)) | Residential (53.4% share) | Commercial (4.3% CAGR) |
| By Installation | New Construction; Renovation | New Construction (60.7% share) | Renovation (5.7% CAGR) |
| By Region | Asia-Pacific; North America; Europe; South America; Middle East and Africa | Europe (34.8% share) | Asia-Pacific (5.3% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Fiberglass | Default choice for code-minimum residential walls and attics |
| Mineral Wool | Gaining in fire-regulated façades and high-rise retrofits |
| Cellulose | Blown-in attic retrofits with low embodied carbon |
| Polyurethane/Polyisocyanurate Foams (PUR/PIR) | Conversion from HFC to HFO blowing agents |
| Polystyrene | Rigid exterior boards and below-grade use |
| Other Materials (Cork, Aerogel and Vacuum Insulation Panels, Spray Foams, Hemp, Calcium-Silicate, etc.) | Premium products for space-constrained retrofits |
Fiberglass leads with a 32.6% share because installers know it well and it meets code-minimum wall and attic requirements at the lowest cost. Polystyrene grows fastest at a 4.4% CAGR, as newer codes call for rigid boards over studs to cut thermal bridging. Mineral Wool and PUR/PIR compete in commercial envelopes, where fire rules and R-value per inch decide the choice.
| Sub-Segment | Key Trend |
|---|
| Roof | Low-slope commercial re-roofing with PIR and mineral wool boards |
| Wall (External and Cavity) | EU façade renovation and cavity-fill retrofits |
| Floor and Basement | Under-slab foam for frost-protected foundations |
| Ceiling and Attic | Blown-in loose-fill to cut labor time |
| Acoustic Partition and HVAC Duct | Duct efficiency rules and open-plan acoustic upgrades |
Roof leads with a 27.4% share, since commercial re-roofing almost always adds insulation boards and roofs lose the most heat per square metre. Acoustic Partition and HVAC Duct grows fastest at a 5.1% CAGR, pulled by ASHRAE 90.1-2022 duct requirements and data center construction. Wall (External and Cavity) demand depends heavily on European façade renovation budgets.
| Sub-Segment | Key Trend |
|---|
| Residential | Subsidy-backed attic and wall retrofits in owner-occupied homes |
| Non-Residential | Office conversions, public renovation mandates and infrastructure projects |
Residential leads with a 53.4% share, because retrofit subsidies and net-zero mandates target homeowners first. Within Non-Residential, Commercial grows fastest at a 4.3% CAGR as office-to-residential conversions require complete envelope re-insulation. Infrastructure and Other Non-Residential Industries add steady public-sector demand under EU public-building renovation quotas.
| Sub-Segment | Key Trend |
|---|
| New Construction | Each code cycle raises required insulation thickness |
| Renovation | Subsidies and prefabricated panels shorten payback and site time |
New Construction leads with a 60.7% share, since every new building must meet the current energy code. Renovation grows fastest at a 5.7% CAGR, as BEG, MaPrimeRénov' and U.S. rebates bring paybacks under six years and high interest rates make upgrading existing buildings more attractive than building new.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA