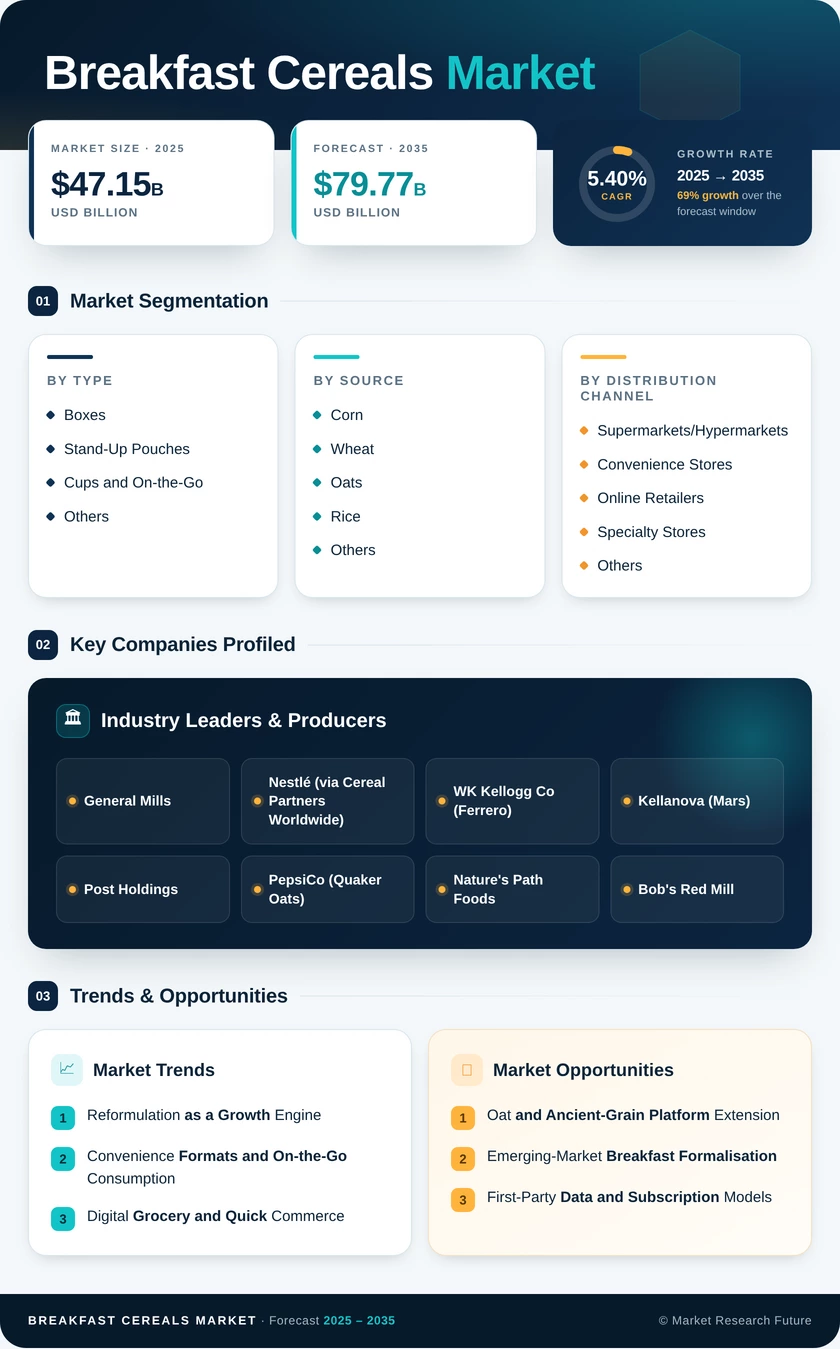
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Product Type | Ready-to-Cook Cereals; Ready-to-Eat Cereals | Ready-to-Eat Cereals | Ready-to-Cook Cereals |
| Ingredient Source | Wheat; Corn; Oats; Rice; Others | Corn | Oats |
| Packaging Type | Boxes; Stand-Up Pouches; Cups and On-the-Go; Others | Boxes | Cups and On-the-Go |
| Distribution Channel | Supermarkets/Hypermarkets; Convenience Stores; Online Retailers; Specialty Stores; Others | Supermarkets/Hypermarkets | Online Retailers |
| Age Group | Adults; Children; Teenagers & Young Adults | Adults | Children |
| Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Ready-to-Eat Cereals | Portion-controlled cups and reduced-sugar reformulation displacing legacy family boxes |
| Ready-to-Cook Cereals | Instant oat sachets and flavoured porridge expanding beyond winter seasonality |
Ready-to-eat retains scale advantages in distribution and merchandising, but ready-to-cook is converting nutrition-motivated households at a faster clip. The gap narrows steadily through 2035 as instant formats erode the preparation-time barrier.
By Ingredient Source
| Sub-Segment | Key Trend |
| Wheat | Whole-grain biscuit and shredded formats retaining European relevance |
| Corn | Cost-efficient volume base facing gradual share erosion |
| Oats | Soluble-fibre claims driving the strongest launch pipeline globally |
| Rice | Gluten-free and crisped-texture applications sustaining niche demand |
| Others | Millet, sorghum, and buckwheat entering mainstream blends |
Grain selection has become a nutrition positioning decision rather than a procurement decision. Oats capture disproportionate innovation attention because they carry an authorised health claim that competing bases cannot replicate.
By Packaging Type
| Sub-Segment | Key Trend |
| Boxes | Paperboard recyclability offsetting share loss to flexible formats |
| Stand-Up Pouches | Freight and material cost efficiency driving conversion |
| Cups and On-the-Go | Fastest-growing format, aligned to portion-control regulation |
| Others | Bulk and refill formats serving zero-waste retail channels |
Packaging economics now interact directly with labelling regulation. Single-serve formats reduce disclosed per-portion sugar and fat figures, converting a compliance requirement into a merchandising advantage.
By Distribution Channel
| Sub-Segment | Key Trend |
| Supermarkets/Hypermarkets | Assortment breadth anchoring volume despite share decline |
| Convenience Stores | Single-serve and immediate-consumption growth |
| Online Retailers | Subscription replenishment and quick commerce scaling rapidly |
| Specialty Stores | Organic and free-from assortment concentration |
| Others | Discounters gaining on private-label price positioning |
Channel migration reshapes brand-building economics. Digital routes lower the cost of category entry for challengers while shifting promotional spend from trade allowances toward retail media placements.
By Age Group
| Sub-Segment | Key Trend |
| Adults | Protein, fibre, and weight-management claims driving value growth |
| Children | Reformulated, dye-free products restoring parental permission |
| Teenagers & Young Adults | Snacking crossover and bold flavour innovation |
Adult consumption underwrites category value while the children's segment supplies volume recovery. Reformulation is the shared enabler across both, and manufacturers that reformulate once for the strictest jurisdiction gain global portfolio efficiency.
By Geography
| Sub-Segment | Key Trend |
| North America | Dye removal and front-of-pack compliance reshaping portfolios |
| Europe | Organic penetration and private-label pressure running in parallel |
| Asia-Pacific | Category formation in India and ASEAN via quick commerce |
| South America | Warning-label regimes accelerating sugar reduction |
| Middle East & Africa | Fortification programmes and premium Gulf imports |
Regional divergence is widening rather than converging. Mature markets compete on nutrition credentials and pricing power; emerging markets compete on distribution reach and localised grain and flavour adaptation.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA