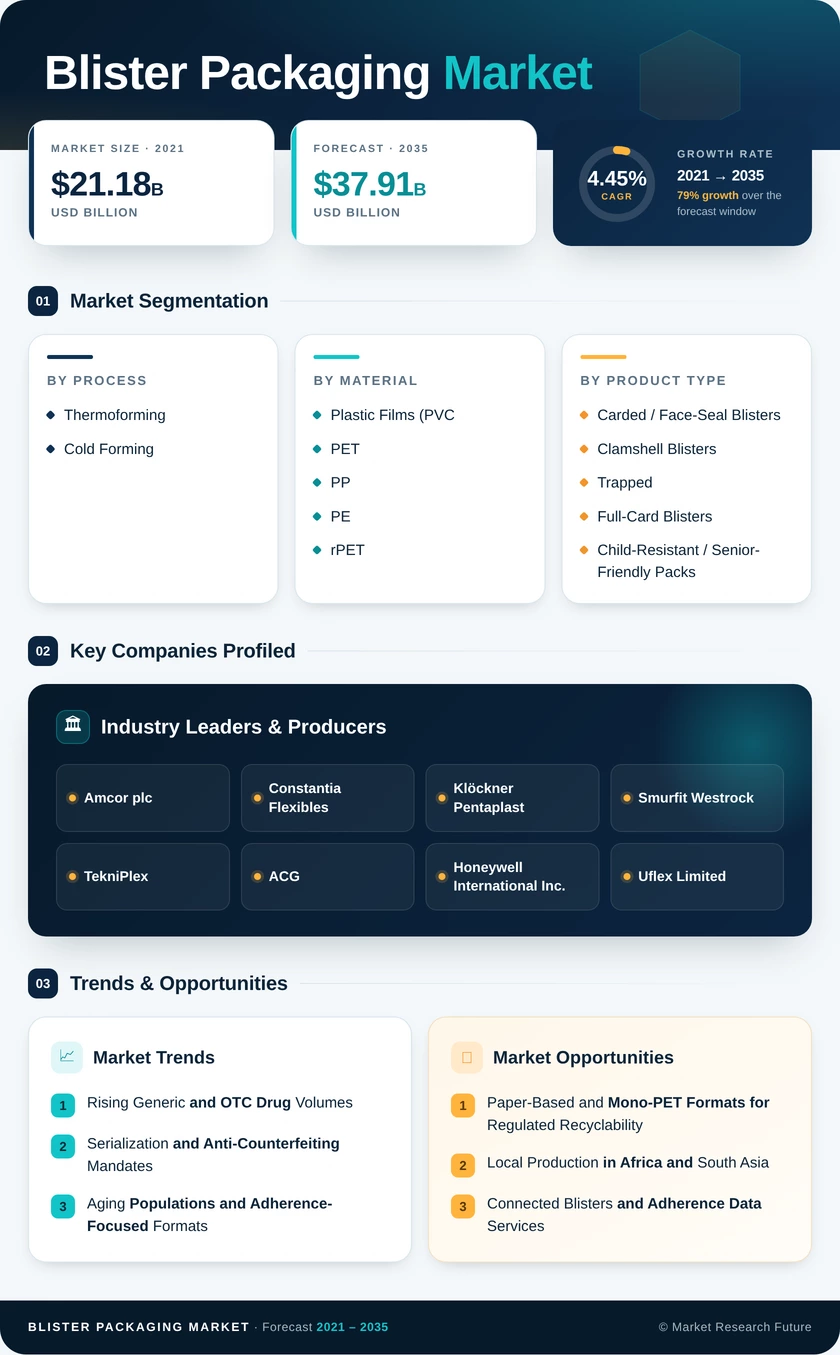
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Process | Thermoforming, Cold Forming | Thermoforming | Cold Forming |
| By Material | Plastic Films (PVC, PET, PP, PE, rPET, COP, others), Aluminium (ALU-ALU, PTP foil), Paper and Paperboard | Plastic Films (PVC, PET, PP, PE, rPET, COP, others) | Aluminium (ALU-ALU, PTP foil) |
| By Product Type | Carded / Face-Seal Blisters, Clamshell Blisters, Trapped and Full-Card Blisters, Child-Resistant / Senior-Friendly Packs | Carded / Face-Seal Blisters | Clamshell Blisters |
| By End-User Industry | Pharmaceuticals, Nutraceuticals and Dietary Supplements, Consumer Electronics and Hardware, Personal Care and Cosmetics, Other End-user Industry | Pharmaceuticals | Nutraceuticals and Dietary Supplements |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East and Africa | Asia-Pacific | Middle East and Africa |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Thermoforming | Low tooling cost and high line speeds for generics |
| Cold Forming | Moisture- and light-sensitive drug formulations |
Within the Blister Packaging Market, Thermoforming accounts for 66.9% of 2025 revenue. Low tooling cost, fast line speeds and compatibility with PVC, PET and PP films make it the default for generic and OTC tablets. Cold Forming grows faster, at a 5.2% CAGR, because aluminium-aluminium cavities provide near-zero moisture and light transmission for hygroscopic and high-potency molecules. Thinner foils and hybrid laminates are narrowing the material-cost gap between the two processes.
| Sub-Segment | Key Trend |
|---|
| Plastic Films (PVC, PET, PP, PE, rPET, COP, others) | Formability and established supply chains |
| Aluminium (ALU-ALU, PTP foil) | High-barrier protection and lidding demand |
| Paper and Paperboard | Recyclability mandates and brand sustainability goals |
Material selection in the Blister Packaging Market still centers on Plastic Films (PVC, PET, PP, PE, rPET, COP, others), which hold a 63.4% share thanks to mature resin supply and easy forming. Aluminium (ALU-ALU, PTP foil) generates USD 6.43 billion, covering cold-form cavities and push-through lidding. Paper and Paperboard is the fastest-growing material at a 6.5% CAGR, as fiber-based cards with functional coatings win vitamin and OTC SKUs seeking recyclability credentials.
| Sub-Segment | Key Trend |
|---|
| Carded / Face-Seal Blisters | Cost-efficient carding for high-volume drugs |
| Clamshell Blisters | Premium presentation and mechanical protection |
| Trapped and Full-Card Blisters | Pilfer resistance and retail security |
| Child-Resistant / Senior-Friendly Packs | Poison prevention rules and aging patients |
Carded / Face-Seal Blisters lead the Blister Packaging Market product mix with 48.3% share, supported by inexpensive inline carding and broad acceptance for prescription and OTC drugs. Clamshell Blisters are the fastest-growing type at a 7.1% CAGR, gaining in nutraceuticals, medical devices and electronics where rigidity and premium presentation matter. Trapped and Full-Card Blisters add pilfer resistance, while Child-Resistant / Senior-Friendly Packs answer CPSC rules and aging-population needs.
| Sub-Segment | Key Trend |
|---|
| Pharmaceuticals | Tamper evidence and serialization mandates |
| Nutraceuticals and Dietary Supplements | Preventive health and premium formats |
| Consumer Electronics and Hardware | Retail display and theft deterrence |
| Personal Care and Cosmetics | Sample and single-use formats |
| Other End-user Industry | Toys, stationery and household goods |
Pharmaceuticals absorb 61.4% of Blister Packaging Market demand, reflecting regulatory preference for tamper-evident, serialization-ready formats. Nutraceuticals and Dietary Supplements grow fastest at a 7.0% CAGR as probiotics and omega-3 products migrate from bottles. Consumer Electronics and Hardware, Personal Care and Cosmetics, and Other End-user Industries provide steadier retail-driven demand for hang-tab and clamshell formats, cushioning exposure to drug-pricing cycles.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA