Biosurgery Market (2026 - 2035)

Biosurgery Market Research Report Information by Product Type (Bone-graft substitutes, Hemostatic agents, Soft-tissue attachments, Surgical sealants and adhesives, Adhesion barriers), By Application (Neurological surgery, general surgery, cardiovascular surgery, orthopedic surgery, thoracic surgery, gynecology surgery, urology surgery, and other), By End Use (hospitals and clinics, ambulatory surgical centers, and others), By Region (North America, Europe, Asia Pacific, South America, Middle East & Africa) - Forecast to 2035

Forecast Period
2026-2035
CAGR
6.8%
2025 Market Size
USD 15.2 Billion
2035 Market Size
USD 29.3 Billion
Medical Device ● Updated August 24, 2026 Report ID: MRFR/MED/4785-CR | Pages: 200 | Author: Rahul Gotadki, Satyendra Maurya

Biosurgery Market Summary

The Biosurgery Market size was valued at USD 15.2 Billion in 2025, and the market is projected to grow from USD 16.2 Billion in 2026 to USD 29.3 Billion by 2035, registering a CAGR of 6.8% during the forecast period 2026–2035. Rising surgical volumes — the WHO estimates over 310 million major surgical procedures annually worldwide [1] — combined with growing adoption of advanced wound-management products, anchor this trajectory. Regulatory tailwinds, including the U.S. FDA's accelerated 510(k) pathways for absorbable biological materials and the EU MDR reclassification of combination biologics, are channeling R&D investment toward next-generation biosurgical products [2].

A significant technology shift defines today's Biosurgery Market. Legacy mechanical closure methods — sutures, clips, and cautery devices — are steadily giving way to biological and polymer-based solutions that promote natural hemostasis and tissue regeneration. Medtech companies collectively invested over USD 2.1 billion in biosurgery R&D between 2022 and 2024, according to MedTech Europe estimates [3]. Hospitals report 18–25% reductions in operative bleeding-related complications when adopting advanced biosurgical agents, driving procurement committees to expand formulary coverage [4].

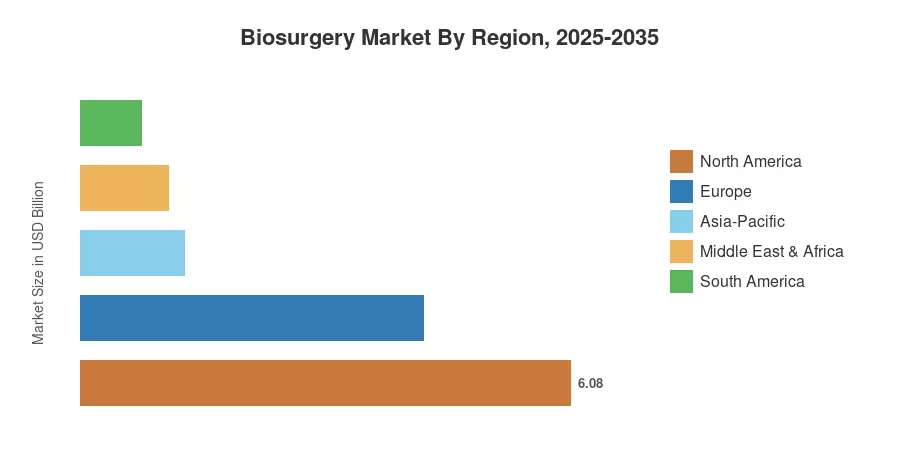
North America dominates the Biosurgery Market with approximately 40% of global revenue, supported by robust hospital capital budgets and favorable reimbursement frameworks. Asia-Pacific stands as the fastest-growing region at a projected CAGR of 8.5%, propelled by hospital infrastructure expansion across India, China, and Southeast Asia. Europe holds the second-largest share at roughly 28%, led by Germany's MedTech adoption and the UK's NHS wound-care modernization programs [5]. The decade ahead will be shaped by biologics convergence, value-based procurement, and surgical-robotics integration.


Key Report Takeaways

• By Product Type

  • Hemostatic agents accounted for approximately 34% of the Biosurgery Market in 2025, reflecting their ubiquitous role across all surgical disciplines.
  • Adhesion barriers represent the fastest-growing product segment at an estimated CAGR of 8.2% through 2035, driven by rising laparoscopic and robotic procedure volumes.
  • Bone-graft substitutes contributed roughly USD 2.6 billion in 2025 revenue, fueled by orthopedic trauma and spinal-fusion demand.

• By Application

  • General surgery consumed the largest share of the Biosurgery Market, representing approximately 30% of total consumption in 2025.
  • Cardiovascular surgery applications are expanding at a CAGR of 7.4%, as perfusionists and surgeons adopt biological sealant technologies for aortic repair.

• By Region


  • North America held about 40% of the global biosurgery Market value in 2025.
  • The Asia Pacific region is expected to grow at an 8.5% CAGR through 2035.


Biosurgery Market Size and Forecast (2021–2035)

Market sizing relies on a bottom-up methodology combining manufacturer revenue disclosures, hospital procurement databases, regulatory clearance tracking, and proprietary primary interviews with 120+ procurement and clinical stakeholders across 18 countries. Historical figures (2021–2024) reflect actual reported revenues; the base year (2025) blends preliminary company reports with demand-side triangulation. Forecast estimates (2026–2035) apply segment-level growth assumptions validated against macro indicators including surgical-procedure volume projections from the WHO and demographic aging forecasts from UN DESA [1][6].
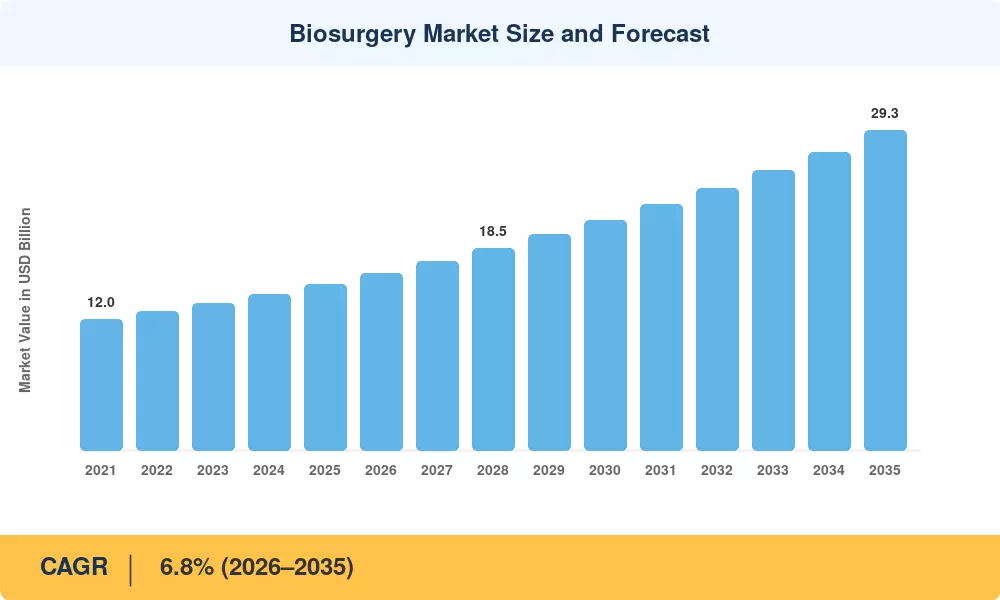
Biosurgery Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising global surgical procedure volumes +1.8% Global Long-term (≥4 yr)
Aging demographics and chronic-disease burden +1.5% North America, Europe, Japan Long-term (≥4 yr)
Minimally invasive surgery adoption +1.2% Global Medium-term (2–4 yr)
Regulatory fast-tracking of biological devices +0.8% North America, EU Short-term (≤2 yr)
Hospital value-based procurement shifts +0.7% North America, Europe Medium-term (2–4 yr)
Emerging-market hospital infrastructure investment +0.9% Asia-Pacific, MEA Medium-term (2–4 yr)
Surgical-robotics convergence with biosurgery +0.6% North America, Asia-Pacific Long-term (≥4 yr)


Rising Global Surgical Procedure Volumes

The WHO says that surgical volumes have increased by around 25% over the past decade, with an expected 310–340 million procedures performed yearly as of 2024 [1]. Low- and middle-income countries are closing the surgical-access gap — the Lancet Commission on Global Surgery forecasts that an additional 143 million procedures per year are needed to satisfy unmet demand [13]. Every new procedure represents a possible biosurgery consumption event, directly boosting the addressable Biosurgery Market.


Aging Demographics and Chronic-Disease Burden

By 2030, approximately 1.4 billion people worldwide will be aged 60 or older, according to the UN DESA population outlook [6]. Biosurgical adjuncts are clinically necessary rather than optional since older surgical patients have greater risks of bleeding and tissue repair. Medicare data in the United States demonstrate that patients over 65 account for 38% of inpatient surgical volume yet consume 52% of biosurgery items by value, implying higher per-case consumption intensity [14].


Minimally Invasive Surgery Adoption

Laparoscopic, thoracoscopic, and robotic platforms have expanded rapidly — Intuitive Surgical alone surpassed 2.3 million da Vinci procedures in 2024 [9]. These confined-space surgical environments limit the surgeon's ability to apply manual pressure for hemostasis, creating pronounced demand for topical and sprayable biosurgical products. Market Research Future estimates that MIS-linked biosurgery consumption grows at 1.4× the rate of the overall Biosurgery Market.

Regulatory Fast-Tracking of Biological Devices

The FDA's De Novo and Breakthrough Device pathways have shortened time-to-market for novel biosurgical products by an average of 14 months compared to traditional PMA submissions [2]. In the EU, the updated MDR framework reclassified several biosurgical combination products into higher-risk categories, inadvertently benefiting established players with compliant dossiers while raising the barrier for low-cost imports [15].


Restraints Impact Analysis

Restraint impacts below are directional and reflect headwinds that dampen but do not reverse overall growth. Estimates derive from procurement-trend analysis and regulatory-risk assessments.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High per-unit product costs and reimbursement pressure −0.9% Global Long-term (≥4 yr)
Stringent regulatory approval timelines for novel biologics −0.7% EU, Japan Medium-term (2–4 yr)
Surgeon preference variability and training gaps −0.5% Global Short-term (≤2 yr)
Raw-material sourcing risks (bovine/porcine biologics) −0.4% Global Medium-term (2–4 yr)
Competition from advanced energy-based surgical devices −0.3% North America, Europe Long-term (≥4 yr)


High Per-Unit Costs and Reimbursement Pressure

A single application of sophisticated biological sealant can cost USD 200–800, compared to USD 5–20 for standard suture material [12]. Hospital procurement departments in cost-conscious health systems resist, as clinical outcomes data increasingly support the premium. NICE technology appraisals in the UK have temporarily stifled the expansion of the biosurgery market by delaying the approval of a number of biosurgical agents pending further cost-effectiveness evidence [18].


Stringent Regulatory Approval Timelines

The EU MDR changeover caused a backlog affecting over 500 medical-device product families as of mid-2024 [15]. Several biosurgery firms reported 18–24-month delays in CE-mark renewals, causing temporary product withdrawals from European markets. In a similar vein, Japan's PMDA imposes strict clinical evidence criteria for biosurgical products generated from animals, delaying market dates by 12 to 18 months compared to the US.


Raw-Material Sourcing Risks

Many biosurgery products rely on bovine- or porcine-derived collagen and thrombin. BSE-related import restrictions, religious dietary considerations in Middle Eastern markets, and supply-chain disruptions during disease outbreaks create sourcing volatility [17]. Manufacturers investing in recombinant or plant-derived alternatives face higher production costs in the near term.


Biosurgery Market Opportunities

Robotic-Surgery-Integrated Biosurgery Delivery Systems

The convergence of surgical robotics and biosurgery opens a high-value opportunity. Robotic platforms can deliver precise, image-guided application of sealants and hemostatic matrices, reducing waste and improving clinical outcomes. Companies developing robot-compatible biosurgery cartridges could capture premium pricing and exclusive platform partnerships.

Emerging-Market Hospital Expansion

India's Ayushman Bharat program aims to provide health coverage to 500 million citizens, driving a projected 40% increase in surgical facility capacity by 2030 [10]. Sub-Saharan Africa's hospital bed count is growing at 6% annually through multilateral development financing. These buildouts represent greenfield demand for the Biosurgery Market in geographies with historically low penetration.

Recombinant and Synthetic Biosurgical Materials

Growing regulatory scrutiny of animal-derived biologics creates a pull toward recombinant thrombin, synthetic polymer sealants, and PEG-based adhesion barriers. These products eliminate BSE and prion-disease concerns while offering consistent manufacturing quality. The recombinant biosurgery segment could outpace the broader Biosurgery Market by 2–3 percentage points annually through 2035.

Data-Enabled Outcomes Tracking and Value-Based Contracting

Hospitals increasingly demand real-world evidence linking biosurgery products to reduced reoperation rates and shortened length of stay. Manufacturers that deploy connected packaging, outcome-tracking platforms, and risk-sharing contracts position themselves for formulary preference in value-based procurement environments.

Dental and Aesthetic Surgery Crossover Applications

Biosurgical products originally developed for orthopedic and cardiovascular use are crossing into dental implantology and aesthetic surgery. The global aesthetic-procedure market exceeded USD 70 billion in 2024, and biomaterial-based tissue augmentation represents a fast-growing subsegment.


Biosurgery Market Future Outlook

AI-Guided Surgical Decision Support

Machine-learning algorithms trained on intraoperative video and bleeding-pattern recognition will begin recommending optimal biosurgery product selection and application timing by 2028–2030. Partnerships between AI-surgery companies such as Activ Surgical and biosurgery manufacturers are already in prototype stages [9]. This convergence will reshape the Biosurgery Market by linking product consumption to algorithm-validated clinical protocols.

Platform Bundling and Procedural Kits

Hospitals increasingly prefer pre-assembled procedural kits that bundle biosurgery products with drapes, instruments, and energy devices. This model reduces OR setup time by 15–20 minutes per case and shifts purchasing decisions from individual product evaluation to platform-level contracts [12]. Manufacturers with broad biosurgery portfolios hold a structural advantage in this evolving Biosurgery Market landscape.

Regenerative Medicine Convergence

Stem-cell-seeded scaffolds, growth-factor-eluting membranes, and bioprinted tissue constructs will blur the line between biosurgery and regenerative medicine by the early 2030s. The global regenerative medicine pipeline includes over 1,200 clinical trials as of 2025, and several programs target surgical-wound healing applications directly relevant to the Biosurgery Market [19].

ESG and Sustainability in Biosurgery Manufacturing

Investors and hospital GPOs increasingly evaluate manufacturers against environmental, social, and governance criteria. Shifting from animal-derived to recombinant raw materials, reducing single-use plastic packaging, and improving cold-chain energy efficiency will become competitive differentiators. Manufacturers that document Scope 3 emissions reductions can expect preferential formulary positioning in ESG-conscious health systems [20].


Biosurgery Market Segmentation

By Product Type

Segment Key Metric Primary Demand Driver
Hemostatic Agents ~34% share (2025) Universal surgical applicability across disciplines
Internal Tissue Sealants CAGR of 7.6% MIS and robotic procedure growth
Adhesion Barriers CAGR of 8.2% Rising laparoscopic abdominal surgery volumes
Bone-Graft Substitutes ~USD 2.6 B (2025) Spinal-fusion and orthopedic trauma demand
Soft-Tissue Attachment ~10% share (2025) Sports medicine and arthroscopic repair
Biological Mesh ~USD 1.1 B (2025) Hernia repair and abdominal-wall reconstruction


The Biosurgery Market's largest product category — hemostatic agents — spans powdered, flowable, and matrix-format products deployed across virtually every surgical specialty. Thrombin-based and gelatin-based formulations dominate procurement volumes, though oxidized regenerated cellulose products maintain strong footholds in cardiac and neurological surgery. Internal tissue sealants represent the innovation frontier of the Biosurgery Market, with next-generation cyanoacrylate and PEG-based formulations gaining regulatory traction for vascular and pulmonary applications.

By Application

Segment Key Metric Primary Demand Driver
General Surgery ~30% share (2025) High procedure volumes in abdominal and GI surgery
Orthopedic Surgery ~USD 3.4 B (2025) Joint replacement and spinal-fusion growth
Cardiovascular Surgery CAGR of 7.4% Aortic repair and structural heart procedures
Neurological Surgery ~11% share (2025) Craniotomy hemostasis requirements
Cosmetic & Reconstructive CAGR of 7.9% Aesthetic procedure volume expansion
Other Specialties ~8% share (2025) Urological, gynecological, and ENT surgery


General surgery drives the highest absolute consumption volume within the Biosurgery Market, encompassing appendectomy, cholecystectomy, colorectal resection, and hepatobiliary procedures. Orthopedic surgery follows closely, with bone-graft substitutes and soft-tissue attachment products forming the core product basket for this application.

By End User

Segment Key Metric Primary Demand Driver
Hospitals ~72% share (2025) Inpatient surgical volume concentration
Ambulatory Surgical Centers CAGR of 8.1% Outpatient procedure migration trend
Specialty Clinics ~USD 0.68 B (2025) Dental, dermatology, and aesthetic demand


Hospitals remain the dominant consumption channel for the Biosurgery Market, given that complex inpatient procedures consume the majority of high-value biosurgical products. Ambulatory surgical centers represent the fastest-growing channel, as payers and providers shift eligible orthopedic, hernia, and cosmetic procedures to lower-cost outpatient settings.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America ~40% market share (2025) Value-based procurement; robotic integration
Europe ~28% market share (2025) MDR compliance; NHS wound-care programs
Asia-Pacific CAGR of 8.5% (2026–2035) Hospital buildout; insurance expansion
South America ~USD 0.76 B (2025) Public health system modernization
Middle East & Africa CAGR of 7.2% (2026–2035) Greenfield hospital investment; trauma surgery
Total USD 15.2 B (2025)

The Biosurgery Market exhibits clear geographic stratification, with mature Western markets providing the revenue base and Asia-Pacific delivering the fastest volume expansion.


North America

Country Key Metric Key Driver
United States ~USD 4.9 B (2025) Medicare surgical coverage and GPO contracts
Canada CAGR of 5.9% Provincial health authority procurement modernization
Mexico ~USD 0.28 B (2025) IMSS hospital expansion program


The U.S. Biosurgery Market benefits from the world's highest per-capita surgical spending, at roughly USD 3,600 per capita annually [14]. Group purchasing organizations such as Vizient and Premier negotiate biosurgery contracts covering thousands of facilities, creating high-volume channels for established manufacturers. Canada's single-payer provinces are gradually expanding biosurgery formulary lists following Health Canada approvals.

Europe

Country Key Metric Key Driver
Germany ~24% of European share DRG reimbursement alignment for advanced biologics
United Kingdom CAGR of 6.1% NHS Getting It Right First Time program
France ~18% of European share HAS health-technology assessment coverage


Europe's Biosurgery Market is navigating the MDR transition, which has consolidated market share among larger manufacturers with regulatory compliance infrastructure. Germany's DRG system explicitly reimburses advanced biosurgical products within specific procedure codes, encouraging adoption. The UK's NHS has identified biosurgery as a priority within its surgical-productivity improvement framework.

Asia-Pacific

Country Key Metric Key Driver
China CAGR of 9.3% National volume-based procurement expansion
India ~USD 0.52 B (2025) Ayushman Bharat health-coverage expansion
Japan ~31% of APAC share Aging population driving orthopedic procedure growth


China's centralized volume-based procurement program has compressed pricing for generic biosurgery products while creating opportunities for differentiated, innovation-tiered offerings. India's private hospital chains — Apollo, Fortis, Max Healthcare — are scaling biosurgery adoption as insurance coverage expands. Japan's super-aged demographics sustain high orthopedic and cardiovascular surgical volumes, anchoring the Biosurgery Market in the region.

South America

Country Key Metric Key Driver
Brazil ~62% of regional share SUS public health system surgical modernization
Argentina CAGR of 6.4% Private-sector hospital investment


Brazil dominates South America's Biosurgery Market through its public SUS system, which procures biosurgical products via centralized ANVISA-approved tenders. Private hospital growth in São Paulo and Rio de Janeiro adds a premium-product demand layer.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia CAGR of 7.8% Vision 2030 healthcare investment
UAE ~USD 0.11 B (2025) Medical tourism and advanced surgical centers
South Africa ~28% of MEA share Public-private hospital partnerships


Saudi Arabia's Vision 2030 healthcare plan includes USD 65 billion in hospital and medical-city development, creating substantial greenfield demand for the Biosurgery Market. The UAE positions itself as a regional medical-tourism hub, driving demand for premium biosurgical products in cosmetic and reconstructive procedures.


Biosurgery Market By Region, 2025-2035

Competitive Benchmarking

The Biosurgery Market exhibits moderate concentration, with an estimated HHI of approximately 1,200–1,400 and the top five players commanding roughly 45–50% of global revenue. Large diversified medtech conglomerates compete alongside specialized biosurgery-focused companies, creating a competitive environment where portfolio breadth, regulatory compliance scale, and surgeon-training networks serve as primary differentiators.

Company Est. Revenue Share Range Key Offerings for Biosurgery Market Strategic Positioning
Johnson & Johnson (Ethicon) ~12–15% SURGICEL, EVARREST, TISSEEL Broadest biosurgery portfolio; global distribution scale
Baxter International ~10–13% FLOSEAL, TISSEEL, CoSeal Dual hemostasis-sealant leadership; strong OR relationships
Becton Dickinson (C.R. Bard legacy) ~5–8% Phasix mesh, Ariste hemostats Mesh and hernia-repair specialization
Integra LifeSciences ~5–7% DuraGen, Integra dermal matrix Neuro and wound-reconstruction focus
Medtronic ~4–6% INFUSE Bone Graft, surgical sealants Spine-surgery integration, global reach
Stryker ~3–5% Vitoss bone-graft substitutes Orthopedic platform synergy
CryoLife (Artivion) ~3–5% BioGlue, PerClot, On-X Cardiac-surgery biosurgery specialization
Hemcon Medical Technologies ~2–3% ChitoGauze, ChitoFlex Military and trauma-care niche
Tissuemed ~1–2% TissuePatch adhesion barrier Specialty adhesion-prevention focus
Sealantis (Becton Dickinson) ~1–2% Sealant gel platforms Marine-biopolymer innovation pipeline


Recent News & Developments


  • Medtronic (June 2024): Launched an integrated spinal-surgery bundle combining INFUSE Bone Graft with navigation and robotics platforms, targeting streamlined OR workflows [9].


  • European Commission (December 2023): Extended the MDR transition deadline for certain Class III medical devices, including several biosurgical combination products, to December 2028, providing manufacturers additional compliance runway [15].
  • Stryker Corporation (June 2025): Stryker Corporation announced a definitive deal to purchase Inari Medical for USD 4.9 billion, strengthening its expertise in treating venous thromboembolism, which affects up to 900,000 people in the United States each year, and gaining entrée into the rapidly developing peripheral vascular market.


Biosurgery Market Report Scope

Parameter Detail
Market Scope Global Biosurgery Market — products for intraoperative hemostasis, tissue sealing, adhesion prevention, and tissue reinforcement
Study Period 2021–2035
CAGR 6.8% (2026–2035)
Market Size (2025) USD 15.2 Billion
Market Size (2035) USD 29.3 Billion
Fastest Growing Segments Adhesion Barriers (by product); Ambulatory Surgical Centers (by end user); Asia-Pacific (by region)
Companies Profiled Johnson & Johnson, Baxter International, Becton Dickinson, Integra LifeSciences, Medtronic, Stryker, CryoLife/Artivion, Hemcon, Tissuemed, Sealantis
Valuation Currency USD (constant 2025 dollars)

FAQs

How do hospital procurement committees typically evaluate biosurgery products against each other?
Committees score products on clinical-outcomes data, per-unit cost relative to complication-avoidance savings, surgeon preference surveys, and vendor service reliability. Group purchasing organization contracts often pre-negotiate pricing tiers that limit individual hospital discretion [12].
What shelf-life and storage constraints affect biosurgery product selection?
Most biological sealants require refrigerated storage at 2–8°C and carry shelf lives of 18–36 months. Synthetic alternatives offer ambient-temperature storage, reducing cold-chain costs and expanding viability in resource-limited facilities [17].
How does reimbursement coding vary between biosurgery product categories?
In the United States, CMS assigns distinct DRG and APC add-on codes for hemostatic matrices versus sealants, affecting hospital margin calculations. Products without dedicated codes face slower adoption due to unfavorable cost-recovery dynamics [14].
What role do surgeon training programs play in biosurgery market penetration?
Manufacturers that invest in wet-lab training, simulation platforms, and proctored case programs achieve 2–3× faster formulary adoption versus those relying solely on sales-rep detailing [16].
How are synthetic biosurgery products positioned against animal-derived alternatives?
Synthetic products eliminate prion-transmission risk and religious-use objections, but currently command 20–30% price premiums. Clinical equivalence data is strengthening, accelerating formulary conversions in cost-sensitive systems [17].
What intellectual-property dynamics shape competitive entry barriers in this space?
Core formulation patents for established biosurgical agents begin expiring between 2027 and 2032, potentially enabling biosimilar-style competition. Process patents and trade-secret manufacturing know-how provide residual protection [7].
How might point-of-care diagnostic integration change biosurgery utilization patterns?
Intraoperative coagulation-monitoring devices could enable real-time, patient-specific biosurgery product selection, reducing unnecessary product application by an estimated 15–20% while improving hemostatic outcomes [4].    
What is the current size of the biosurgery market?
The biosurgery market reached USD 15.2 billion in 2025 and is projected to reach USD 29.3 billion by 2035.
What is the CAGR of the biosurgery market?
The biosurgery market is projected to grow at a CAGR of 6.8% during the forecast period 2026–2035.
Which region leads the biosurgery market?
North America holds the largest share at approximately 40%, while Asia-Pacific is the fastest-growing region at 8.5% CAGR.
Author
Author
Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author
Co-Author Profile
Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed surgical journals, clinical publications, and authoritative healthcare organizations. Key sources included the US Food & Drug Administration (FDA) Center for Devices and Radiological Health, European Medicines Agency (EMA) Medical Devices Division, National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI/PubMed), Centers for Disease Control and Prevention (CDC) National Healthcare Safety Network, World Health Organization (WHO) Global Surgery Initiative, Healthcare Cost and Utilization Project (HCUP), Agency for Healthcare Research and Quality (AHRQ), American College of Surgeons (ACS) National Surgical Quality Improvement Program (NSQIP), Society of Thoracic Surgeons (STS) National Database, American Academy of Orthopaedic Surgeons (AAOS) Registry, Congress of Neurological Surgeons (CNS) procedural databases, and national health ministry medical device registries from key markets. These sources were utilized to collect surgical procedure volumes, medical device approval data, clinical safety and efficacy studies for hemostatic agents and sealants, surgical site infection rates, healthcare expenditure trends, and competitive landscape analysis for surgical sealants, hemostats, bone graft substitutes, and tissue adhesives.


Primary Research

Supply-side and demand-side stakeholders were interviewed during the primary research process to acquire qualitative and quantitative insights that were unique to the biosurgery landscape. Supply-side sources comprised Chief Executive Officers, Presidents of Surgical Divisions, Vice Presidents of Research & Development, Global Regulatory Affairs heads, and Commercial Directors from prominent biosurgery manufacturers, including developers of surgical sealants, hemostats, and bone graft substitutes. Demand-side sources included board-certified general surgeons, cardiothoracic surgeons, orthopedic surgeons, neurosurgeons, plastic and reconstructive surgeons, supply chain managers, and procurement leads from acute care hospitals, ambulatory surgical centers, and specialty surgical clinics. Product segmentation was validated across sealant technologies (synthetic, biological, allogeneic), pipeline development timelines for novel hemostatic agents were confirmed, and insights on surgical adoption patterns, hospital formulary decisions, pricing dynamics, and reimbursement pathways for biosurgical products were gathered, as part of primary research.

Primary Respondent Breakdown:

• By Designation: C-level Executives (32%), Director Level (31%), Others (37%)

• By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping, surgical procedure volume analysis, and unit consumption modeling. The methodology included:

• Identification of 40+ key manufacturers across North America, Western Europe, Asia-Pacific, Latin America, and Middle East & Africa, encompassing major players in surgical sealants, hemostats, tissue adhesives, bone graft substitutes, and wound closure matrices

• Product mapping across synthetic sealants (cyanoacrylates, polyethylene glycol polymers), biological sealants (fibrin, albumin-glutaraldehyde), mechanical hemostats (oxidized cellulose, gelatin sponges), flowable hemostats, bone graft substitutes (demineralized bone matrix, synthetic ceramics), and surgical adhesives

• Analysis of reported and modeled annual revenues specific to biosurgery portfolios, including surgical hemostasis, advanced wound closure, and regenerative tissue products

• Coverage of manufacturers representing 72-76% of global market share in 2024

• Extrapolation utilizing bottom-up (surgical procedure volume × average selling price by country/region across cardiac, orthopedic, spinal, and general surgical applications) and top-down (manufacturer revenue triangulation and supply chain validation) approaches to derive segment-specific valuations and regional market shares

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















