Biophotonics Market (2026 - 2035)

ID: MRFR/HC/10030-HCR 128 Pages Vikita Thakur Last Updated: September 28, 2026
Biophotonics Market Research Report Information By Application (Microscopy, See-through Imaging, Light Therapy, Biosensors, Inside Imaging, and Surface Imaging (endoscopy) and Others), By Technology (In-vivo and In-vitro), By End-Use (Medical Therapeutics, Medical Diagnostics, and Others) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) –Market Forecast Till 2035
Biophotonics Market
Market Size
Forecast Period2026-2035
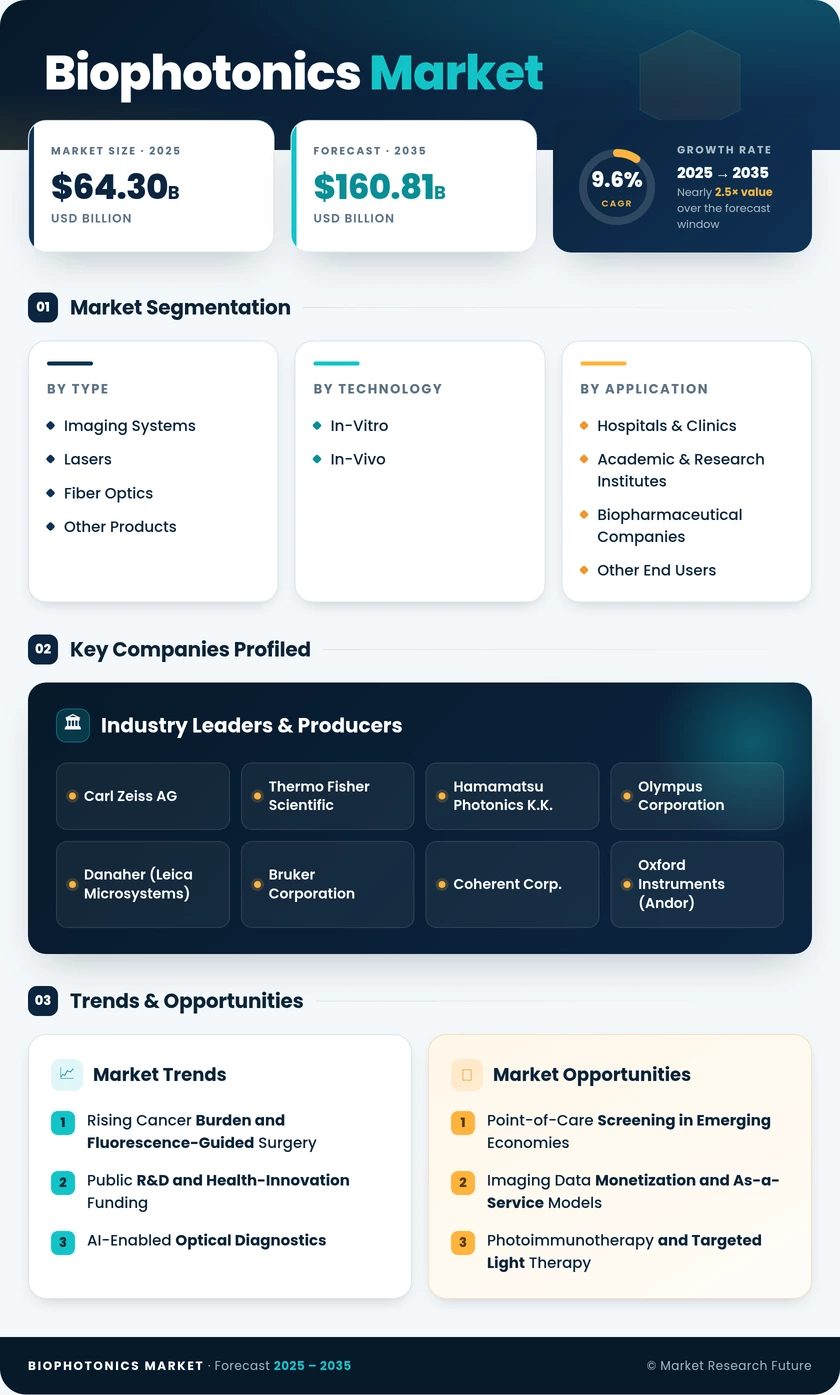
CAGR (2026-2035)9.6%
2025 Market SizeUSD 64.30 Billion
2035 Market SizeUSD 160.81 Billion
Key Players
Carl Zeiss AG
Thermo Fisher Scientific
Hamamatsu Photonics K.K.
Olympus Corporation
Danaher
Bruker Corporation
Opportunities
  • Point-of-Care Screening in Emerging Economies
  • Imaging Data Monetization and As-a-Service Models
  • Photoimmunotherapy and Targeted Light Therapy
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Product Type | |
    2. 2.2 By Technology | |
    3. 2.3 By Application | |
    4. 2.4 By Usage | |
    5. 2.5 By End-User | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Rising Cancer Burden and Fluorescence-Guided Surgery | |
    2. 4.2 Public R&D and Health-Innovation Funding | |
    3. 4.3 AI-Enabled Optical Diagnostics | |
    4. 4.4 Aging Populations and Minimally Invasive Care | |
    5. 4.5 Wearable and Point-of-Care Biosensing | |
    6. 4.6 Asia-Pacific Capacity Programs | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 High System Acquisition and Ownership Costs | |
    2. 5.2 Regulatory Complexity Under EU MDR | |
    3. 5.3 Critical Material Supply Constraints | |
    4. 5.4 Reimbursement Gaps for Novel Optical Procedures | |
    5. 5.5 Shortage of Photonics-Skilled Workforce | |
  6. 6 Opportunities | |
    1. 6.1 Point-of-Care Screening in Emerging Economies | |
    2. 6.2 Imaging Data Monetization and As-a-Service Models | |
    3. 6.3 Photoimmunotherapy and Targeted Light Therapy | |
    4. 6.4 Food Authentication and Environmental Testing | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 India | | |
      4. 7.3.4 Australia | | |
      5. 7.3.5 South Korea | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 GCC | | |
      2. 7.5.2 South Africa | | |
      3. 7.5.3 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 AI-Native Optical Diagnostics | |
    2. 8.2 Continuous Monitoring on the Body | |
    3. 8.3 Integrated and Quantum Photonics | |
    4. 8.4 Sustainability and Supply-Chain Resilience | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Product Type | | |
      1. 9.1.1 Imaging Systems | | |
      2. 9.1.2 Lasers | | |
      3. 9.1.3 Fiber Optics | | |
      4. 9.1.4 Other Products | |
    2. 9.2 By Technology | | |
      1. 9.2.1 In-Vitro | | |
      2. 9.2.2 In-Vivo | |
    3. 9.3 By Application | | |
      1. 9.3.1 Surface Imaging | | |
      2. 9.3.2 Inside Imaging | | |
      3. 9.3.3 See-Through Imaging | | |
      4. 9.3.4 Microscopy | | |
      5. 9.3.5 Light Therapy | | |
      6. 9.3.6 Biosensors | | |
      7. 9.3.7 Analytics Sensing | | |
      8. 9.3.8 Other Applications | |
    4. 9.4 By Usage | | |
      1. 9.4.1 Tests and Components | | |
      2. 9.4.2 Medical Therapeutics | | |
      3. 9.4.3 Medical Diagnostics | | |
      4. 9.4.4 Non-Medical Application | |
    5. 9.5 By End-User | | |
      1. 9.5.1 Hospitals & Clinics | | |
      2. 9.5.2 Academic & Research Institutes | | |
      3. 9.5.3 Biopharmaceutical Companies | | |
      4. 9.5.4 Other End Users | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Carl Zeiss AG | | |
      2. 10.3.2 Thermo Fisher Scientific | | |
      3. 10.3.3 Hamamatsu Photonics K.K. | | |
      4. 10.3.4 Olympus Corporation | | |
      5. 10.3.5 Danaher (Leica Microsystems) | | |
      6. 10.3.6 Becton, Dickinson and Company | | |
      7. 10.3.7 Bruker Corporation | | |
      8. 10.3.8 Coherent Corp. | | |
      9. 10.3.9 Oxford Instruments (Andor) | | |
      10. 10.3.10 Revvity | | |
      11. 10.3.11 IPG Photonics | | |
      12. 10.3.12 Zecotek Photonics | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Market Snapshot – Study Period, Market Size, CAGR, and Regional Leaders | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 North America Market, by Country, 2025 | |
  21. TABLE 7 Europe Market, by Country, 2025 | |
  22. TABLE 8 Asia-Pacific Market, by Country, 2025 | |
  23. TABLE 9 South America Market, by Country, 2025 | |
  24. TABLE 10 Middle East & Africa Market, by Country, 2025 | |
  25. TABLE 11 Global Market, by Product Type, 2025 | |
  26. TABLE 12 Global Market, by Technology, 2025 | |
  27. TABLE 13 Global Market, by Application, 2025 | |
  28. TABLE 14 Global Market, by Usage, 2025 | |
  29. TABLE 15 Global Market, by End-User, 2025 | |
  30. TABLE 16 Competitive Benchmarking Matrix, 2025 | |
  31. TABLE 17 Report Scope and Methodology | |
  32. TABLE 18 Detailed Sources and Citations | |
  33. TABLE 19 Segmentation Quick Reference | | LIST OF FIGURES | |
  34. FIGURE 1 Market Dynamics Overview – Drivers, Restraints, and Opportunities | |
  35. FIGURE 2 Industry Value Chain Analysis | |
  36. FIGURE 3 Porter's Five Forces Analysis | |
  37. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  38. FIGURE 5 Market Share, by Product Type, 2025 | |
  39. FIGURE 6 Market Share, by Technology, 2025 | |
  40. FIGURE 7 Market Share, by Application, 2025 | |
  41. FIGURE 8 Market Share, by Usage, 2025 | |
  42. FIGURE 9 Market Share, by End-User, 2025 | |
  43. FIGURE 10 Regional Market Share, 2025 | |
  44. FIGURE 11 Regional Growth Comparison, 2026–2035 | |
  45. FIGURE 12 Competitive Positioning Matrix | |
  46. FIGURE 13 Estimated Revenue Share Ranges of Key Players, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Product TypeImaging Systems, Lasers, Fiber Optics, Other ProductsLasers (33.6% share)Imaging Systems (10.5% CAGR)
By TechnologyIn-Vitro, In-VivoIn-Vitro (57.2% share)In-Vivo (9.9% CAGR)
By ApplicationSurface Imaging, Inside Imaging, See-Through Imaging, Microscopy, Light Therapy, Biosensors, Analytics Sensing, Other ApplicationsAnalytics Sensing (28.1% share)Biosensors (10.9% CAGR)
By UsageTests and Components, Medical Therapeutics, Medical Diagnostics, Non-Medical ApplicationMedical Diagnostics (51.8% share)Medical Therapeutics (10.1% CAGR)
By End-UserHospitals & Clinics, Academic & Research Institutes, Biopharmaceutical Companies, Other End UsersHospitals & Clinics (48.5% share)Academic & Research Institutes (11.0% CAGR)
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth America (38.4% share)Asia-Pacific (11.3% CAGR)


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
Imaging SystemsNear-infrared and hyperspectral cameras enter routine surgery
LasersBeam-quality gains support photoimmunotherapy protocols
Fiber OpticsMiniaturized probes power wearable and endoscopic sensing
Other ProductsQuantum and single-photon detectors reach commercial instruments


Lasers lead the product mix because photodynamic therapy, retinal surgery, and cytometry each depend on stable, wavelength-specific sources. Imaging Systems grow fastest as fluorescence-guided surgery approvals create reimbursable demand for intraoperative cameras. Fiber Optics ride the same miniaturization curve that is shrinking probes for endoscopy and wearables.

By Technology

Sub-SegmentKey Trend
In-VitroAutomated flow cytometry and fluorescence immunoassays scale
In-VivoReal-time optical guidance replaces tissue sampling


In-Vitro retains the larger base because clinical laboratories have standardized workflows, validated assays, and reimbursement built around specimen analysis. In-Vivo grows faster as photoacoustic imaging and optically guided biopsy let clinicians assess tissue without excision. Streamlined regulatory pathways for real-time devices further favor in-vivo adoption.

By Application

Sub-SegmentKey Trend
Surface ImagingDermatology imaging adopts AI-assisted lesion scoring
Inside ImagingOCT expands from ophthalmology into cardiology
See-Through ImagingShort-wave infrared aids deep-tissue visualization
MicroscopySuper-resolution tools break diffraction limits in live cells
Light TherapyPhotobiomodulation trials extend to neurological care
BiosensorsLow-cost polymer substrates enable point-of-care use
Analytics SensingRaman and fluorescence spectroscopy anchor lab chemistry
Other ApplicationsForensic and industrial inspection reuse clinical optics


Analytics Sensing leads because spectroscopic chemistry analysis is embedded across clinical, pharmaceutical, and industrial labs. Biosensors grow fastest as AI-assisted signal processing and surface-enhanced Raman assays push detection limits down while polymer substrates cut unit costs. Inside Imaging and Microscopy remain the core clinical and research categories supporting both trends.

By Usage

Sub-SegmentKey Trend
Tests and ComponentsStandardized optical modules shorten certification
Medical TherapeuticsTargeted light therapies gain oncology indications
Medical DiagnosticsPortable spectrometers extend screening to remote areas
Non-Medical ApplicationRaman authentication tackles food fraud


Medical Diagnostics dominate usage because screening, pathology, and point-of-care testing generate recurring procedure volumes. Medical Therapeutics grow fastest as photodynamic therapy and photoimmunotherapy win oncology approvals that lock in specific lasers and delivery fibers. Tests and Components supply the modules both depend on, while Non-Medical Application demand broadens the buyer base.

By End-User

Sub-SegmentKey Trend
Hospitals & ClinicsLeasing and per-procedure pricing ease capital hurdles
Academic & Research InstitutesNational photonics funds build core imaging facilities
Biopharmaceutical CompaniesHigh-content imaging supports AI-driven discovery
Other End UsersFood and environmental labs add optical testing


Hospitals & Clinics lead because structured capital procurement and clinical evidence requirements favor established optical platforms. Academic & Research Institutes grow fastest as Horizon Europe, NIH, and India's quantum mission fund new imaging cores and spin-offs. Biopharmaceutical Companies form a steady third pool through high-content screening in drug discovery.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.