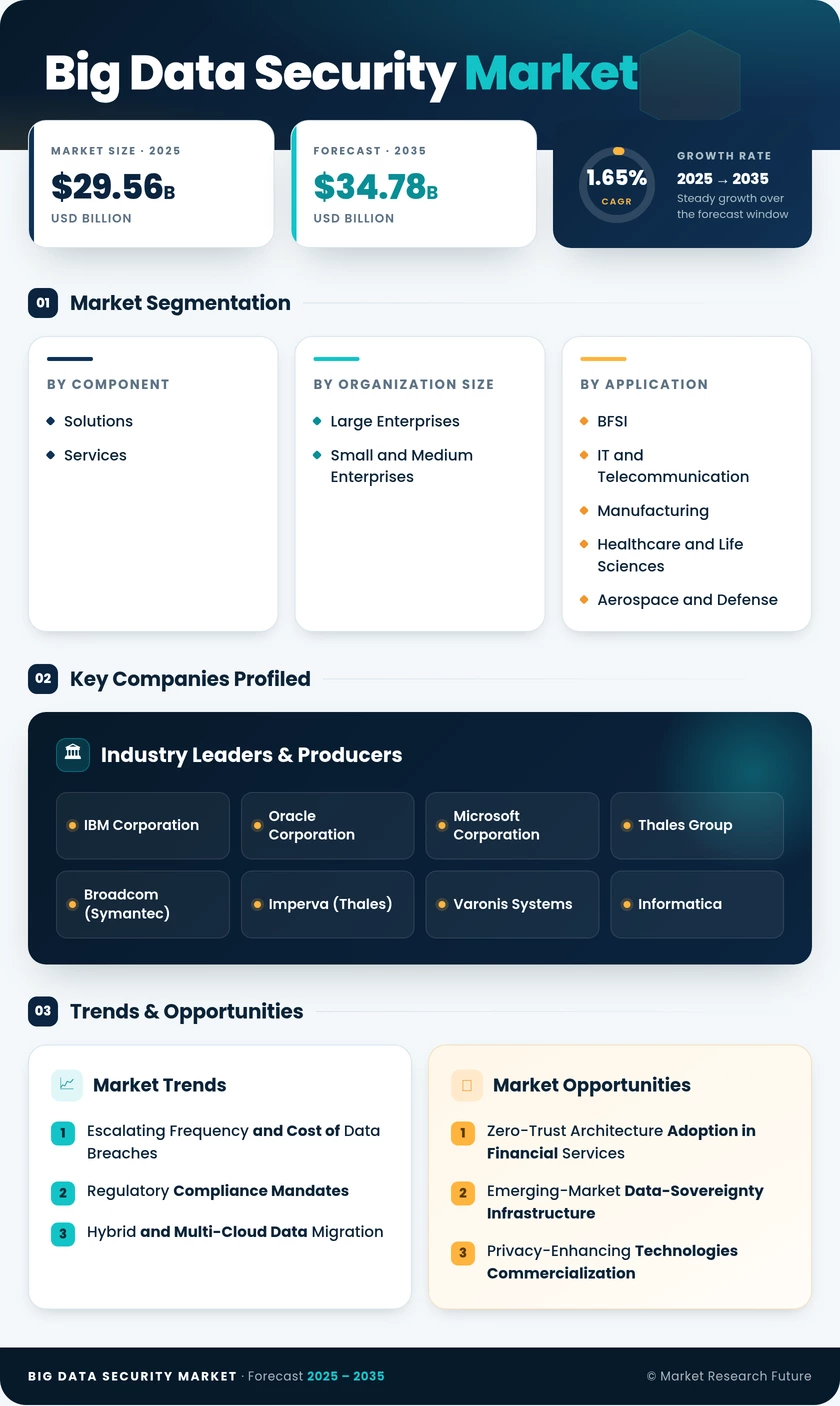
Big Data Security Market (2026 - 2035)

ID: MRFR/ICT/3001-CR 200 Pages Aarti Dhapte Last Updated: September 15, 2026
Big Data Security Market Size, Share and Research Report By Component (Software and Services), By Classification Method (Content-Based, Context-Based, User-Based, and Machine Learning–Driven), By Organization Size (Large Enterprises and Small and Medium Enterprises (SMEs)), By Application (Access Control and IAM, Governance and Compliance, Data Loss Prevention, and Threat Detection and Response), By Industry Vertical (BFSI, Healthcare and Life Sciences, Government and Defense, IT and Telecom, Retail and E-Commerce, Manufacturing, and Others), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
Big Data Security Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)1.65%
2025 Market SizeUSD 29.56 Billion
2026 Market SizeUSD 30.01 Billion
2035 Market SizeUSD 34.78 Billion
Key Players
IBM Corporation
Oracle Corporation
Microsoft Corporation
Thales Group
Broadcom
Imperva
Opportunities
  • Zero-Trust Architecture Adoption in Financial Services
  • Emerging-Market Data-Sovereignty Infrastructure
  • Privacy-Enhancing Technologies Commercialization
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Escalating Frequency and Cost of Data Breaches | |
      2. 3.1.2 Regulatory Compliance Mandates | |
      3. 3.1.3 Hybrid and Multi-Cloud Data Migration | |
      4. 3.1.4 AI and ML Integration in Threat Detection | |
      5. 3.1.5 Data-Sovereignty and Localization Requirements | |
      6. 3.1.6 Cybersecurity Workforce Shortage Driving Automation | |
      7. 3.1.7 IoT/OT Data Volume Growth in Manufacturing |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 High Implementation and Integration Costs | |
      2. 3.2.2 Cybersecurity Skills Shortage | |
      3. 3.2.3 Data Silos and Interoperability Challenges | |
      4. 3.2.4 Privacy-Security Trade-Off Tensions | |
      5. 3.2.5 Vendor Lock-In and Platform Fragmentation |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Zero-Trust Architecture Adoption in Financial Services | |
      2. 3.3.2 Emerging-Market Data-Sovereignty Infrastructure | |
      3. 3.3.3 Privacy-Enhancing Technologies Commercialization | |
      4. 3.3.4 Managed Security Services for Mid-Market Enterprises | |
      5. 3.3.5 Data Monetization Governance Platforms |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global Big Data Security Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Component | |
      1. 5.1.1 Solutions | |
      2. 5.1.2 Services |
    2. 5.2 By Organization Size | |
      1. 5.2.1 Large Enterprises | |
      2. 5.2.2 Small and Medium Enterprises |
    3. 5.3 By End-User Industry | |
      1. 5.3.1 Banking, Financial Services, and Insurance (BFSI) | |
      2. 5.3.2 IT and Telecommunication | |
      3. 5.3.3 Manufacturing | |
      4. 5.3.4 Healthcare and Life Sciences | |
      5. 5.3.5 Aerospace and Defense | |
      6. 5.3.6 Others |
    4. 5.4 By Deployment Mode | |
      1. 5.4.1 Cloud | |
      2. 5.4.2 On-Premise
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 IBM Corporation | |
      2. 7.3.2 Oracle Corporation | |
      3. 7.3.3 Microsoft Corporation | |
      4. 7.3.4 Thales Group | |
      5. 7.3.5 Broadcom (Symantec) | |
      6. 7.3.6 Imperva (Thales) | |
      7. 7.3.7 Varonis Systems | |
      8. 7.3.8 Informatica | |
      9. 7.3.9 Cloudera | |
      10. 7.3.10 Hewlett Packard Enterprise
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 AI-Native Security Operations |
    2. 8.2 Post-Quantum Cryptography Migration |
    3. 8.3 Data-Mesh and Federated Governance Architectures |
    4. 8.4 ESG and Sustainability Reporting Data Integrity
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global Big Data Security Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global Big Data Security Market — Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Market Driver Impact Analysis, 2026–2035 |
  16. TABLE 4 Market Restraint Impact Analysis, 2026–2035 |
  17. TABLE 5 Global Big Data Security Market Size, by Component, 2021–2035 (USD Billion) |
  18. TABLE 6 Global Big Data Security Market Size, by Organization Size, 2021–2035 (USD Billion) |
  19. TABLE 7 Global Big Data Security Market Size, by End-User Industry, 2021–2035 (USD Billion) |
  20. TABLE 8 Global Big Data Security Market Size, by Deployment Mode, 2021–2035 (USD Billion) |
  21. TABLE 9 Global Big Data Security Market Size, by Region, 2021–2035 (USD Billion) |
  22. TABLE 10 North America Big Data Security Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 11 Europe Big Data Security Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 12 Asia-Pacific Big Data Security Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 13 South America Big Data Security Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 14 Middle East & Africa Big Data Security Market Size, by Country, 2021–2035 (USD Billion) |
  27. TABLE 15 Competitive Benchmarking Matrix — Global Big Data Security Market, 2025 |
  28. TABLE 16 Company Profiles — Key Players, Global Big Data Security Market |
  29. TABLE 17 Recent Developments & Strategic Announcements, 2023–2025 |
  30. TABLE 18 North America Big Data Security Market Size, by Component, 2021–2035 (USD Billion) |
  31. TABLE 19 North America Big Data Security Market Size, by Organization Size, 2021–2035 (USD Billion) |
  32. TABLE 20 North America Big Data Security Market Size, by End-User Industry, 2021–2035 (USD Billion) |
  33. TABLE 21 North America Big Data Security Market Size, by Deployment Mode, 2021–2035 (USD Billion) |
  34. TABLE 22 Europe Big Data Security Market Size, by Component, 2021–2035 (USD Billion) |
  35. TABLE 23 Europe Big Data Security Market Size, by Organization Size, 2021–2035 (USD Billion) |
  36. TABLE 24 Europe Big Data Security Market Size, by End-User Industry, 2021–2035 (USD Billion) |
  37. TABLE 25 Europe Big Data Security Market Size, by Deployment Mode, 2021–2035 (USD Billion) |
  38. TABLE 26 Asia-Pacific Big Data Security Market Size, by Component, 2021–2035 (USD Billion) |
  39. TABLE 27 Asia-Pacific Big Data Security Market Size, by Organization Size, 2021–2035 (USD Billion) |
  40. TABLE 28 Asia-Pacific Big Data Security Market Size, by End-User Industry, 2021–2035 (USD Billion) |
  41. TABLE 29 Asia-Pacific Big Data Security Market Size, by Deployment Mode, 2021–2035 (USD Billion) |
  42. TABLE 30 South America Big Data Security Market Size, by Component, 2021–2035 (USD Billion) |
  43. TABLE 31 South America Big Data Security Market Size, by Organization Size, 2021–2035 (USD Billion) |
  44. TABLE 32 South America Big Data Security Market Size, by End-User Industry, 2021–2035 (USD Billion) |
  45. TABLE 33 South America Big Data Security Market Size, by Deployment Mode, 2021–2035 (USD Billion) |
  46. TABLE 34 Middle East & Africa Big Data Security Market Size, by Component, 2021–2035 (USD Billion) |
  47. TABLE 35 Middle East & Africa Big Data Security Market Size, by Organization Size, 2021–2035 (USD Billion) |
  48. TABLE 36 Middle East & Africa Big Data Security Market Size, by End-User Industry, 2021–2035 (USD Billion) |
  49. TABLE 37 Middle East & Africa Big Data Security Market Size, by Deployment Mode, 2021–2035 (USD Billion) |
  50. TABLE 38 Report Scope & Methodology Summary |
  51. TABLE 39 Detailed Sources and Citations
  52. 13 LIST OF FIGURES |
  53. FIGURE 1 Big Data Security Market Dynamics — Drivers, Restraints, and Opportunities |
  54. FIGURE 2 Value Chain Analysis — Global Big Data Security Market |
  55. FIGURE 3 Porter's Five Forces Analysis — Big Data Security Market |
  56. FIGURE 4 Global Big Data Security Market Size Trend & Forecast (USD Billion), 2021–2035 |
  57. FIGURE 5 Big Data Security Market Share, by Component, 2025 (%) |
  58. FIGURE 6 Big Data Security Market Share, by Organization Size, 2025 (%) |
  59. FIGURE 7 Big Data Security Market Share, by End-User Industry, 2025 (%) |
  60. FIGURE 8 Big Data Security Market Share, by Deployment Mode, 2025 (%) |
  61. FIGURE 9 Big Data Security Market Share, by Region, 2025 (%) |
  62. FIGURE 10 North America Big Data Security Market — Country Share, 2025 (%) |
  63. FIGURE 11 Europe Big Data Security Market — Country Share, 2025 (%) |
  64. FIGURE 12 Asia-Pacific Big Data Security Market — Country Share, 2025 (%) |
  65. FIGURE 13 South America Big Data Security Market — Country Share, 2025 (%) |
  66. FIGURE 14 Middle East & Africa Big Data Security Market — Country Share, 2025 (%) |
  67. FIGURE 15 Competitive Landscape — Market Share of Top 10 Players, 2025 (%) |
  68. FIGURE 16 Competitive Positioning Matrix — Big Data Security Market, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
ComponentSolutions, ServicesSolutionsServices
Organization SizeLarge Enterprises, Small and Medium EnterprisesLarge EnterprisesSmall and Medium Enterprises
End-User IndustryBFSI, IT and Telecommunication, Manufacturing, Healthcare and Life Sciences, Aerospace and Defense, OthersBFSIHealthcare and Life Sciences
Deployment ModeCloud, On-PremiseCloudCloud
GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
SolutionsPlatform consolidation — vendors bundling encryption, access control, masking, and audit into unified suites
ServicesRapid growth in managed detection and response (MDR) and advisory services for mid-market buyers


The Solutions segment captures the majority of revenue as enterprises seek to reduce vendor sprawl. Services is the growth engine, driven by organizations outsourcing specialized data-protection operations.

By Organization Size

Sub-SegmentKey Trend
Large EnterprisesBoard-level governance mandates and compliance-driven procurement cycles
Small and Medium EnterprisesAdoption of consumption-based, cloud-native security-as-a-service platforms


Large Enterprises anchor overall spending, while SMEs represent the fastest-growing buyer cohort enabled by lower-friction SaaS delivery.

By End-User Industry

Sub-SegmentKey Trend
BFSIRegulatory density (DORA, PCI-DSS, SOX) sustains the largest vertical share
IT and TelecommunicationHigh-throughput environments drive demand for scalable monitoring
ManufacturingOT/IT convergence and supply-chain data risks expand the addressable market
Healthcare and Life SciencesEHR digitization and genomic data growth create the fastest vertical growth
Aerospace and DefenseClassified data handling and ITAR compliance mandate specialized solutions
OthersEducation, retail, and government verticals contributing incremental demand


BFSI remains the anchor vertical, while Healthcare and Life Sciences offers the strongest growth trajectory through 2035.

By Deployment Mode

Sub-SegmentKey Trend
CloudMulti-cloud migration driving demand for cross-environment policy orchestration
On-PremisePersistent demand from defense, government, and data-sovereign environments


Cloud deployment dominates and continues to gain share, while On-Premise retains a stable base in highly regulated sectors.

By Geography

Sub-SegmentKey Trend
North AmericaMature compliance landscape and federal zero-trust mandates
EuropeGDPR/NIS2 enforcement expansion broadening the buyer base
Asia-PacificData-sovereignty laws and record data-center investment driving fastest growth
South AmericaLGPD enforcement and open-banking mandates
Middle East & AfricaNational digital-transformation strategies and smart-city programs


North America leads in absolute size, while Asia-Pacific delivers the highest growth rate underpinned by regulatory and infrastructure catalysts.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.