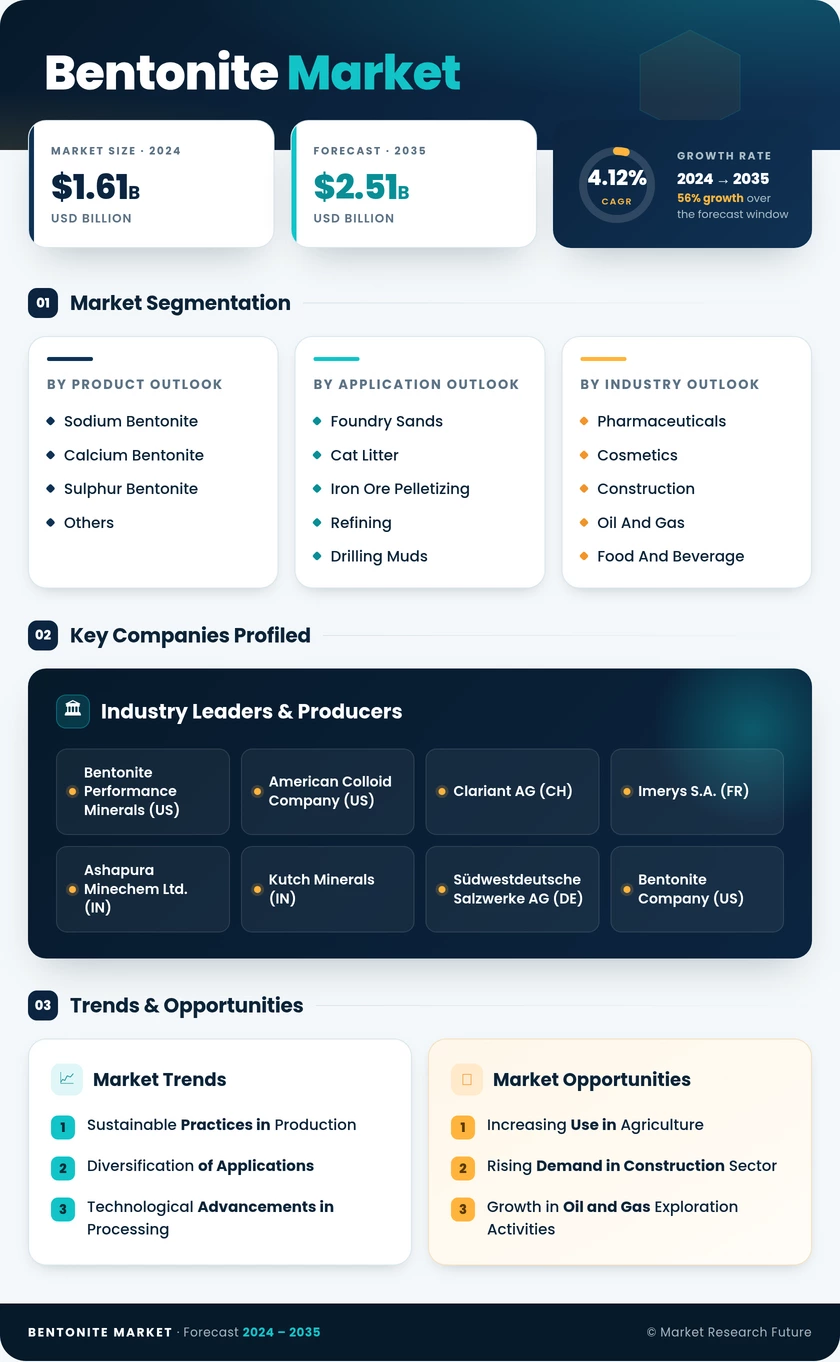
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product | Sodium Bentonite; Calcium Bentonite; Organically Modified Grades; Other Grades | Sodium Bentonite | Calcium Bentonite |
| By Application | Drilling Muds; Foundry Casting; Iron Ore Pelletizing; Civil Engineering; Absorbents; Other Applications | Drilling Muds | Civil Engineering |
| By End-Use Industry | Construction; Oil & Gas; Metallurgy & Foundry; Agriculture & Animal Feed; Water & Wastewater Treatment; Pharmaceuticals & Personal Care; Other Industries | Construction | Water & Wastewater Treatment |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Product
| Sub-Segment | Key Trend |
| Sodium-Grade Bentonite | Retains specification lock-in in pelletizing and API drilling due to superior swelling index and yield |
| Calcium Bentonite | Expanding through edible-oil bleaching capacity in Southeast Asia and activation into synthetic equivalents |
| Organically Modified Grades | Highest realized pricing; growth tied to non-aqueous coatings, greases, and specialty rheology systems |
| Other Grades | Niche demand in ceramics, agricultural carriers, and animal feed binders with stable low growth |
Product chemistry determines which applications a deposit can serve, and that constraint is geological rather than commercial. High-swell natural material remains concentrated in a small number of basins, which is why reserve ownership continues to command a valuation premium even as processing value migrates downstream toward engineered grades.
By Application
| Sub-Segment | Key Trend |
| Drilling Muds | Largest but most cyclical block; tied to global rig counts and lateral length trends |
| Foundry Casting | Green sand molding demand stabilized by EV structural castings offsetting engine-block decline |
| Iron Ore Pelletizing | Binder chemistry under reformulation pressure from direct-reduced iron silica limits |
| Civil Engineering | Fastest-expanding application on metro tunneling, slurry walls, and containment liners |
| Absorbents | Recession-resistant household demand with consistent margin performance |
| Other Applications | Pharmaceutical, cosmetic, and agricultural uses growing from a small premium base |
Application mix explains most of the difference between producer profitability profiles. Suppliers weighted toward drilling capture upside in strong energy cycles but suffer sharp volume swings, while those with meaningful absorbent and civil engineering exposure post steadier earnings across the cycle.
By End-Use Industry
| Sub-Segment | Key Trend |
| Construction | Now the leading end-use industry on the strength of global infrastructure pipelines |
| Oil & Gas | Demand concentrated in North America and the Gulf; sensitive to national oil company capital plans |
| Metallurgy & Foundry | Combined casting and pelletizing demand provides industrial ballast to overall volumes |
| Agriculture & Animal Feed | Steady growth from feed binder specification and soil amendment programs |
| Water & Wastewater Treatment | Regulation-driven expansion under tightening discharge and nutrient-removal rules |
| Pharmaceuticals & Personal Care | Certification-limited supply supports premium pricing and low competitive intensity |
| Other Industries | Detergents, paper, ceramics, and wine clarification form a diversified residual block |
End-use concentration has shifted materially over the past decade as construction displaced energy at the top of the table. That rotation favors suppliers positioned near infrastructure clusters and those able to document performance under civil-engineering specification regimes rather than oilfield standards alone.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA