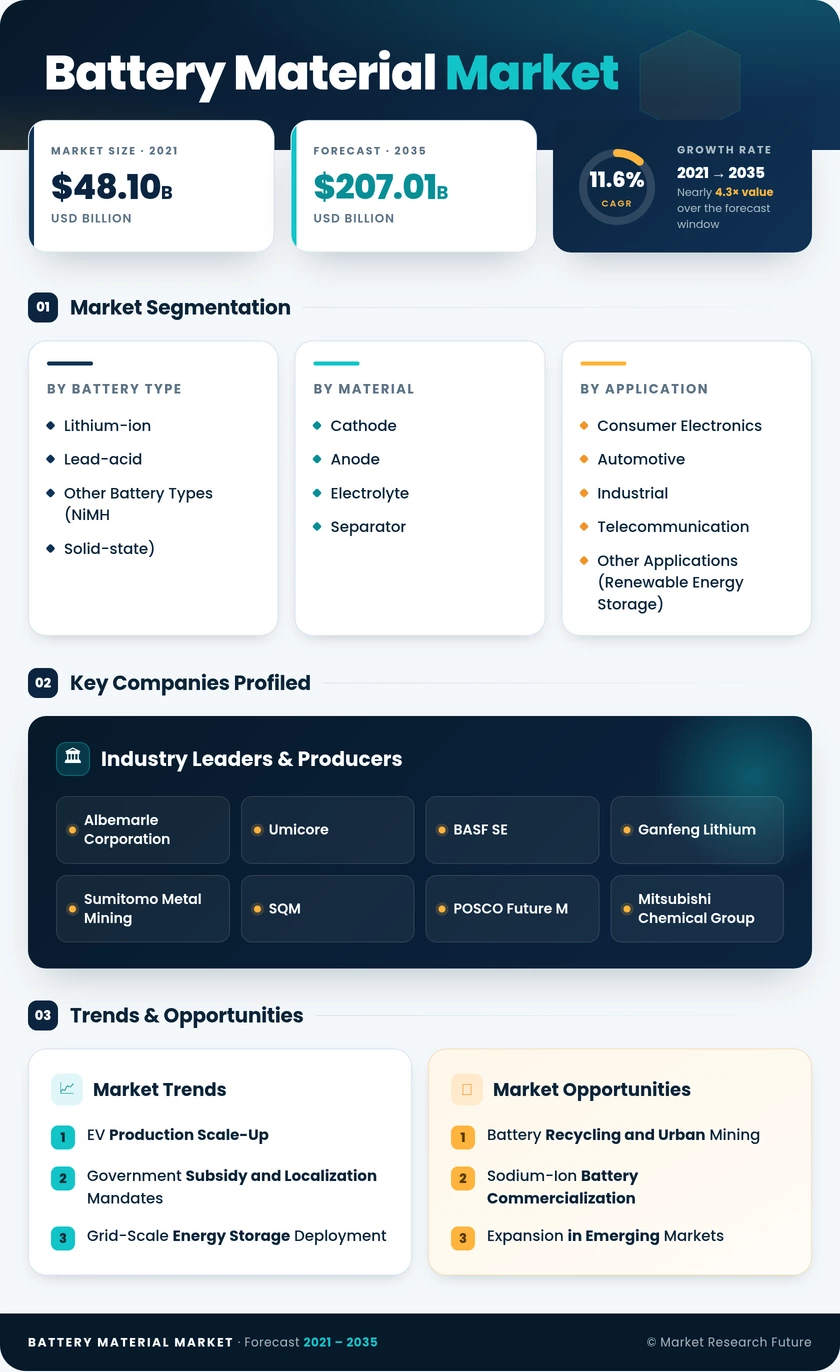
Battery Material Market (2026 - 2035)

ID: MRFR/CnM/0989-HCR 111 Pages Chitranshi Jaiswal Last Updated: September 18, 2026
Battery Materials Market Research Report Information By Type (Cathode, Anode, Electrolyte, Separator and Others), By Battery Type (Lithium-Ion, Lead-Acid, Nickel Metal Hydride (NiMH), Nickel Cadmium (Ni-Cd) and Others), By Application (Portable Devices, Automotive, Electronics Items, Power Storages and Others), and By Region (Asia-Pacific, North America, Europe, And Rest Of The World) –Market Predictions Till 2032
Battery Material Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.6%
2025 Market SizeUSD 69.10 Billion
2035 Market SizeUSD 207.01 Billion
Key Players
Albemarle Corporation
Umicore
BASF SE
Ganfeng Lithium
Sumitomo Metal Mining
SQM
Opportunities
  • Battery Recycling and Urban Mining
  • Sodium-Ion Battery Commercialization
  • Expansion in Emerging Markets
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 EV Production Scale-Up | |
      2. 3.1.2 Government Subsidy and Localization Mandates | |
      3. 3.1.3 Grid-Scale Energy Storage Deployment | |
      4. 3.1.4 Consumer Electronics Battery Demand | |
      5. 3.1.5 Recycling and Circular-Economy Mandates | |
      6. 3.1.6 Sodium-Ion and Solid-State R&D | |
      7. 3.1.7 Critical Mineral Strategic Stockpiling |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 Battery Storage and Transport Safety Regulations | |
      2. 3.2.2 Raw Material Price Volatility | |
      3. 3.2.3 Geopolitical Concentration of Refining Capacity | |
      4. 3.2.4 Environmental Permitting Delays for Mining | |
      5. 3.2.5 Competition from Alternative Chemistries Reducing Legacy Demand |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Battery Recycling and Urban Mining | |
      2. 3.3.2 Sodium-Ion Battery Commercialization | |
      3. 3.3.3 Expansion in Emerging Markets | |
      4. 3.3.4 Data-Driven Material Qualification Platforms | |
      5. 3.3.5 Solid-State Battery Material Supply Chains |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global Battery Materials Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Battery Type | |
      1. 5.1.1 Lithium-ion | |
      2. 5.1.2 Lead-acid | |
      3. 5.1.3 Other Battery Types (Nickel-Metal Hydride (NiMH), and Solid-State Batteries) |
    2. 5.2 By Material | |
      1. 5.2.1 Cathode | |
      2. 5.2.2 Anode | |
      3. 5.2.3 Electrolyte | |
      4. 5.2.4 Separator |
    3. 5.3 By Application | |
      1. 5.3.1 Consumer Electronics | |
      2. 5.3.2 Automotive | |
      3. 5.3.3 Industrial | |
      4. 5.3.4 Telecommunication | |
      5. 5.3.5 Other Applications (Renewable Energy Storage)
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Albemarle Corporation | |
      2. 7.3.2 Umicore | |
      3. 7.3.3 BASF SE | |
      4. 7.3.4 Ganfeng Lithium | |
      5. 7.3.5 Sumitomo Metal Mining | |
      6. 7.3.6 SQM | |
      7. 7.3.7 POSCO Future M | |
      8. 7.3.8 Mitsubishi Chemical Group | |
      9. 7.3.9 Targray Technology International | |
      10. 7.3.10 Johnson Matthey | |
      11. 7.3.11 Tianqi Lithium
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 The Electrification Supercycle and Material Demand |
    2. 8.2 AI-Driven Materials Discovery and Process Optimization |
    3. 8.3 ESG and Sustainability Reporting Pressures |
    4. 8.4 Platform Economics and Tolling Models
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global Battery Materials Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global Battery Materials Market — Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Global Battery Materials Market — Driver Impact Analysis |
  16. TABLE 4 Global Battery Materials Market — Restraint Impact Analysis |
  17. TABLE 5 Global Battery Materials Market Size, by Battery Type, 2021–2035 (USD Billion) |
  18. TABLE 6 Global Battery Materials Market Size, by Material, 2021–2035 (USD Billion) |
  19. TABLE 7 Global Battery Materials Market Size, by Application, 2021–2035 (USD Billion) |
  20. TABLE 8 Global Battery Materials Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 9 North America Battery Materials Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 10 Europe Battery Materials Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 11 Asia-Pacific Battery Materials Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 12 South America Battery Materials Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 13 Middle East & Africa Battery Materials Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 14 North America Battery Materials Market Size, by Battery Type, 2021–2035 (USD Billion) |
  27. TABLE 15 North America Battery Materials Market Size, by Material, 2021–2035 (USD Billion) |
  28. TABLE 16 North America Battery Materials Market Size, by Application, 2021–2035 (USD Billion) |
  29. TABLE 17 Europe Battery Materials Market Size, by Battery Type, 2021–2035 (USD Billion) |
  30. TABLE 18 Europe Battery Materials Market Size, by Material, 2021–2035 (USD Billion) |
  31. TABLE 19 Europe Battery Materials Market Size, by Application, 2021–2035 (USD Billion) |
  32. TABLE 20 Asia-Pacific Battery Materials Market Size, by Battery Type, 2021–2035 (USD Billion) |
  33. TABLE 21 Asia-Pacific Battery Materials Market Size, by Material, 2021–2035 (USD Billion) |
  34. TABLE 22 Asia-Pacific Battery Materials Market Size, by Application, 2021–2035 (USD Billion) |
  35. TABLE 23 South America Battery Materials Market Size, by Battery Type, 2021–2035 (USD Billion) |
  36. TABLE 24 South America Battery Materials Market Size, by Material, 2021–2035 (USD Billion) |
  37. TABLE 25 South America Battery Materials Market Size, by Application, 2021–2035 (USD Billion) |
  38. TABLE 26 Middle East & Africa Battery Materials Market Size, by Battery Type, 2021–2035 (USD Billion) |
  39. TABLE 27 Middle East & Africa Battery Materials Market Size, by Material, 2021–2035 (USD Billion) |
  40. TABLE 28 Middle East & Africa Battery Materials Market Size, by Application, 2021–2035 (USD Billion) |
  41. TABLE 29 Competitive Benchmarking Matrix — Global Battery Materials Market, 2025 |
  42. TABLE 30 Company Profiles — Key Players, Global Battery Materials Market |
  43. TABLE 31 Recent Developments & Strategic Announcements, 2023–2025 |
  44. TABLE 32 Report Scope & Methodology Summary |
  45. TABLE 33 Detailed Sources and Citations
  46. 13 LIST OF FIGURES |
  47. FIGURE 1 Battery Materials Market Dynamics — Drivers, Restraints, and Opportunities |
  48. FIGURE 2 Battery Materials Market — Industry Value Chain Analysis |
  49. FIGURE 3 Battery Materials Market — Porter's Five Forces Analysis |
  50. FIGURE 4 Global Battery Materials Market Size Trend & Forecast (USD Billion), 2021–2035 |
  51. FIGURE 5 Battery Materials Market Share, by Battery Type (%), 2025 |
  52. FIGURE 6 Battery Materials Market Share, by Material (%), 2025 |
  53. FIGURE 7 Battery Materials Market Share, by Application (%), 2025 |
  54. FIGURE 8 Battery Materials Market Share, by Region (%), 2025 |
  55. FIGURE 9 North America Battery Materials Market Size, by Country (USD Billion), 2025 vs 2035 |
  56. FIGURE 10 Europe Battery Materials Market Size, by Country (USD Billion), 2025 vs 2035 |
  57. FIGURE 11 Asia-Pacific Battery Materials Market Size, by Country (USD Billion), 2025 vs 2035 |
  58. FIGURE 12 South America Battery Materials Market Size, by Country (USD Billion), 2025 vs 2035 |
  59. FIGURE 13 Middle East & Africa Battery Materials Market Size, by Country (USD Billion), 2025 vs 2035 |
  60. FIGURE 14 Competitive Landscape — Market Share Heat Map, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Battery TypeLithium-ion; Lead-acid; Other Battery Types (NiMH, Solid-state)Lithium-ionOther Battery Types (Solid-state)
By MaterialCathode; Anode; Electrolyte; SeparatorCathodeAnode
By ApplicationConsumer Electronics; Automotive; Industrial; Telecommunication; Other Applications (Renewable Energy Storage)AutomotiveOther Applications (Renewable Energy Storage)
By GeographyAsia-Pacific; North America; Europe; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Battery Type

Sub-SegmentKey Trend
Lithium-ionDominant chemistry driven by EV and grid storage adoption; shift toward high-nickel and LFP variants.
Lead-acidMature segment sustained by telecom backup and industrial UPS; gradual share erosion to Li-ion
Other Battery Types (NiMH, Solid-state)NiMH declining in hybrid vehicles; solid-state approaching pilot production for premium EVs


Lithium-ion batteries represent the core demand engine for the Battery Materials Market, consuming the majority of processed cathode, anode, electrolyte, and separator materials globally. Lead-acid retains relevance in cost-sensitive stationary applications, while solid-state batteries are expected to enter limited commercial production between 2027 and 2029, creating new material demand categories for sulfide and oxide solid electrolytes.

By Material

Sub-SegmentKey Trend
CathodeLargest cost component; migration from NMC 532 to NMC 811 and LFP chemistries
AnodeFastest-growing material segment; silicon content increasing beyond 20% in advanced blends
ElectrolyteLiPF6 salt demand stable; advanced additives gaining share for performance and safety
SeparatorCeramic-coated polyethylene membranes expanding for thermal stability in high-energy cells


Cathode materials dominate material-level spend due to the high cost of nickel, cobalt, and lithium compounds. Anode innovation — particularly the integration of silicon into graphite composites — is the fastest-moving technical frontier, requiring new binder chemistries and pre-lithiation processes that expand the overall material addressable market.

By Application

Sub-SegmentKey Trend
AutomotiveLargest application; driven by BEV and PHEV production scaling across all major regions
Consumer ElectronicsStable demand from smartphones, laptops, and wearables; focus on compact, high-density cells
IndustrialGrowth linked to forklift electrification, warehouse automation, and backup power systems
Telecommunication5G tower backup batteries driving steady demand in developing markets
Other Applications (Renewable Energy Storage)Fastest-growing application; utility-scale and C&I storage mandates accelerating deployment


Automotive applications absorb the largest share of global battery material output, with EV production volumes expected to more than triple between 2025 and 2035. Renewable energy storage is emerging as the fastest-growing application, as declining levelized costs and generation-linked storage mandates drive GW-scale procurement cycles globally.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.