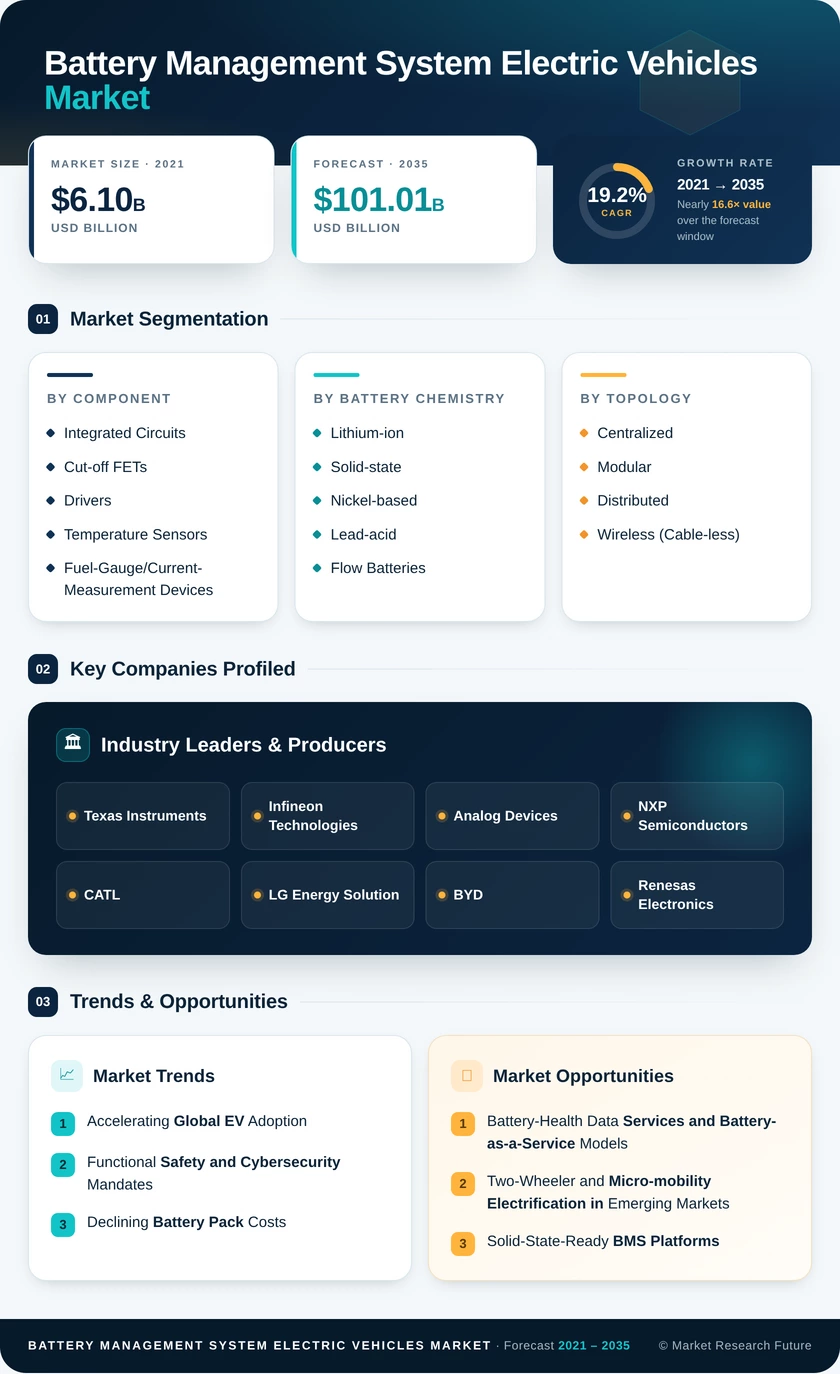
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|
| By Component | Integrated Circuits; Cut-off FETs and Drivers; Temperature Sensors; Fuel-Gauge/Current-Measurement Devices; Microcontrollers; Communication Interface ICs; Other Components | Integrated Circuits (38.2% share) | Communication Interface ICs (19.6% CAGR) |
| By Battery Chemistry | Lithium-ion; Solid-state; Nickel-based; Lead-acid; Flow Batteries | Lithium-ion (92.1% share) | Solid-state (22.6% CAGR) |
| By Topology | Centralized; Modular; Distributed; Wireless (Cable-less) | Modular (45.3% share) | Wireless (Cable-less) (22.9% CAGR) |
| By Communication Technology | Wired CAN; Wired Ethernet; Wireless RF | Wired CAN (67.4% share) | Wireless RF (23.5% CAGR) |
| By Propulsion Type | Battery Electric Vehicles (BEV); Hybrid Electric Vehicles (HEV); Plug-in Hybrid Vehicles (PHEV); Fuel-Cell Electric Vehicles (FCEV) | Battery Electric Vehicles (BEV) (72.6% share) | Fuel-Cell Electric Vehicles (FCEV) (19.9% CAGR) |
| By Vehicle Type | Passenger Cars; Light Commercial Vehicles; Medium and Heavy Commercial Vehicles; Two-Wheelers and Micro-mobility; Off-highway and Specialty Vehicles | Passenger Cars (65.8% share) | Two-Wheelers and Micro-mobility (23.2% CAGR) |
| By Sales Channel | OEM-fitted; Aftermarket/Retrofit | OEM-fitted (90.4% share) | Aftermarket/Retrofit (20.3% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East and Africa | Asia-Pacific (49.9% share) | Middle East and Africa (19.8% CAGR) |
Market Segmentation Overview
| Sub-Segment | Key Trend |
|---|
| Integrated Circuits | Single-die integration of measurement, balancing and diagnostics |
| Cut-off FETs and Drivers | Higher-voltage switching for 800 V packs |
| Temperature Sensors | Denser sensor placement for thermal runaway warning |
| Fuel-Gauge/Current-Measurement Devices | 24-bit converters improving charge accuracy |
| Microcontrollers | Lockstep cores for ASIL-D safety |
| Communication Interface ICs | Encrypted wireless and isolated daisy-chain links |
| Other Components | Isolation, connectors and passives scaling with pack size. |
Integrated Circuits lead because suppliers now place cell measurement, passive balancing and diagnostic logic on a single mixed-signal die, which cuts board area and simplifies safety certification. Communication Interface ICs grow fastest since every module in a modular or wireless pack needs its own transceiver, multiplying unit demand per vehicle. Fuel-Gauge/Current-Measurement Devices and Microcontrollers gain content as precision and redundancy requirements tighten.
| Sub-Segment | Key Trend |
|---|
| Lithium-ion | Shift from NMC to LFP in cost-sensitive vehicles |
| Solid-state | Pressure and interface-impedance sensing requirements |
| Nickel-based | Stable demand in hybrid vehicles |
| Lead-acid | Limited to 12 V auxiliary systems |
| Flow Batteries | Reuse of automotive control logic in stationary storage |
Lithium-ion leads on a mature cell supply base, though the move toward LFP forces BMS vendors to estimate charge on flatter voltage curves. Solid-state grows fastest from pilot volumes, demanding stack-pressure sensing that today's lithium-ion boards lack. Nickel-based and Lead-acid chemistries hold niche roles in hybrids and auxiliary circuits.
| Sub-Segment | Key Trend |
|---|
| Centralized | Lowest-cost option for small packs and micro-mobility |
| Modular | Board-per-module standardization across platforms |
| Distributed | Fault-tolerant designs for buses and trucks |
| Wireless (Cable-less) | Harness removal and automated pack assembly |
Modular topologies lead because one module controller can be reused across sedans, SUVs and vans, cutting engineering and tooling costs. Wireless (Cable-less) designs grow fastest by eliminating low-voltage harnesses and easing second-life reuse of modules. Centralized boards remain cost leaders for small packs, while distributed systems serve heavy vehicles needing graceful degradation.
| Sub-Segment | Key Trend |
|---|
| Wired CAN | Entrenched in existing validation toolchains |
| Wired Ethernet | High-bandwidth links to zonal controllers |
| Wireless RF | Encrypted 2.4 GHz mesh with self-healing routes |
Wired CAN leads because its deterministic timing satisfies most pack needs and plugs into established test equipment. Wireless RF grows fastest as encrypted mesh transceivers meet ISO/SAE 21434 expectations and harness savings justify the switch. Wired Ethernet expands where zonal architectures need full-resolution cell data for cloud analytics.
| Sub-Segment | Key Trend |
|---|
| Battery Electric Vehicles (BEV) | Larger packs and 800 V platforms |
| Hybrid Electric Vehicles (HEV) | High-volume, small-pack designs in Japan and Korea |
| Plug-in Hybrid Vehicles (PHEV) | Extended-range growth in China |
| Fuel-Cell Electric Vehicles (FCEV) | Buffer-battery management for hydrogen trucks |
Battery Electric Vehicles lead because their packs carry full traction load and the highest cell counts, maximizing BMS content. Fuel-Cell Electric Vehicles grow fastest from a small base as hydrogen truck corridors open, with buffer batteries requiring coordinated power management. Plug-in Hybrid Vehicles benefit from China's extended-range segment, and Hybrid Electric Vehicles deliver steady, lower-value volume.
| Sub-Segment | Key Trend |
|---|
| Passenger Cars | Mass-market EV penetration |
| Light Commercial Vehicles | Last-mile delivery fleet electrification |
| Medium and Heavy Commercial Vehicles | Large distributed packs under CO2 standards |
| Two-Wheelers and Micro-mobility | Low-cost boards and battery swapping |
| Off-highway and Specialty Vehicles | Rugged BMS for mining and construction |
Passenger Cars lead through sheer production scale across China, Europe and North America. Two-Wheelers and Micro-mobility grow fastest as India and Southeast Asia electrify scooters, with swapping networks adding BMS units per vehicle. Medium and Heavy Commercial Vehicles deliver the highest value per vehicle because their large packs need distributed monitoring.
| Sub-Segment | Key Trend |
|---|
| OEM-fitted | Factory certification tied to vehicle warranty |
| Aftermarket/Retrofit | Repowering, conversions and second-life recertification |
OEM-fitted systems lead because BMS hardware and firmware are homologated with the vehicle and bound to battery warranties. Aftermarket/Retrofit grows faster as early EV fleets leave warranty, conversion specialists repower vehicles and second-life integrators recertify modules for stationary storage.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA