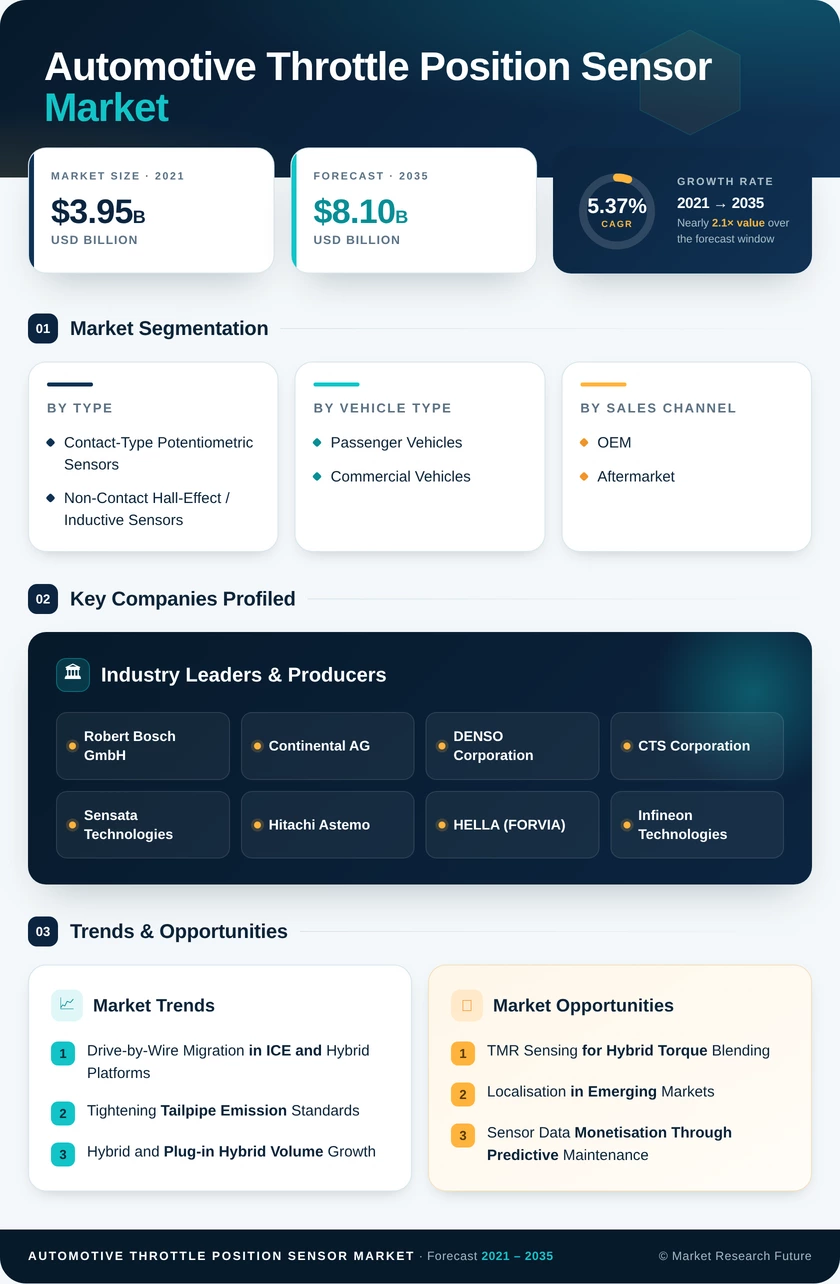
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Type | Contact-Type Potentiometric Sensors; Non-Contact Hall-Effect / Inductive Sensors | Contact-Type Potentiometric Sensors (53.2% share) | Non-Contact Hall-Effect / Inductive Sensors (5.42% CAGR) |
| By Vehicle Type | Passenger Vehicles; Commercial Vehicles | Passenger Vehicles (USD 3.31 Billion) | Commercial Vehicles (5.47% CAGR) |
| By Sales Channel | OEM; Aftermarket | OEM (64.1% share) | Aftermarket (5.49% CAGR) |
| By Output Type | Analog; Digital | Analog (60.6% share) | Digital (5.44% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific (44.9% share) | Middle East & Africa (5.46% CAGR) |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
|---|---|
| Contact-Type Potentiometric Sensors | Retained in cost-sensitive entry vehicles without redundancy mandates |
| Non-Contact Hall-Effect / Inductive Sensors | Replacing wiper-track designs to meet lifetime durability and ISO 26262 requirements |
Contact-Type Potentiometric Sensors still lead with a 53.2% share because their low unit cost suits entry-level vehicles in emerging markets. Non-Contact Hall-Effect / Inductive Sensors grow fastest at a 5.42% CAGR, since they have no wearing parts and support the dual-channel outputs that Euro 7 durability rules and functional-safety cases now favour.
By Vehicle Type
| Sub-Segment | Key Trend |
|---|---|
| Passenger Vehicles | Hybrid growth raises sensor content even as battery-electric share rises |
| Commercial Vehicles | Heavy-duty emission rules drive ruggedised dual-channel sensors |
Passenger Vehicles remain the largest pool at USD 3.31 Billion, supported by car production volume and the hybrid bridge in Asia-Pacific and Europe. Commercial Vehicles grow fastest at a 5.47% CAGR because heavy-duty engines face tighter monitoring under Euro 7 and fleets pay for sensors that survive vibration and thermal shock.
By Sales Channel
| Sub-Segment | Key Trend |
|---|---|
| OEM | Sensors ship integrated with throttle bodies and engine-specific calibration |
| Aftermarket | Ageing parcs and cheaper diagnostics accelerate replacement demand |
OEM supply leads with a 64.1% share because throttle-position sensors are validated and calibrated as part of the factory throttle body. The Aftermarket grows fastest at a 5.49% CAGR as potentiometric units installed in the 2010s wear out, although digital sensors that need dealer programming favour genuine replacement parts.
By Output Type
| Sub-Segment | Key Trend |
|---|---|
| Analog | Compatible with the large installed base of voltage-input controllers |
| Digital | SENT and PSI5 interfaces enable diagnostics and safety-rated redundancy |
Analog sensors hold a 60.6% share because most controllers in production still read ratiometric voltage signals. Digital sensors grow fastest at a 5.44% CAGR, as SENT and PSI5 provide the error detection and shared data access that ISO 26262 compliance and domain-controller architectures require.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA