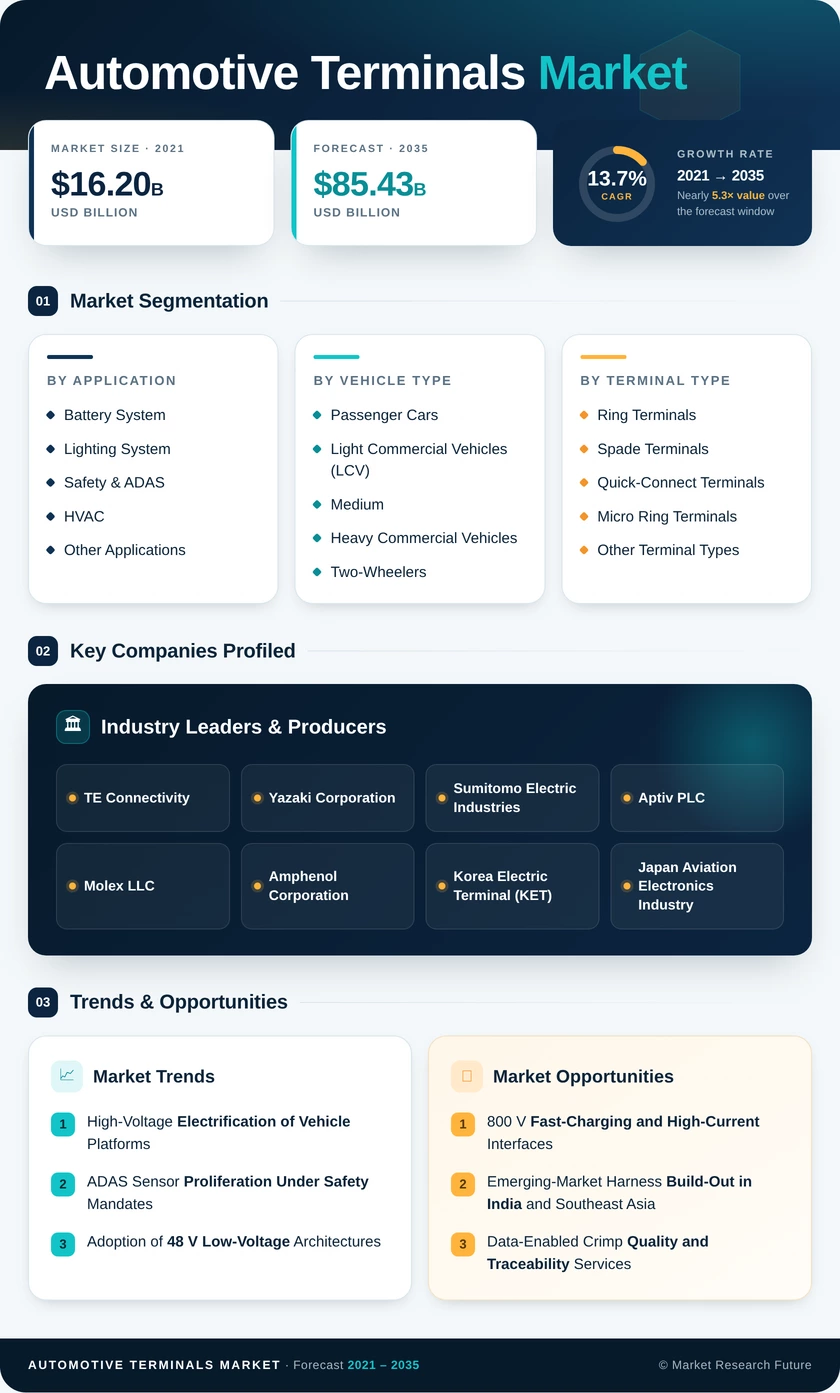
Automotive Terminals Market (2026 - 2035)

ID: MRFR/AT/4709-HCR 100 Pages Triveni Bhoyar Last Updated: November 02, 2026
Automotive Terminals Market Research Report By Application (Battery System, Lighting System, Safety & ADAS, HVAC, Other Applications), By Vehicle Type (Passenger Cars, Light Commercial Vehicles (LCV), Medium and Heavy Commercial Vehicles, Two-Wheelers), By Terminal Type (Ring Terminals, Spade Terminals, Quick-Connect Terminals, Micro Ring Terminals, Other Terminal Types), By Material (Copper, Brass, Aluminum, Other Alloys), By Current Rating (Less than 25 Amp, 25–50 Amp, More than 50 Amp), By Sales Channel (OEM, Aftermarket) - Forecast to 2035
Automotive Terminals Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.01%
2025 Market SizeUSD 30.39 Billion
2035 Market SizeUSD 45.02 Billion
Key Players
TE Connectivity
Yazaki Corporation
Sumitomo Electric Industries
Aptiv PLC
Molex LLC
Amphenol Corporation
Opportunities
  • 800 V Fast-Charging and High-Current Interfaces
  • Emerging-Market Harness Build-Out in India and Southeast Asia
  • Data-Enabled Crimp Quality and Traceability Services
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Application | |
    2. 2.2 By Vehicle Type | |
    3. 2.3 By Terminal Type | |
    4. 2.4 By Material | |
    5. 2.5 By Current Rating | |
    6. 2.6 By Sales Channel | |
    7. 2.7 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 High-Voltage Electrification of Vehicle Platforms | |
    2. 4.2 ADAS Sensor Proliferation Under Safety Mandates | |
    3. 4.3 Adoption of 48 V Low-Voltage Architectures | |
    4. 4.4 Zonal Architecture and Terminal Miniaturization | |
    5. 4.5 Light-Vehicle Production Recovery | |
    6. 4.6 Onshoring Incentives for Batteries and Harnesses | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Copper Price Volatility | |
    2. 5.2 Harness Simplification in Zonal Designs | |
    3. 5.3 Uneven EV Adoption and Subsidy Withdrawals | |
    4. 5.4 Qualification and Validation Costs | |
    5. 5.5 Counterfeit and Low-Grade Aftermarket Parts | |
  6. 6 Opportunities | |
    1. 6.1 800 V Fast-Charging and High-Current Interfaces | |
    2. 6.2 Emerging-Market Harness Build-Out in India and Southeast Asia | |
    3. 6.3 Data-Enabled Crimp Quality and Traceability Services | |
    4. 6.4 Micro-Terminals for Solid-State Batteries and BMS | |
    5. 6.5 Closed-Loop Copper and Lead-Free Alloys | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Rest of North America | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 France | | |
      3. 7.2.3 United Kingdom | | |
      4. 7.2.4 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 India | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 South Africa | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Software-Defined Vehicles and Zonal Consolidation | |
    2. 8.2 Electrification Supercycle | |
    3. 8.3 Automated Harness Production and AI Quality Control | |
    4. 8.4 Sustainability, Traceability and ESG Reporting | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Application | | |
      1. 9.1.1 Battery System | | |
      2. 9.1.2 Lighting System | | |
      3. 9.1.3 Safety & ADAS | | |
      4. 9.1.4 HVAC | | |
      5. 9.1.5 Other Applications | |
    2. 9.2 By Vehicle Type | | |
      1. 9.2.1 Passenger Cars | | |
      2. 9.2.2 Light Commercial Vehicles (LCV) | | |
      3. 9.2.3 Medium and Heavy Commercial Vehicles | | |
      4. 9.2.4 Two-Wheelers | |
    3. 9.3 By Terminal Type | | |
      1. 9.3.1 Ring Terminals | | |
      2. 9.3.2 Spade Terminals | | |
      3. 9.3.3 Quick-Connect Terminals | | |
      4. 9.3.4 Micro Ring Terminals | | |
      5. 9.3.5 Other Terminal Types | |
    4. 9.4 By Material | | |
      1. 9.4.1 Copper | | |
      2. 9.4.2 Brass | | |
      3. 9.4.3 Aluminum | | |
      4. 9.4.4 Other Alloys | |
    5. 9.5 By Current Rating | | |
      1. 9.5.1 Less than 25 Amp | | |
      2. 9.5.2 25–50 Amp | | |
      3. 9.5.3 More than 50 Amp | |
    6. 9.6 By Sales Channel | | |
      1. 9.6.1 OEM | | |
      2. 9.6.2 Aftermarket | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 TE Connectivity | | |
      2. 10.3.2 Yazaki Corporation | | |
      3. 10.3.3 Sumitomo Electric Industries | | |
      4. 10.3.4 Aptiv PLC | | |
      5. 10.3.5 Molex LLC | | |
      6. 10.3.6 Amphenol Corporation | | |
      7. 10.3.7 Korea Electric Terminal (KET) | | |
      8. 10.3.8 Japan Aviation Electronics Industry | | |
      9. 10.3.9 Furukawa Electric | | |
      10. 10.3.10 Hirose Electric | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Report Summary — Key Market Parameters | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis on CAGR | |
  18. TABLE 4 Restraints Impact Analysis on CAGR | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 North America Market, by Country | |
  21. TABLE 7 Europe Market, by Country | |
  22. TABLE 8 Asia-Pacific Market, by Country | |
  23. TABLE 9 South America Market, by Country | |
  24. TABLE 10 Middle East & Africa Market, by Country | |
  25. TABLE 11 Global Market, by Application | |
  26. TABLE 12 Global Market, by Vehicle Type | |
  27. TABLE 13 Global Market, by Terminal Type | |
  28. TABLE 14 Global Market, by Material | |
  29. TABLE 15 Global Market, by Current Rating | |
  30. TABLE 16 Global Market, by Sales Channel | |
  31. TABLE 17 Competitive Benchmarking Matrix | |
  32. TABLE 18 Report Scope and Methodology | |
  33. TABLE 19 Detailed Sources and Citations | |
  34. TABLE 20 Segmentation Quick Reference | | LIST OF FIGURES | |
  35. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities | |
  36. FIGURE 2 Industry Value Chain Analysis | |
  37. FIGURE 3 Porter's Five Forces Analysis | |
  38. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  39. FIGURE 5 Market Share by Application, 2025 | |
  40. FIGURE 6 Market Share by Vehicle Type, 2025 | |
  41. FIGURE 7 Market Share by Terminal Type, 2025 | |
  42. FIGURE 8 Market Share by Material, 2025 | |
  43. FIGURE 9 Market Share by Current Rating, 2025 | |
  44. FIGURE 10 Market Share by Sales Channel, 2025 | |
  45. FIGURE 11 Regional Market Share, 2025 | |
  46. FIGURE 12 Competitive Landscape — Estimated Revenue Share Ranges

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ApplicationBattery System, Lighting System, Safety & ADAS, HVAC, Other ApplicationsBattery System (30.6% share)Safety & ADAS (13.8% CAGR)
By Vehicle TypePassenger Cars, Light Commercial Vehicles (LCV), Medium and Heavy Commercial Vehicles, Two-WheelersPassenger Cars (14.3% CAGR)Passenger Cars (14.3% CAGR)
By Terminal TypeRing Terminals, Spade Terminals, Quick-Connect Terminals, Micro Ring Terminals, Other Terminal TypesRing Terminals (27.4% share)Micro Ring Terminals (14.2% CAGR)
By MaterialCopper, Brass, Aluminum, Other AlloysCopper (52.3% share)Other Alloys (14.8% CAGR)
By Current RatingLess than 25 Amp, 25–50 Amp, More than 50 AmpLess than 25 Amp (47.8% share)More than 50 Amp (14.1% CAGR)
By Sales ChannelOEM, AftermarketOEM (13.8% CAGR)OEM (13.8% CAGR)
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaAsia-Pacific (47.2% share)Asia-Pacific (47.2% share)


Market Segmentation Overview

By Application

Sub-SegmentKey Trend
Battery SystemRising pack voltages and cell-level sensing
Lighting SystemLED matrix and adaptive headlamps
Safety & ADASShielded sensor connections under safety mandates
HVACHeat pumps and 48 V brushless blowers
Other ApplicationsBody control and infotainment circuits


Battery System leads because each pack combines busbars, cell monitoring leads and thermal sensors in a single terminal-intensive assembly. Safety & ADAS grows fastest as GSR2 and the U.S. braking mandate multiply camera and radar modules per vehicle. HVAC gains relevance as heat pumps lift current draw in electric cars.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsRapid shift to battery electric lineups
Light Commercial Vehicles (LCV)Last-mile fleet electrification
Medium and Heavy Commercial VehiclesElectric trucks and megawatt charging
Two-WheelersSealed DC terminals for swappable batteries


Passenger Cars both lead and grow fastest, since CO₂ fleet targets concentrate electrification on high-volume car platforms. Light Commercial Vehicles (LCV) follow as parcel fleets electrify for low-emission zones, favoring high-cycle, vibration-resistant terminals. Two-Wheelers push standardization of sealed terminals for battery swapping in Asia.

By Terminal Type

Sub-SegmentKey Trend
Ring TerminalsGrounding and high-current battery lugs
Spade TerminalsSecondary locking for fuse and relay boxes
Quick-Connect TerminalsTool-free mating on automated lines
Micro Ring TerminalsFine-pitch board-to-cable interfaces
Other Terminal TypesSpecialty butt and pin contacts


Ring Terminals keep the largest share because grounding and battery lug connections demand their mechanical security. Micro Ring Terminals grow fastest as battery management and inverter boards shrink toward sub-0.5 mm pitch. Quick-Connect Terminals gain where automated harness lines prioritize cycle time over cost.

By Material

Sub-SegmentKey Trend
CopperHigh-current and fast-charging paths
BrassLead-free, RoHS-compliant alloys
AluminumWeight savings in large-gauge cables
Other AlloysHigh-fatigue grades for extreme conditions


Copper leads because resistive losses in high-current paths translate directly into heat and warranty risk. Other Alloys grow fastest as solid-state packs and high-temperature zones call for beryllium copper and similar grades. Brass stays competitive through lead-free formulations, while Aluminum serves weight-sensitive battery cables.

By Current Rating

Sub-SegmentKey Trend
Less than 25 AmpDense infotainment and body circuits
25–50 AmpPlug-in hybrid chargers and e-compressors
More than 50 Amp800 V drivetrains and fast charging


Less than 25 Amp terminals lead on circuit count across body electronics, lighting and infotainment. More than 50 Amp terminals grow fastest because 800 V drivetrains, battery disconnect units and megawatt truck chargers require blade and busbar designs with minimal temperature rise. The 25–50 Amp band remains anchored in plug-in hybrid chargers.

By Sales Channel

Sub-SegmentKey Trend
OEMHarness specifications locked in vehicle development
AftermarketProfessional installers and ADAS recalibration


OEM procurement leads and grows fastest because terminal specifications are fixed during platform development and supplied through PPAP-controlled flows. Aftermarket demand relies on professional installers, as high-voltage systems and multiplexed networks discourage do-it-yourself repair and favor certified replacement kits.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.