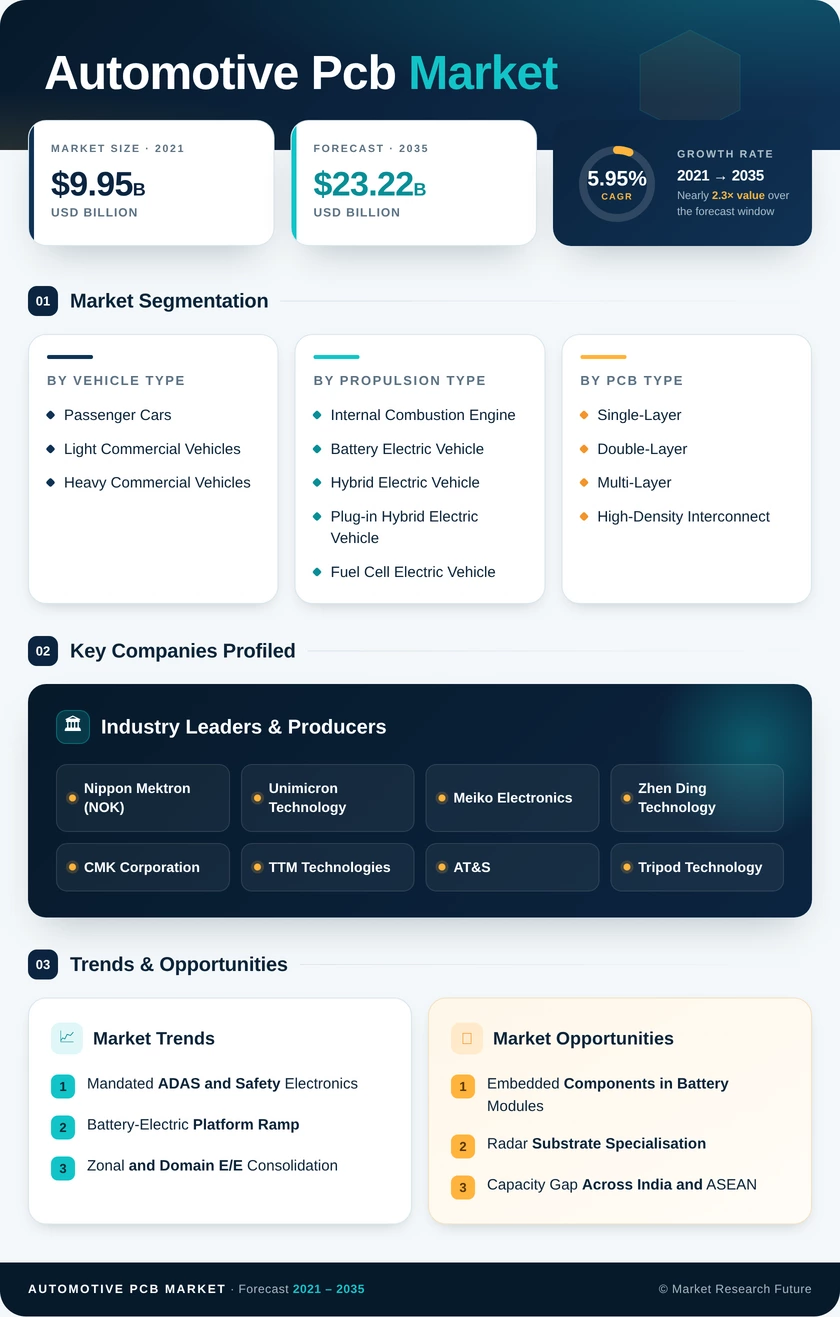
Automotive PCB Market (2026 - 2035)

ID: MRFR/AT/3976-CR 136 Pages Triveni Bhoyar Last Updated: September 15, 2026
Automotive PCB Market Research Report By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles), By Propulsion Type (Internal Combustion Engine, Battery Electric Vehicle, Hybrid Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle), By PCB Type (Single-Layer, Double-Layer, Multi-Layer, High-Density Interconnect), By Substrate (Rigid, Flexible, Rigid-Flex), By Application (ADAS & Safety Systems, Powertrain & Electrification, Infotainment & Connectivity, Body & Comfort Electronics, Autonomous Driving Compute), By Level of Automation (SAE Level 0–2, SAE Level, SAE Level 4–5) - Forecast to 2035
Automotive PCB Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.95%
2025 Market SizeUSD 13.08 Billion
2035 Market SizeUSD 23.22 Billion
Key Players
Nippon Mektron
Unimicron Technology
Meiko Electronics
Zhen Ding Technology
CMK Corporation
TTM Technologies
Opportunities
  • Embedded Components in Battery Modules
  • Radar Substrate Specialisation
  • Capacity Gap Across India and ASEAN
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Market Drivers Analysis | |
    1. 4.1 Mandated ADAS and Safety Electronics | |
    2. 4.2 Battery-Electric Platform Ramp | |
    3. 4.3 Zonal and Domain E/E Consolidation | |
    4. 4.4 48 V Power-Net Migration | |
    5. 4.5 Digital Cockpit and Connectivity Content | |
    6. 4.6 Silicon-Carbide Inverter Adoption | |
    7. 4.7 Regional Supply-Chain Localisation Policy | |
  5. 5 Market Restraints Analysis | |
    1. 5.1 Copper and Laminate Price Volatility | |
    2. 5.2 Qualification Cycle Length and Capex Intensity | |
    3. 5.3 Environmental Compliance and Effluent Limits | |
    4. 5.4 Skilled Process Labour Shortage | |
    5. 5.5 Board Count Reduction from Architecture Change | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Embedded Components in Battery Modules | |
    2. 6.2 Radar Substrate Specialisation | |
    3. 6.3 Capacity Gap Across India and ASEAN | |
    4. 6.4 Design Data and Digital Twin Monetisation | |
    5. 6.5 Low-Carbon Laminates and Recycled Copper | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Compute Centralisation and Autonomous Readiness | |
    2. 8.2 Electrification Supercycle and Voltage Escalation | |
    3. 8.3 Supply-Chain Regionalisation and Dual Sourcing | |
    4. 8.4 Circularity and Emissions Disclosure | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Vehicle Type | | |
      1. 9.1.1 Passenger Cars | | |
      2. 9.1.2 Light Commercial Vehicles | | |
      3. 9.1.3 Heavy Commercial Vehicles | |
    2. 9.2 By Propulsion Type | | |
      1. 9.2.1 Internal Combustion Engine | | |
      2. 9.2.2 Battery Electric Vehicle | | |
      3. 9.2.3 Hybrid Electric Vehicle | | |
      4. 9.2.4 Plug-in Hybrid Electric Vehicle | | |
      5. 9.2.5 Fuel Cell Electric Vehicle | |
    3. 9.3 By PCB Type | | |
      1. 9.3.1 Single-Layer | | |
      2. 9.3.2 Double-Layer | | |
      3. 9.3.3 Multi-Layer | | |
      4. 9.3.4 High-Density Interconnect | |
    4. 9.4 By Substrate | | |
      1. 9.4.1 Rigid | | |
      2. 9.4.2 Flexible | | |
      3. 9.4.3 Rigid-Flex | |
    5. 9.5 By Application | | |
      1. 9.5.1 ADAS & Safety Systems | | |
      2. 9.5.2 Powertrain & Electrification | | |
      3. 9.5.3 Infotainment & Connectivity | | |
      4. 9.5.4 Body & Comfort Electronics | | |
      5. 9.5.5 Autonomous Driving Compute | |
    6. 9.6 By Level of Automation | | |
      1. 9.6.1 SAE Level 0–2 | | |
      2. 9.6.2 SAE Level | | |
      3. 9.6.3 SAE Level 4–5 | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Nippon Mektron (NOK) | | |
      2. 10.3.2 Unimicron Technology | | |
      3. 10.3.3 Meiko Electronics | | |
      4. 10.3.4 Zhen Ding Technology | | |
      5. 10.3.5 CMK Corporation | | |
      6. 10.3.6 TTM Technologies | | |
      7. 10.3.7 AT&S | | |
      8. 10.3.8 Tripod Technology | | |
      9. 10.3.9 Chin Poon Industrial | | |
      10. 10.3.10 KCE Electronics | | |
      11. 10.3.11 Ibiden | | |
      12. 10.3.12 Daeduck Electronics | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Automotive PCB Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Automotive PCB Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Propulsion Type, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by PCB Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Market Size, by Substrate, 2021–2035 (USD Billion) | |
  29. TABLE 15 Global Market Size, by Application, 2021–2035 (USD Billion) | |
  30. TABLE 16 Global Market Size, by Level of Automation, 2021–2035 (USD Billion) | |
  31. TABLE 17 Competitive Benchmarking Matrix, 2026 | |
  32. TABLE 18 Company Profiles – Key Players | |
  33. TABLE 19 Recent Developments & Strategic Announcements, 2023–2025 | |
  34. TABLE 20 Report Scope & Methodology Summary | |
  35. TABLE 21 Detailed Sources and Citations Index | |
  36. TABLE 22 North America Market Size, by Application, 2021–2035 (USD Billion) | |
  37. TABLE 23 Europe Market Size, by Substrate, 2021–2035 (USD Billion) | |
  38. TABLE 24 Asia-Pacific Market Size, by PCB Type, 2021–2035 (USD Billion) | | LIST OF FIGURES | |
  39. FIGURE 1 Market Dynamics – Drivers, Restraints, and Opportunities | |
  40. FIGURE 2 Industry Value Chain Analysis | |
  41. FIGURE 3 Porter's Five Forces Analysis | |
  42. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  43. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 (%) | |
  44. FIGURE 6 Market Share by Vehicle Type, 2025 vs 2035 (%) | |
  45. FIGURE 7 Market Share by Propulsion Type, 2025 vs 2035 (%) | |
  46. FIGURE 8 Market Share by PCB Type, 2025 (%) | |
  47. FIGURE 9 Market Share by Substrate, 2025 (%) | |
  48. FIGURE 10 Market Share by Application, 2025 (%) | |
  49. FIGURE 11 Market Share by Level of Automation, 2025 (%) | |
  50. FIGURE 12 Regional Revenue Share, 2025 (%) | |
  51. FIGURE 13 Regional CAGR Comparison, 2026–2035 (%) | |
  52. FIGURE 14 Asia-Pacific Country-Level Revenue Split, 2025 (%) | |
  53. FIGURE 15 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  54. FIGURE 16 Competitive Positioning Matrix – Process Capability vs Scale

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Vehicle TypePassenger Cars; Light Commercial Vehicles; Heavy Commercial VehiclesPassenger CarsPassenger Cars
By Propulsion TypeInternal Combustion Engine; Battery Electric Vehicle; Hybrid Electric Vehicle; Plug-in Hybrid Electric Vehicle; Fuel Cell Electric VehicleInternal Combustion EngineBattery Electric Vehicle
By PCB TypeSingle-Layer; Double-Layer; Multi-Layer; High-Density InterconnectSingle-LayerHigh-Density Interconnect
By SubstrateRigid; Flexible; Rigid-FlexRigidRigid-Flex
By ApplicationADAS & Safety Systems; Powertrain & Electrification; Infotainment & Connectivity; Body & Comfort Electronics; Autonomous Driving ComputeADAS & Safety SystemsAutonomous Driving Compute
By Level of AutomationSAE Level 0–2; SAE Level 3; SAE Level 4–5SAE Level 0–2SAE Level 4–5
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

Segmentation across the Automotive PCB Market is structured around seven dimensions, each mapped to distinct demand mechanics and supplier capability requirements.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsContent escalation in cockpit and driver assistance outpaces unit volume growth.
Light Commercial VehiclesUrban delivery fleet electrification adds battery and charging, boards.
Heavy Commercial VehiclesTelematics mandates and long service lives sustain aftermarket demand.


Vehicle class determines both board volume and specification depth. Passenger platforms carry the widest electronics content range, from entry trims with minimal assistance features to flagship models running centralised compute. Commercial platforms move more slowly but reward suppliers who can support extended production and service windows.

By Propulsion Type

Sub-SegmentKey Trend
Internal Combustion EngineEmissions aftertreatment control sustains multilayer board demand
Battery Electric VehicleTraction inverter and pack sensing content drives highest value per unit.
Hybrid Electric VehicleDual-powertrain supervision maximises board count per vehicle.
Plug-in Hybrid Electric VehicleCharging hardware layered onto combustion control electronics.
Fuel Cell Electric VehicleStack control and hydrogen sensing in commercial demonstration fleets


Propulsion architecture is the strongest single predictor of board value per vehicle. Electrified platforms require high-current routing, thicker copper, and thermal spreading capability that combustion platforms rarely demand.

By PCB Type

Sub-SegmentKey Trend
Single-LayerCost-driven volume in lighting, actuators, and discrete sensors
Double-LayerBody control and comfort modules maintain steady replacement demand.
Multi-LayerPowertrain and chassis controllers migrate toward higher layer counts.
High-Density InterconnectDomain controller consolidation drives sequential lamination adoption.


Construction type separates commodity supply from defensible capability. Fabricators competing only in low-layer-count work face persistent margin pressure, while advanced interconnect capacity remains capital-constrained and comparatively insulated.

By Substrate

Sub-SegmentKey Trend
RigidDefault construction for housed powertrain and chassis electronics
FlexibleCamera modules, display interconnects, and cell-contacting systems
Rigid-FlexConnector elimination improves warranty performance in confined assemblies.


Substrate selection increasingly follows packaging constraints rather than cost alone. As available volume inside vehicle structures shrinks, three-dimensional construction becomes a design necessity.

By Application

Sub-SegmentKey Trend
ADAS & Safety SystemsRegulatory mandates set a rising content floor across all trim levels
Powertrain & ElectrificationHighest average board value per unit on heavy copper requirements
Infotainment & ConnectivityDisplay area growth and 5G telematics lift layer counts.
Body & Comfort ElectronicsSteady volume base with modest specification escalation
Autonomous Driving ComputeRedundant architectures multiply board content per vehicle.


Application mix reflects regulation and packaging pressure more than consumer demand. Safety and electrification jointly account for the majority of forecast revenue growth.

By Level of Automation

Sub-SegmentKey Trend
SAE Level 0–2Mass-market assistance packages sustain the largest revenue base
SAE Level 3Approval geography, not technology, limits near-term deployment.
SAE Level 4–5Redundant compute and sensing drive exceptional content per unit


Automation level correlates directly with redundancy requirements. Each step upward duplicates power and signal paths, multiplying board content well beyond what sensor count alone would suggest.

By Geography

Sub-SegmentKey Trend
North AmericaReshoring incentives outpace domestic bare-board capacity build-out
EuropeHigh content per vehicle offsets comparatively modest unit volumes
Asia-PacificIntegrated fabrication and assembly base sustains structural dominance.
South AmericaLocal content rules encourage regional electronics assembly.
Middle East & AfricaAssembly localisation programmes create early-stage demand.


Geographic concentration reflects the co-location logic of bare-board supply. Freight economics keep fabrication close to assembly, which is why capacity migration follows vehicle plants rather than leading them.


 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.