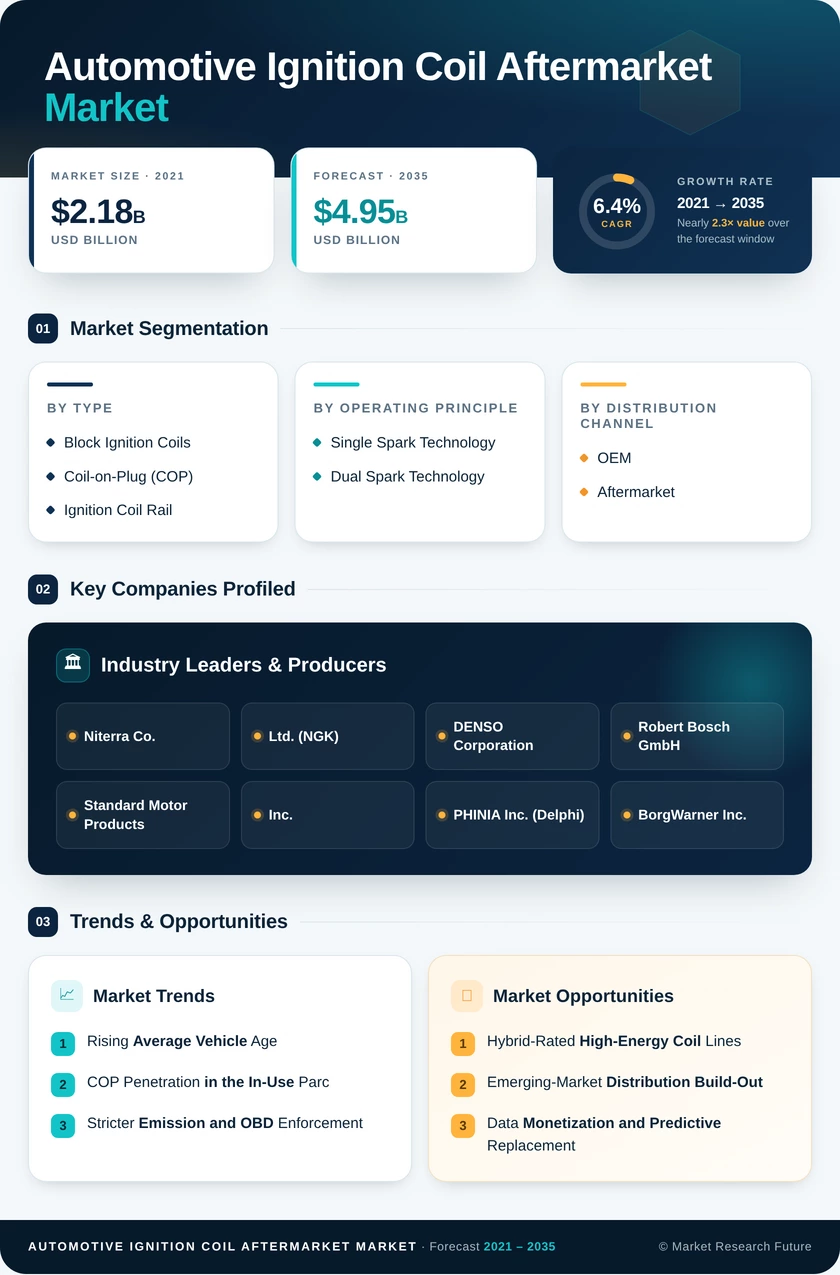
Automotive Ignition Coil Aftermarket Market (2026 - 2035)

ID: MRFR/AT/6243-CR 200 Pages Shubham Munde Last Updated: November 18, 2026
Automotive Ignition Coil Aftermarket Market Research Report By Type (Block Ignition Coils, Coil-on-Plug (COP), Ignition Coil Rail), By Operating Principle (Single Spark Technology, Dual Spark Technology), By Distribution Channel (OEM, Aftermarket), By Vehicle Type (Passenger Cars, Commercial Vehicles) - Forecast to 2035
Automotive Ignition Coil Aftermarket Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.4%
2025 Market SizeUSD 2.66 Billion
2035 Market SizeUSD 4.95 Billion
Key Players
Niterra Co.
Ltd.
DENSO Corporation
Robert Bosch GmbH
Standard Motor Products, Inc.
PHINIA Inc.
Opportunities
  • Hybrid-Rated High-Energy Coil Lines
  • Emerging-Market Distribution Build-Out
  • Data Monetization and Predictive Replacement
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Type | |
    2. 2.2 By Operating Principle | |
    3. 2.3 By Distribution Channel | |
    4. 2.4 By Vehicle Type | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Rising Average Vehicle Age | |
    2. 4.2 COP Penetration in the In-Use Parc | |
    3. 4.3 Stricter Emission and OBD Enforcement | |
    4. 4.4 Hybrid Fleet Growth | |
    5. 4.5 E-commerce and Digital Parts Catalogues | |
    6. 4.6 Flex-Fuel and Ethanol-Blend Fleets | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Battery-Electric Vehicle Substitution | |
    2. 5.2 Copper and Raw-Material Price Volatility | |
    3. 5.3 Rare-Earth and Magnet Supply Risk | |
    4. 5.4 Tariffs on Imported Auto Parts | |
    5. 5.5 Low-Cost Counterfeit and Grey-Market Coils | |
  6. 6 Opportunities | |
    1. 6.1 Hybrid-Rated High-Energy Coil Lines | |
    2. 6.2 Emerging-Market Distribution Build-Out | |
    3. 6.3 Data Monetization and Predictive Replacement | |
    4. 6.4 Regional Assembly to Offset Tariffs | |
    5. 6.5 Multi-Pack and Complete-Set Programmes | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Rest of North America | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Russia | | |
      6. 7.2.6 Rest of Europe | |
    3. 7.3 Asia Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 India | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 Australia | | |
      6. 7.3.6 New Zealand | | |
      7. 7.3.7 Rest of Asia Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 United Arab Emirates | | |
      3. 7.5.3 Egypt | | |
      4. 7.5.4 Turkey | | |
      5. 7.5.5 South Africa | | |
      6. 7.5.6 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 The Hybrid Bridge | |
    2. 8.2 Connected Diagnostics and Predictive Maintenance | |
    3. 8.3 Supply-Chain Regionalisation | |
    4. 8.4 Sustainability and Circularity | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Type | | |
      1. 9.1.1 Block Ignition Coils | | |
      2. 9.1.2 Coil-on-Plug (COP) | | |
      3. 9.1.3 Ignition Coil Rail | |
    2. 9.2 By Operating Principle | | |
      1. 9.2.1 Single Spark Technology | | |
      2. 9.2.2 Dual Spark Technology | |
    3. 9.3 By Distribution Channel | | |
      1. 9.3.1 OEM | | |
      2. 9.3.2 Aftermarket | |
    4. 9.4 By Vehicle Type | | |
      1. 9.4.1 Passenger Cars | | |
      2. 9.4.2 Commercial Vehicles | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Niterra Co., Ltd. (NGK) | | |
      2. 10.3.2 DENSO Corporation | | |
      3. 10.3.3 Robert Bosch GmbH | | |
      4. 10.3.4 Standard Motor Products, Inc. | | |
      5. 10.3.5 PHINIA Inc. (Delphi) | | |
      6. 10.3.6 BorgWarner Inc. | | |
      7. 10.3.7 Hitachi Astemo, Ltd. | | |
      8. 10.3.8 Mitsubishi Electric Corporation | | |
      9. 10.3.9 Diamond Electric Holdings | | |
      10. 10.3.10 Valeo SA | | |
      11. 10.3.11 Marelli Holdings | | |
      12. 10.3.12 Tenneco Inc. (Champion) | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Ignition Coil Aftermarket Summary Metrics, 2025–2035 | |
  16. TABLE 2 Global Ignition Coil Aftermarket Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis on Forecast CAGR | |
  18. TABLE 4 Restraint Impact Analysis on Forecast CAGR | |
  19. TABLE 5 Global Ignition Coil Aftermarket, by Region, 2025 | |
  20. TABLE 6 North America Ignition Coil Aftermarket, by Country, 2025 | |
  21. TABLE 7 Europe Ignition Coil Aftermarket, by Country, 2025 | |
  22. TABLE 8 Asia Pacific Ignition Coil Aftermarket, by Country, 2025 | |
  23. TABLE 9 South America Ignition Coil Aftermarket, by Country, 2025 | |
  24. TABLE 10 Middle East and Africa Ignition Coil Aftermarket, by Country, 2025 | |
  25. TABLE 11 Global Ignition Coil Aftermarket, by Type, 2025 | |
  26. TABLE 12 Global Ignition Coil Aftermarket, by Operating Principle, 2025 | |
  27. TABLE 13 Global Ignition Coil Aftermarket, by Distribution Channel, 2025 | |
  28. TABLE 14 Global Ignition Coil Aftermarket, by Vehicle Type, 2025 | |
  29. TABLE 15 Competitive Benchmarking Matrix, Key Ignition Coil Aftermarket Suppliers | |
  30. TABLE 16 Report Scope and Methodology | |
  31. TABLE 17 Detailed Sources and Citations | | LIST OF FIGURES | |
  32. FIGURE 1 Market Dynamics Overview: Drivers, Restraints and Opportunities | |
  33. FIGURE 2 Ignition Coil Aftermarket Value Chain Analysis | |
  34. FIGURE 3 Porter's Five Forces Analysis | |
  35. FIGURE 4 Global Ignition Coil Aftermarket Size Trend, 2021–2035 (USD Billion) | |
  36. FIGURE 5 Year-over-Year Growth Trend, 2022–2035 | |
  37. FIGURE 6 Share by Type, 2025 | |
  38. FIGURE 7 Share by Operating Principle, 2025 | |
  39. FIGURE 8 Share by Distribution Channel, 2025 | |
  40. FIGURE 9 Share by Vehicle Type, 2025 | |
  41. FIGURE 10 Regional Share, 2025 | |
  42. FIGURE 11 Country Share within Each Region, 2025 | |
  43. FIGURE 12 Competitive Landscape: Estimated Revenue Share Ranges of Key Players

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypeBlock Ignition Coils; Coil-on-Plug (COP); Ignition Coil RailCoil-on-Plug (COP) (6.6% CAGR)Coil-on-Plug (COP) (6.6% CAGR)
By Operating PrincipleSingle Spark Technology; Dual Spark TechnologySingle Spark Technology (58.1% share)Dual Spark Technology (USD 1.11 Billion)
By Distribution ChannelOEM; AftermarketAftermarket (6.5% CAGR)Aftermarket (6.5% CAGR)
By Vehicle TypePassenger Cars; Commercial VehiclesPassenger Cars (68.4% share)Commercial Vehicles (6.7% CAGR)
By RegionNorth America; Europe; Asia Pacific; South America; Middle East and AfricaAsia Pacific (41.2% share)Asia Pacific (41.2% share)

Market Segmentation Overview

By Type

Sub-SegmentKey Trend
Block Ignition CoilsSteady demand from older and entry-level vehicles
Coil-on-Plug (COP)Set replacement on high-mileage turbo-GDI engines
Ignition Coil RailHigh unit value in a narrow set of engine families

Coil-on-Plug (COP) leads by type and also grows fastest, because every cylinder carries its own replaceable coil and direct-injection engines built after 2012 are now entering peak failure years. Block Ignition Coils hold a stable base in older vehicles and cost-sensitive markets, while Ignition Coil Rail stays a high-value niche tied to specific engines.

By Operating Principle

Sub-SegmentKey Trend
Single Spark TechnologyDefault design on modern COP engines
Dual Spark TechnologyGains from flex-fuel and waste-spark engines

Single Spark Technology leads because nearly all modern COP engines fire one spark per coil per cycle. Dual Spark Technology grows faster, supported by waste-spark engines in older fleets and by Brazil's flex-fuel parc, where multiple ignition events help stabilise combustion across ethanol blends.

By Distribution Channel

Sub-SegmentKey Trend
OEMRetains newer vehicles under warranty
AftermarketGains as vehicles leave dealer service

The Aftermarket channel leads and grows fastest as vehicles exit warranty and move to independent garages, retail chains and e-commerce. The OEM channel holds its position on newer vehicles, where warranty coverage and dealer-linked diagnostic software keep coil repairs inside franchised workshops.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsLargest parc with rising average age
Commercial VehiclesHigh mileage and slower electrification

Passenger Cars lead on fleet size and the prevalence of multi-cylinder COP engines. Commercial Vehicles grow fastest because gasoline vans, pickups and light trucks accumulate high annual mileage and stay in service longer, and fleet buyers favour durable coils that cut unplanned downtime.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.