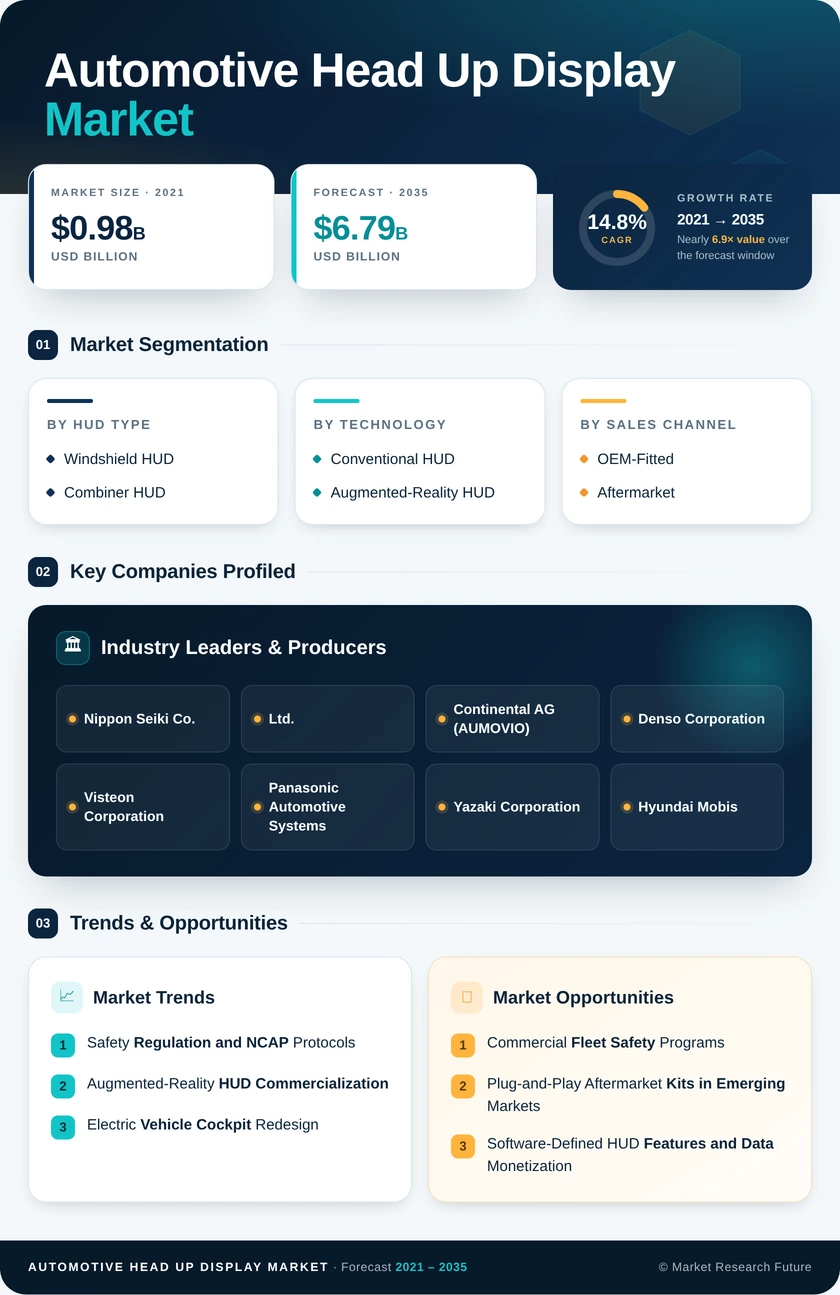
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By HUD Type | Windshield HUD, Combiner HUD | Windshield HUD (68.4% share) | Combiner HUD (15.1% CAGR) |
| By Technology | Conventional HUD, Augmented-Reality HUD | Conventional HUD (USD 1.10 Billion (2025)) | Augmented-Reality HUD (15.4% CAGR) |
| By Sales Channel | OEM-Fitted, Aftermarket | OEM-Fitted (78.9% share) | Aftermarket (15.9% CAGR) |
| By Vehicle Type | Passenger Cars, Commercial Vehicles | Passenger Cars (85.2% share) | Commercial Vehicles (15.8% CAGR) |
| By Region | North America, Europe, Asia-Pacific, South America, Middle East and Africa | Europe (36.8% share) | Asia-Pacific (16.9% CAGR) |
Market Segmentation Overview
By HUD Type
| Sub-Segment | Key Trend |
|---|---|
| Windshield HUD | Panoramic, full-width images replacing secondary cabin screens |
| Combiner HUD | Brighter, anti-glare modules suited to retrofits and budget models |
Windshield HUD leads because it integrates invisibly into the cabin and supports the large virtual images premium brands now use in place of secondary screens. Combiner HUD grows fastest, since its self-contained optics avoid vehicle-specific windshield geometry and cut installation time. That independence makes combiners the practical route into cost-sensitive trims and used-vehicle upgrades.
By Technology
| Sub-Segment | Key Trend |
|---|---|
| Conventional HUD | Cost-optimized TFT-LCD units meeting legibility requirements |
| Augmented-Reality HUD | Depth-accurate overlays enabled by DLP, laser, and holographic engines |
Conventional HUD holds the revenue lead because it meets luminance and legibility requirements at a low cost for high-volume programs. Augmented-Reality HUD grows fastest as cheaper PGUs and stronger graphics processors allow guidance to be placed at true road distance. Level 3 takeover requests will further favor AR units, since they show system status most intuitively.
By Sales Channel
| Sub-Segment | Key Trend |
|---|---|
| OEM-Fitted | HUDs sourced within integrated cockpit modules |
| Aftermarket | Sub-USD 250 plug-and-play kits with simplified installation |
OEM-Fitted units dominate because design-stage integration optimizes the optical path and brings warranty coverage. Aftermarket kits grow fastest as falling PGU costs make plug-and-play products affordable for drivers keeping vehicles longer. Installer training that protects ADAS camera calibration is removing a key adoption barrier for retrofits.
By Vehicle Type
| Sub-Segment | Key Trend |
|---|---|
| Passenger Cars | HUDs spreading from premium to mid-price electric models |
| Commercial Vehicles | Color-coded blind-spot alerts and telematics-linked coaching |
Passenger Cars lead because consumers value immersive navigation and regulators require clear, eyes-forward ADAS warnings. Commercial Vehicles grow fastest because fleet operators can measure HUD returns through lower insurance costs and less downtime. Integration with telematics platforms will add fuel-efficiency coaching, broadening the case for trucks and buses.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA