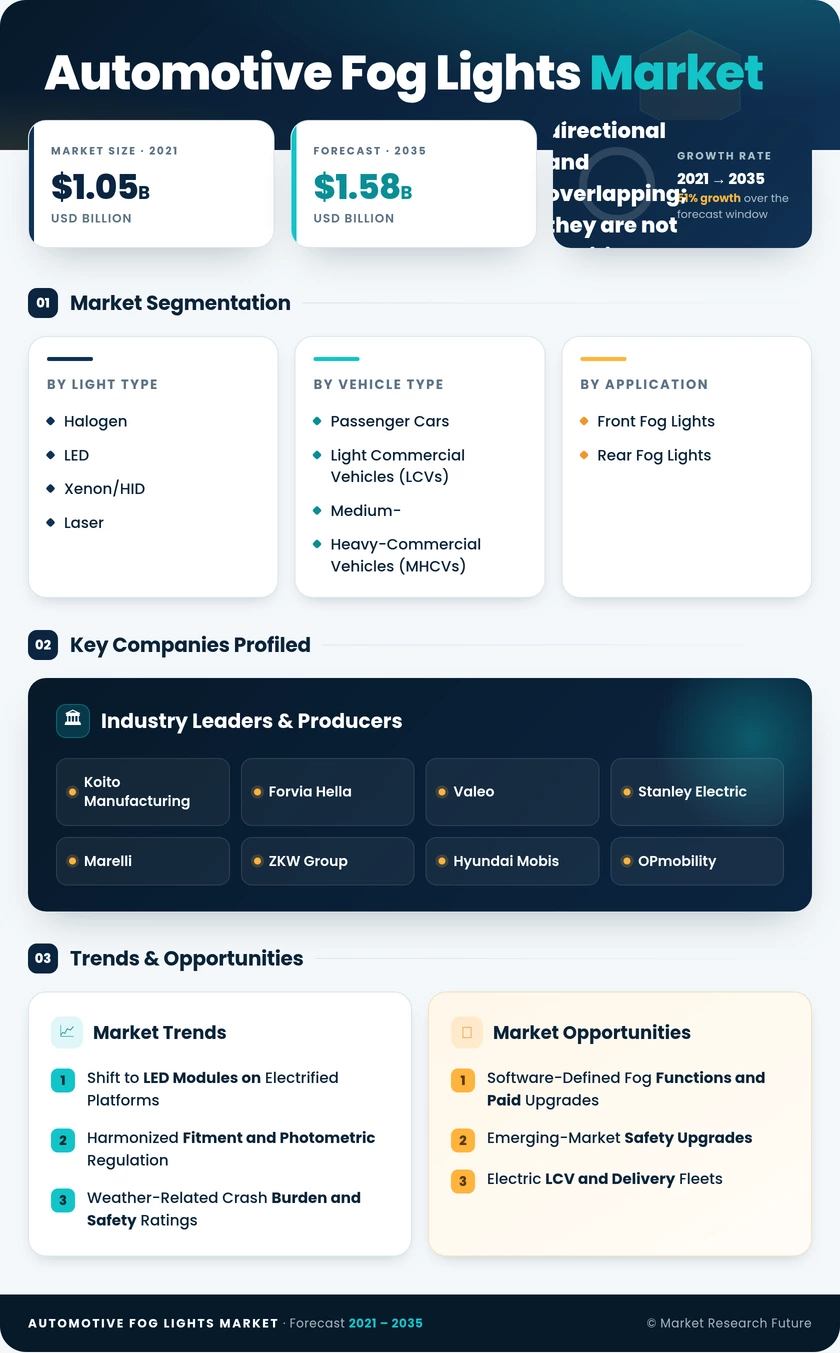
Automotive Fog Lights Market (2026 - 2035)

ID: MRFR/AT/2453-CR 101 Pages Shubham Munde Last Updated: September 23, 2026
Automotive Fog Lights Market Research Report By Light Type (Halogen, LED, Xenon/HID, Laser), By Vehicle Type (Passenger Cars, Light Commercial Vehicles (LCVs), Medium- and Heavy-Commercial Vehicles (MHCVs)), By Application (Front Fog Lights, Rear Fog Lights), By Technology (Conventional Static Fog Lights, Adaptive Fog Lights), By Distribution Channel (OEM, Aftermarket) - Forecast to 2035
Automotive Fog Lights Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)2.84%
2025 Market SizeUSD 1.20 Billion
2035 Market SizeUSD 1.58 Billion
Key Players
Koito Manufacturing
Forvia Hella
Valeo
Stanley Electric
Marelli
ZKW Group
Opportunities
  • Software-Defined Fog Functions and Paid Upgrades
  • Emerging-Market Safety Upgrades
  • Electric LCV and Delivery Fleets
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Light Type | |
    2. 2.2 By Vehicle Type | |
    3. 2.3 By Application | |
    4. 2.4 By Technology | |
    5. 2.5 By Distribution Channel | |
    6. 2.6 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Shift to LED Modules on Electrified Platforms | |
    2. 4.2 Harmonized Fitment and Photometric Regulation | |
    3. 4.3 Weather-Related Crash Burden and Safety Ratings | |
    4. 4.4 Adaptive Beam Control and Sensor Fusion | |
    5. 4.5 Localized Asia-Pacific Production and Cost-Down | |
    6. 4.6 SUV, Pickup, and Off-Road Accessory Demand | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Integration into Main Headlamp Modules | |
    2. 5.2 LED and Semiconductor Cost Volatility | |
    3. 5.3 Extended LED Lifetimes | |
    4. 5.4 Non-Compliant Aftermarket Retrofits | |
    5. 5.5 Thermal and Cost Barriers | |
  6. 6 Opportunities | |
    1. 6.1 Software-Defined Fog Functions and Paid Upgrades | |
    2. 6.2 Emerging-Market Safety Upgrades | |
    3. 6.3 Electric LCV and Delivery Fleets | |
    4. 6.4 Hybrid LED–Laser Modules and Advanced Thermal Materials | |
    5. 6.5 Certified Plug-and-Play Aftermarket Kits | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Rest of North America | |
    2. 7.2 South America | | |
      1. 7.2.1 Brazil | | |
      2. 7.2.2 Argentina | | |
      3. 7.2.3 Rest of South America | |
    3. 7.3 Europe | | |
      1. 7.3.1 Germany | | |
      2. 7.3.2 UK | | |
      3. 7.3.3 France | | |
      4. 7.3.4 Italy | | |
      5. 7.3.5 Spain | | |
      6. 7.3.6 Russia | | |
      7. 7.3.7 Rest of Europe | |
    4. 7.4 Asia-Pacific | | |
      1. 7.4.1 China | | |
      2. 7.4.2 Japan | | |
      3. 7.4.3 India | | |
      4. 7.4.4 South Korea | | |
      5. 7.4.5 Rest of Asia-Pacific | |
    5. 7.5 Middle East and Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Rest of Middle East and Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Weather-Aware Lighting and Sensor Fusion | |
    2. 8.2 Electrification Supercycle | |
    3. 8.3 Software-Defined Vehicle Economics | |
    4. 8.4 Circularity and Sustainability Rules | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Light Type | | |
      1. 9.1.1 Halogen | | |
      2. 9.1.2 LED | | |
      3. 9.1.3 Xenon/HID | | |
      4. 9.1.4 Laser | |
    2. 9.2 By Vehicle Type | | |
      1. 9.2.1 Passenger Cars | | |
      2. 9.2.2 Light Commercial Vehicles (LCVs) | | |
      3. 9.2.3 Medium- and Heavy-Commercial Vehicles (MHCVs) | |
    3. 9.3 By Application | | |
      1. 9.3.1 Front Fog Lights | | |
      2. 9.3.2 Rear Fog Lights | |
    4. 9.4 By Technology | | |
      1. 9.4.1 Conventional Static Fog Lights | | |
      2. 9.4.2 Adaptive Fog Lights | |
    5. 9.5 By Distribution Channel | | |
      1. 9.5.1 OEM | | |
      2. 9.5.2 Aftermarket | |
  10. 10 Competitive Landscape | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Market Snapshot – Key Metrics, 2025–2035 | |
  16. TABLE 2 Global Market Size and Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis, 2026–2035 | |
  18. TABLE 4 Restraints Impact Analysis, 2026–2035 | |
  19. TABLE 5 Regional Summary, by Key Metric, 2025 | |
  20. TABLE 6 North America Market, by Country | |
  21. TABLE 7 South America Market, by Country | |
  22. TABLE 8 Europe Market, by Country | |
  23. TABLE 9 Asia-Pacific Market, by Country | |
  24. TABLE 10 Middle East and Africa Market, by Country | |
  25. TABLE 11 Market Segmentation, by Light Type | |
  26. TABLE 12 Market Segmentation, by Vehicle Type | |
  27. TABLE 13 Market Segmentation, by Application | |
  28. TABLE 14 Market Segmentation, by Technology | |
  29. TABLE 15 Market Segmentation, by Distribution Channel | |
  30. TABLE 16 Competitive Benchmarking Matrix, 2025 | |
  31. TABLE 17 Report Scope and Methodology | |
  32. TABLE 18 Detailed Sources and Citations | |
  33. TABLE 19 Segmentation Quick Reference | | LIST OF FIGURES | |
  34. FIGURE 1 Market Dynamics Overview – Drivers, Restraints, Opportunities | |
  35. FIGURE 2 Industry Value Chain Analysis | |
  36. FIGURE 3 Porter's Five Forces Analysis | |
  37. FIGURE 4 Global Market Size Trend (USD Billion), 2021–2035 | |
  38. FIGURE 5 Market Share, by Light Type, 2025 | |
  39. FIGURE 6 Market Share, by Vehicle Type, 2025 | |
  40. FIGURE 7 Market Share, by Application, 2025 | |
  41. FIGURE 8 Market Share, by Technology, 2025 | |
  42. FIGURE 9 Market Share, by Distribution Channel, 2025 | |
  43. FIGURE 10 Market Share, by Region, 2025 | |
  44. FIGURE 11 Asia-Pacific Country-Level Share, 2025 | |
  45. FIGURE 12 Competitive Landscape – Estimated Revenue Share Ranges, 2025

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Light TypeHalogen, LED, Xenon/HID, LaserLED (55.6% share)Laser (9.5% CAGR)
By Vehicle TypePassenger Cars, Light Commercial Vehicles (LCVs), Medium- and Heavy-Commercial Vehicles (MHCVs)Passenger Cars (64.0% share)Light Commercial Vehicles (LCVs) (3.4% CAGR)
By ApplicationFront Fog Lights, Rear Fog LightsFront Fog Lights (75.5% share)Front Fog Lights (75.5% share)
By TechnologyConventional Static Fog Lights, Adaptive Fog LightsConventional Static Fog Lights (81.8% share)Adaptive Fog Lights (4.2% CAGR)
By Distribution ChannelOEM, AftermarketOEM (58.8% share)Aftermarket (3.3% CAGR)
By RegionNorth America, South America, Europe, Asia-Pacific, Middle East and AfricaAsia-Pacific (39.9% share)Asia-Pacific (39.9% share)


Market Segmentation Overview

By Light Type

Sub-SegmentKey Trend
HalogenRetreating to low-cost replacement and entry trims
LEDStandard on new OEM platforms, especially EVs
Xenon/HIDPhasing out as ballast systems lose to solid-state units
LaserHybrid LED–laser modules under development for flagship models


LED leads this dimension because solid-state modules cut power draw and last the vehicle's lifetime, which suits electrified platforms. Laser grows fastest from a very small base, but its adoption hinges on thermal management breakthroughs. Halogen and Xenon/HID are both losing OEM fitment, with halogen holding on mainly in replacement channels.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsLED and adaptive features spreading into compact and mid-size models
Light Commercial Vehicles (LCVs)Electric delivery vans specifying long-life LED fog units
Medium- and Heavy-Commercial Vehicles (MHCVs)Durability-focused fitment for long-haul operations


Passenger Cars account for the largest share because fog lamps are widely fitted on SUVs and crossovers that dominate new-car sales. Light Commercial Vehicles (LCVs) grow fastest as fleet buyers favor low-draw LED units on electric vans to reduce downtime. Medium- and Heavy-Commercial Vehicles (MHCVs) provide steady, durability-driven demand.

By Application

Sub-SegmentKey Trend
Front Fog LightsAdaptive matrix designs adding value to the front unit
Rear Fog LightsRegulated base demand; LED light-bar integration on premium models


Front Fog Lights both lead and grow fastest, as camera-linked adaptive designs raise the value of each unit. Rear Fog Lights rest on mandatory fitment in Europe and China, which secures volume but limits growth to content upgrades such as color-balanced LED modules.

By Technology

Sub-SegmentKey Trend
Conventional Static Fog LightsPreferred for budget models and price-sensitive markets
Adaptive Fog LightsFalling controller costs bring beam shaping to mid-size vehicles


Conventional Static Fog Lights dominate because simple circuitry keeps tooling and certification costs low. Adaptive Fog Lights grow fastest as pixel-module costs decline and OEMs link lighting to ADAS sensors, supported by ventures such as the Stanley Electric–Mitsubishi Electric Mobility partnership.

By Distribution Channel

Sub-SegmentKey Trend
OEMIntegrated styling and multi-region homologation
AftermarketGrowth in type-approved LED kits and accessory lamps


OEM leads because automakers integrate fog lamps with vehicle styling and electrical systems during homologation. The Aftermarket grows faster on halogen-to-LED upgrades and off-road accessories, though growth depends on certified kits as enforcement against non-compliant retrofits tightens.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.