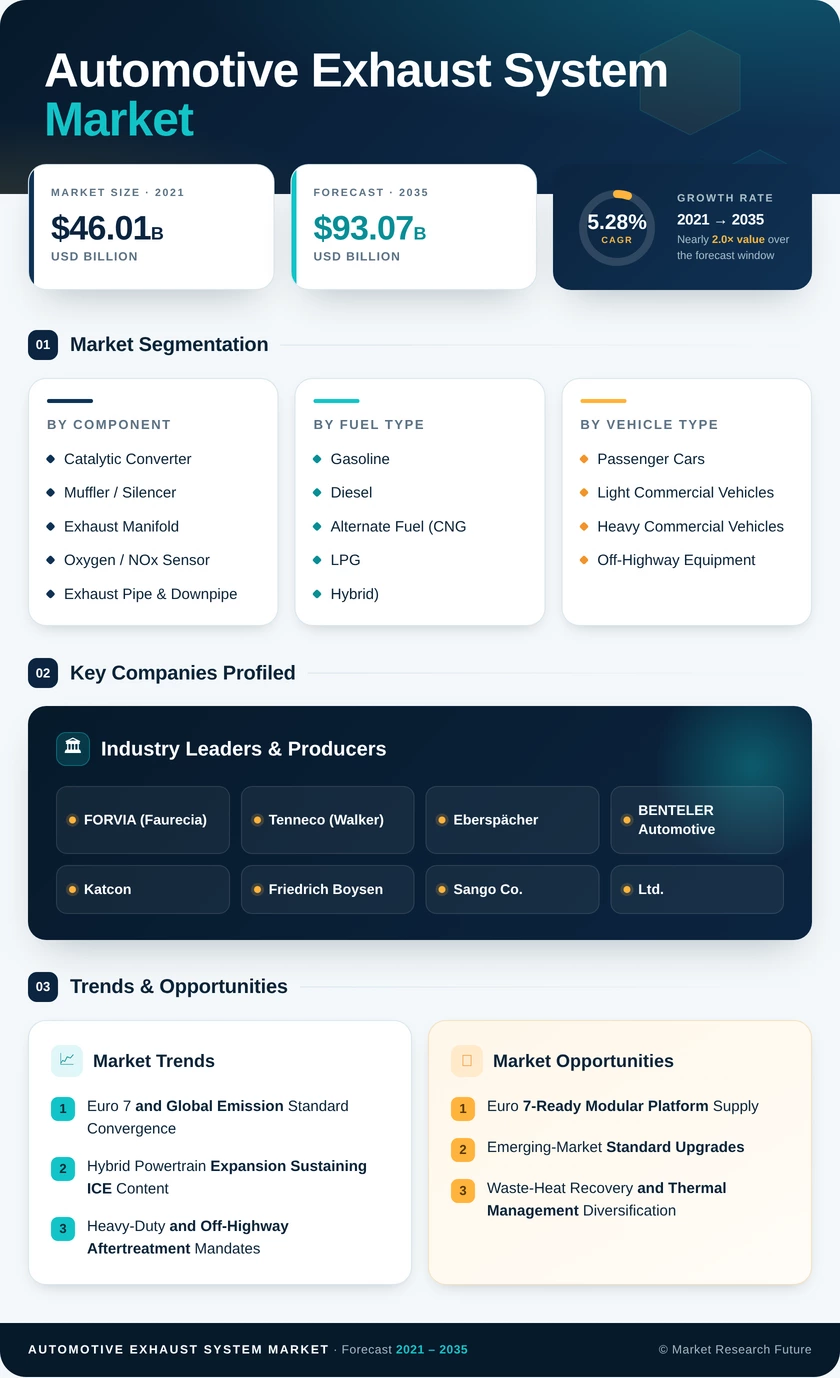
Automotive Exhaust System Market (2026 - 2035)

ID: MRFR/AT/1411-CR 100 Pages Shubham Munde Last Updated: October 16, 2026
Automotive Exhaust System Market Research Report By Component (Catalytic Converter, Muffler / Silencer, Exhaust Manifold, Oxygen / NOx Sensor, Exhaust Pipe & Downpipe, Diesel Particulate Filter), By Fuel Type (Gasoline, Diesel, Alternate Fuel (CNG, LPG, Hybrid)), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Off-Highway Equipment), By System Type (Single Exhaust System, Dual Exhaust System, Header System, Cat-Back / Axle-Back System), By Sales Channel (OEM, Aftermarket) - Forecast to 2035
Automotive Exhaust System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.28%
2025 Market SizeUSD 55.63 Billion
2035 Market SizeUSD 93.07 Billion
Key Players
FORVIA
Tenneco
Eberspächer
BENTELER Automotive
Katcon
Friedrich Boysen
Opportunities
  • Euro 7-Ready Modular Platform Supply
  • Emerging-Market Standard Upgrades
  • Waste-Heat Recovery and Thermal Management Diversification
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Takeaways | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Dynamics — Drivers | |
    1. 4.1 Euro 7 and Global Emission Standard Convergence | |
    2. 4.2 Hybrid Powertrain Expansion Sustaining ICE Content | |
    3. 4.3 Heavy-Duty and Off-Highway Aftertreatment Mandates | |
    4. 4.4 Low-Emission Zone Proliferation and Retrofit Demand | |
    5. 4.5 Gasoline Particulate Filter Adoption | |
    6. 4.6 Ageing Vehicle Parc and Replacement Cycle | |
    7. 4.7 Acoustic Engineering and Lightweight Alloy Content | |
  5. 5 Market Dynamics — Restraints | |
    1. 5.1 Battery Electric Vehicle Penetration | |
    2. 5.2 Platinum-Group Metal Price Volatility | |
    3. 5.3 OEM Cost-Down and Platform Consolidation | |
    4. 5.4 Converter Theft and Counterfeit Aftermarket Parts | |
    5. 5.5 Regulatory Timeline Uncertainty Deferring Capex | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Euro 7-Ready Modular Platform Supply | |
    2. 6.2 Emerging-Market Standard Upgrades | |
    3. 6.3 Waste-Heat Recovery and Thermal Management Diversification | |
    4. 6.4 On-Board Monitoring Data as a Service | |
    5. 6.5 Premium Acoustic and Performance Retrofit | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) | |
    1. 8.1 The Hybrid Supercycle | |
    2. 8.2 Materials Substitution and PGM Thrifting | |
    3. 8.3 Digital Compliance and On-Board Monitoring | |
    4. 8.4 Circularity and Scope 3 Reporting | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Catalytic Converter | | |
      2. 9.1.2 Muffler / Silencer | | |
      3. 9.1.3 Exhaust Manifold | | |
      4. 9.1.4 Oxygen / NOx Sensor | | |
      5. 9.1.5 Exhaust Pipe & Downpipe | | |
      6. 9.1.6 Diesel Particulate Filter | |
    2. 9.2 By Fuel Type | | |
      1. 9.2.1 Gasoline | | |
      2. 9.2.2 Diesel | | |
      3. 9.2.3 Alternate Fuel (CNG, LPG, Hybrid) | |
    3. 9.3 By Vehicle Type | | |
      1. 9.3.1 Passenger Cars | | |
      2. 9.3.2 Light Commercial Vehicles | | |
      3. 9.3.3 Heavy Commercial Vehicles | | |
      4. 9.3.4 Off-Highway Equipment | |
    4. 9.4 By System Type | | |
      1. 9.4.1 Single Exhaust System | | |
      2. 9.4.2 Dual Exhaust System | | |
      3. 9.4.3 Header System | | |
      4. 9.4.4 Cat-Back / Axle-Back System | |
    5. 9.5 By Sales Channel | | |
      1. 9.5.1 OEM | | |
      2. 9.5.2 Aftermarket | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 FORVIA (Faurecia) | | |
      2. 10.3.2 Tenneco | | |
      3. 10.3.3 Eberspächer | | |
      4. 10.3.4 BENTELER Automotive | | |
      5. 10.3.5 Katcon | | |
      6. 10.3.6 Friedrich Boysen | | |
      7. 10.3.7 Sango Co., Ltd. | | |
      8. 10.3.8 Futaba Industrial | | |
      9. 10.3.9 Yutaka Giken | | |
      10. 10.3.10 Sejong Industrial | | |
      11. 10.3.11 Bosal | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Automotive Exhaust System Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Automotive Exhaust System Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis — Estimated Contribution to CAGR, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis — Estimated Drag on CAGR, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Component, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Fuel Type, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Market Size, by System Type, 2021–2035 (USD Billion) | |
  29. TABLE 15 Global Market Size, by Sales Channel, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Market Size, by Component and Fuel Type, 2021–2035 (USD Billion) | |
  31. TABLE 17 Europe Market Size, by Component and Fuel Type, 2021–2035 (USD Billion) | |
  32. TABLE 18 Asia-Pacific Market Size, by Component and Fuel Type, 2021–2035 (USD Billion) | |
  33. TABLE 19 South America Market Size, by Component and Fuel Type, 2021–2035 (USD Billion) | |
  34. TABLE 20 Middle East & Africa Market Size, by Component and Fuel Type, 2021–2035 (USD Billion) | |
  35. TABLE 21 Competitive Benchmarking Matrix, 2026 | |
  36. TABLE 22 Company Profiles — Key Players | |
  37. TABLE 23 Recent Developments & Strategic Announcements, 2023–2025 | |
  38. TABLE 24 Report Scope & Methodology Summary | |
  39. TABLE 25 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  40. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities Framework | |
  41. FIGURE 2 Industry Value Chain Analysis — Raw Materials to Aftermarket Distribution | |
  42. FIGURE 3 Porter's Five Forces Analysis | |
  43. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  44. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) | |
  45. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) | |
  46. FIGURE 7 Market Share by Fuel Type, 2025 vs 2035 (%) | |
  47. FIGURE 8 Market Share by Vehicle Type, 2025 (%) | |
  48. FIGURE 9 Market Share by System Type, 2025 (%) | |
  49. FIGURE 10 OEM vs Aftermarket Channel Split, 2025–2035 (%) | |
  50. FIGURE 11 Regional Market Share Distribution, 2025 (%) | |
  51. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) | |
  52. FIGURE 13 Country-Level Share within Asia-Pacific, 2025 (%) | |
  53. FIGURE 14 Country-Level Share within Europe, 2025 (%) | |
  54. FIGURE 15 Competitive Landscape — Estimated Revenue Share Bands, 2026 | |
  55. FIGURE 16 Competitive Positioning Map — Scale vs Electrification Readiness | |
  56. FIGURE 17 Powertrain Mix Scenario Impact on Addressable Content, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentCatalytic Converter; Muffler / Silencer; Exhaust Manifold; Oxygen / NOx Sensor; Exhaust Pipe & Downpipe; Diesel Particulate FilterCatalytic ConverterOxygen / NOx Sensor
By Fuel TypeGasoline; Diesel; Alternate Fuel (CNG, LPG, Hybrid)GasolineAlternate Fuel
By Vehicle TypePassenger Cars; Light Commercial Vehicles; Heavy Commercial Vehicles; Off-Highway EquipmentPassenger CarsOff-Highway Equipment
By System TypeSingle Exhaust System; Dual Exhaust System; Header System; Cat-Back / Axle-Back SystemSingle Exhaust SystemHeader System
By Sales ChannelOEM; AftermarketOEMAftermarket
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
Catalytic ConverterBimetallic washcoat chemistry reducing platinum-group loading without efficiency loss
Muffler / SilencerActive valve integration migrating from premium into mainstream platforms
Exhaust ManifoldClose-coupled designs to accelerate catalyst light-off under cold-start limits
Oxygen / NOx SensorTriple-gas sensing to satisfy continuous on-board monitoring obligations
Exhaust Pipe & DownpipeFerritic and austenitic stainless substitution for extended corrosion durability
Diesel Particulate FilterHigher ash-capacity substrates supporting longer service intervals


Component value is concentrating upstream, toward catalyst chemistry and sensing, while downstream tubing competes increasingly on materials engineering rather than fabrication cost. Suppliers with metallurgical and washcoat capability retain pricing power; pure fabricators face steady margin compression as OEMs standardise across consolidated platforms.

By Fuel Type

Sub-SegmentKey Trend
GasolineUniversal particulate filter fitment on direct-injection platforms
DieselStacked SCR, DPF and dosing architectures raising value per system
Alternate Fuel (CNG, LPG, Hybrid)Methane-slip catalysts opening a distinct chemistry niche


Fuel-type economics diverge sharply from fuel-type volumes. Gasoline dominates units while diesel carries the richest per-system content, and alternate-fuel platforms grow fastest as municipal and logistics fleets seek interim compliance routes that avoid full charging-infrastructure commitments.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsHybrid content growth offsetting combustion unit-volume decline
Light Commercial VehiclesLast-mile logistics expansion against early low-emission-zone exclusion
Heavy Commercial VehiclesEPA 2027 and Euro VII driving step-change NOx reduction requirements
Off-Highway EquipmentStage V and Tier 4 Final compliance in construction, agriculture and mining


Growth momentum sits at the heavy and off-highway end of the vehicle spectrum, where duty cycles, service intensity and slow electrification combine to protect demand. Passenger cars retain scale leadership but face the steepest substitution pressure across European and Chinese urban fleets.

By System Type

Sub-SegmentKey Trend
Single Exhaust SystemCost and packaging advantage on high-volume compact platforms
Dual Exhaust SystemPremium and larger-displacement application standard
Header SystemThermal management for faster catalyst light-off under cold-start rules
Cat-Back / Axle-Back SystemPreferred retrofit format leaving homologated aftertreatment intact


System architecture increasingly follows thermal strategy rather than acoustic preference. Header configurations expand fastest because exhaust-side heat management has become a compliance requirement, while retrofit formats concentrate downstream of the catalyst to preserve type approval.

By Sales Channel

Sub-SegmentKey Trend
OEMMulti-year programme pricing with constrained cost pass-through
AftermarketInspection-driven replacement demand insulated from new-vehicle mix


Channel exposure is the clearest strategic hedge available to suppliers. Aftermarket demand tracks the installed parc, which turns over across a decade or more, so it remains resilient well past the point at which new-vehicle combustion fitment begins its structural decline.


Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.