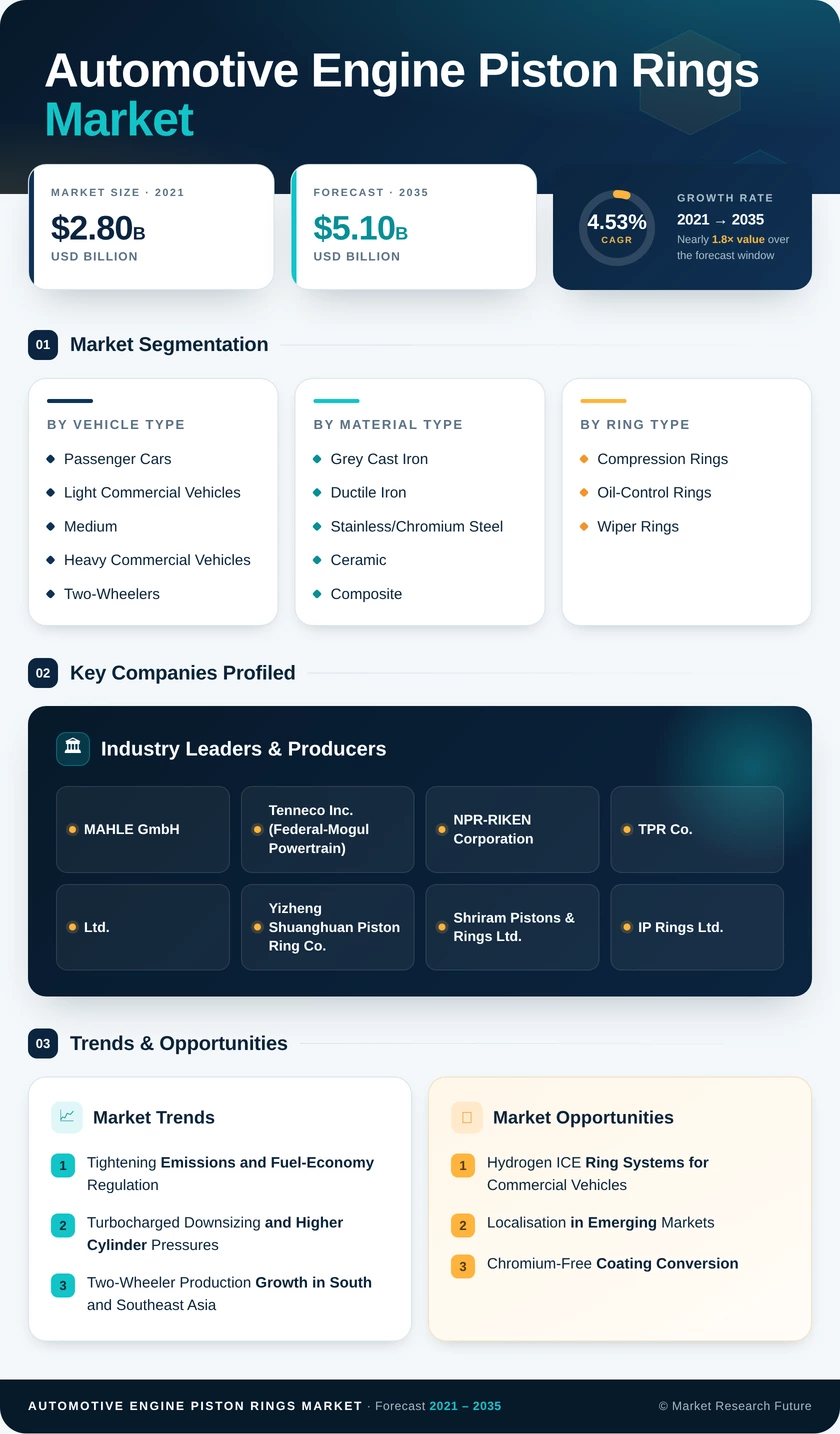
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Vehicle Type | Passenger Cars; Light Commercial Vehicles; Medium and Heavy Commercial Vehicles; Two-Wheelers | Passenger Cars — 60.3% (share, 2025) | Two-Wheelers — 8.5% (CAGR, 2026–2035) |
| By Material Type | Grey Cast Iron; Ductile Iron; Stainless/Chromium Steel; Ceramic and Composite | Grey Cast Iron — 49.9% (share, 2025) | Stainless/Chromium Steel — 7.8% (CAGR, 2026–2035) |
| By Ring Type | Compression Rings; Oil-Control Rings; Wiper Rings | Compression Rings — 63.6% (share, 2025) | Oil-Control Rings — 7.7% (CAGR, 2026–2035) |
| By Coating Technology | Chrome Plating; Molybdenum Spray; DLC and ta-C; Ceramic and Hybrid Nano-Coatings; Nitriding and Others | Chrome Plating — 37.6% (share, 2025) | DLC and ta-C — 8.1% (CAGR, 2026–2035) |
| By Fuel Type | Gasoline; Diesel; CNG/LPG; Hydrogen ICE | Gasoline — 61.2% (share, 2025) | Hydrogen ICE — 8.0% (CAGR, 2026–2035) |
| By Sales Channel | OEM; Aftermarket | OEM — 58.7% (share, 2025) | Aftermarket — 4.9% (CAGR, 2026–2035) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific — 46.8% (share, 2025) | Middle East & Africa — 5.9% (CAGR, 2026–2035) |
Market Segmentation Overview
By Vehicle Type
| Sub-Segment | Key Trend |
|---|---|
| Passenger Cars | Shift to PVD-coated stainless rings in turbo-gasoline and hybrid engines |
| Light Commercial Vehicles | Cost-focused cast-iron rings; low-friction upgrades in EU hybrid vans |
| Medium and Heavy Commercial Vehicles | Molybdenum and ceramic overlays for extended service intervals |
| Two-Wheelers | Chrome-plated ductile iron, with DLC-coated steel entering premium scooters |
Passenger cars lead this dimension with a 60.3% share because they account for most engines built worldwide and increasingly carry higher-value coated steel rings. Two-wheelers grow fastest at an 8.5% CAGR, driven by Asian scooter and motorcycle output and tightening Indian emission rules that favour better coatings. Medium and heavy commercial vehicles buy fewer but more durable ring packs.
By Material Type
| Sub-Segment | Key Trend |
|---|---|
| Grey Cast Iron | Remains the low-cost default in China, India, and Brazil |
| Ductile Iron | Thinner, stronger profiles for medium-duty diesels |
| Stainless/Chromium Steel | Rapid adoption in engines above 180 bar peak pressure |
| Ceramic and Composite | Early-stage use in hydrogen ICE research |
Grey cast iron holds a 49.9% share on cost and existing foundry capacity, particularly for aftermarket and emerging-market engines. Stainless/chromium steel grows fastest at a 7.8% CAGR because turbo-gasoline and hybrid engines need the tensile strength and low thermal expansion that iron cannot provide. Ductile iron occupies the middle ground for diesel applications.
By Ring Type
| Sub-Segment | Key Trend |
|---|---|
| Compression Rings | Barrel and taper profiles that shorten break-in |
| Oil-Control Rings | Three-piece expander designs for stable long-term tension |
| Wiper Rings | Durability and debris tolerance in diesel and off-highway engines |
Compression rings lead with a 63.6% share since every piston relies on them for gas sealing and heat transfer. Oil-control rings grow fastest at a 7.7% CAGR as Euro 7 and hydrogen engines demand far lower oil consumption. Wiper rings remain a stable, lower-growth line concentrated in diesel engines.
By Coating Technology
| Sub-Segment | Key Trend |
|---|---|
| Chrome Plating | Aftermarket stronghold under growing chromium regulation |
| Molybdenum Spray | Scuff resistance for heavy equipment |
| DLC and ta-C | Lowest friction and chromium-free compliance |
| Ceramic and Hybrid Nano-Coatings | Capacity additions for high-temperature uses |
| Nitriding and Others | Surface hardening for steel rings in Asian OEM supply |
Chrome plating leads with a 37.6% share because depreciated plating lines keep it cheapest for older vehicles. DLC and ta-C grow fastest at an 8.1% CAGR, cutting friction while sidestepping hexavalent chromium restrictions. Limited PVD capacity is the main brake on faster conversion from chrome.
By Fuel Type
| Sub-Segment | Key Trend |
|---|---|
| Gasoline | Turbo and hybrid engines lift ring value per unit |
| Diesel | Long-life ring packs for commercial and off-highway use |
| CNG/LPG | Scuff-resistant rings for hotter, drier combustion |
| Hydrogen ICE | Tight oil control and embrittlement-resistant materials |
Gasoline leads with a 61.2% share, covering most passenger cars, hybrids, and two-wheelers. Hydrogen ICE grows fastest at an 8.0% CAGR as heavy-duty OEMs use hydrogen combustion to meet EU zero-emission targets. Diesel remains a large value pool tied to commercial vehicles.
By Sales Channel
| Sub-Segment | Key Trend |
|---|---|
| OEM | Platform contracts specifying coated steel ring packs |
| Aftermarket | Rebuild demand from ageing fleets; price-led purchasing |
OEM supply leads with a 58.7% share through multi-year engine platform contracts. The aftermarket grows faster at a 4.9% CAGR as vehicle fleets age in North America, South America, and the Middle East & Africa, while new-engine output softens in electrifying markets.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA