Automotive Engine Piston Rings Market Summary
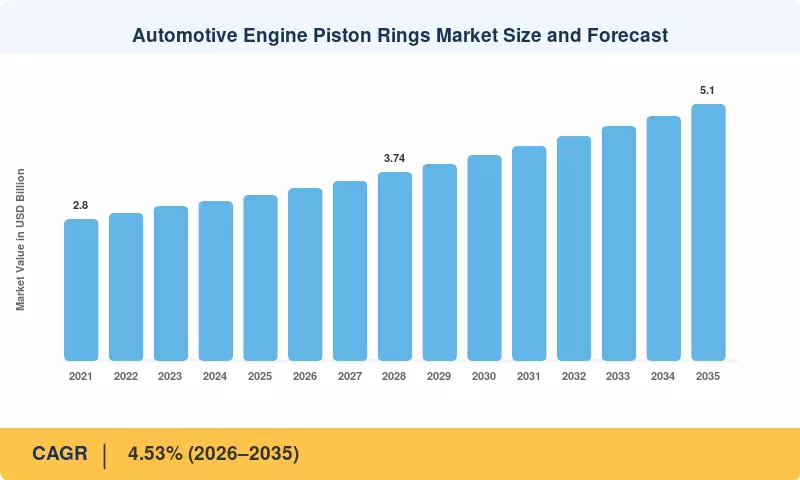
The global Automotive Engine Piston Rings Market was valued at USD 3.28 billion in 2025. It is projected to reach USD 3.42 billion in 2026 and USD 5.10 billion by 2035, a CAGR of 4.53% over 2026–2035. Two regulatory catalysts anchor the outlook. Euro 7, adopted in 2024, extends emission durability obligations for new cars to 200,000 km or 10 years [3]. The US EPA's standards for model years 2027–2032 cut fleet-average greenhouse gas emissions by roughly half [4]. Both rules reward rings that hold tension and control oil for longer.
Technology change is happening inside a component most vehicle buyers never see. Single-piece grey cast iron rings with hard chrome faces are giving way to steel rings with PVD and diamond-like carbon coatings. Three-piece oil-control assemblies and low-tension profiles are replacing older designs in downsized turbo engines that run combustion pressures above 180 bar. Hybrids keep this demand alive: Toyota alone sold about 4.1 million hybrid electric vehicles in 2024 [18], and each one carries a conventional ring pack.
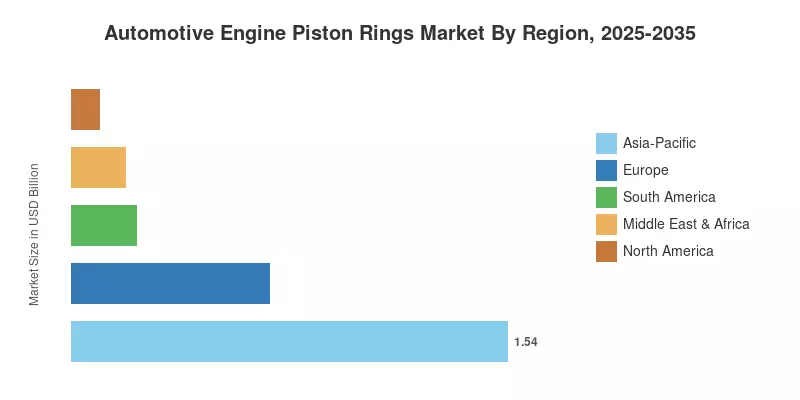
Asia-Pacific dominates with a 46.8% share in 2025, supported by engine output in China, India, and ASEAN. Middle East & Africa is the fastest-growing region at a 5.9% CAGR, driven by ageing fleets and new local vehicle assembly. Europe ranks second at USD 0.70 billion, where Euro 7 compliance is shifting spend toward premium coatings. Through 2035, ring value per engine should rise even as unit volumes plateau in electrifying markets.
Key Report Takeaways
• By Vehicle Type
- Passenger cars held a 60.3% share of the Automotive Engine Piston Rings Market in 2025, reflecting their weight in global engine output
- Two-wheelers are forecast to grow at an 8.5% CAGR through 2035 on high-volume scooter and motorcycle production in Asia
• By Material Type
- Grey cast iron retained a 49.9% share in 2025 on low cost and an entrenched foundry base
- Stainless/chromium steel is projected to post a 7.8% CAGR as turbo-gasoline and hybrid engines demand higher tensile strength
• By Ring Type
- Compression rings accounted for a 63.6% share in 2025, since every engine needs a robust gas seal
- Oil-control rings are set to grow at a 7.7% CAGR as particulate and oil-consumption limits tighten
• By Coating Technology
- Chrome plating led with a 37.6% share in 2025, anchored in the price-sensitive aftermarket
- DLC and ta-C coatings are forecast to expand at an 8.1% CAGR on friction and chromium-compliance advantages
• By Fuel Type
- Gasoline engines represented a 61.2% share of the Automotive Engine Piston Rings Market in 2025
- Hydrogen ICE rings are projected to record an 8.0% CAGR from a small base
• By Sales Channel
- OEM supply held a 58.7% share in 2025, tied to new engine production
- Aftermarket demand is expected to grow at a 4.9% CAGR as global vehicle fleets age
• By Region
- Asia-Pacific held a 46.8% share in 2025
- Middle East & Africa is forecast to grow at a 5.9% CAGR over 2026–2035
- Europe was valued at USD 0.70 billion in 2025
Market Size and Forecast (2021–2035)
Market Research Future sized the Automotive Engine Piston Rings Market with a bottom-up model. The model multiplies global engine production and the in-use vehicle parc by ring-pack content and average selling prices for each vehicle, material, and coating class. It then cross-checks the result against supplier revenue disclosures, OICA production data [2], and interviews with OEM purchasing and aftermarket distribution executives. Historical values are reconciled with reported output. Forecasts apply regional electrification, hybrid, and replacement-cycle assumptions.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


