Automotive Closure Market (2026 - 2035)

ID: MRFR/AT/4320-HCR 100 Pages Triveni Bhoyar Last Updated: September 10, 2026
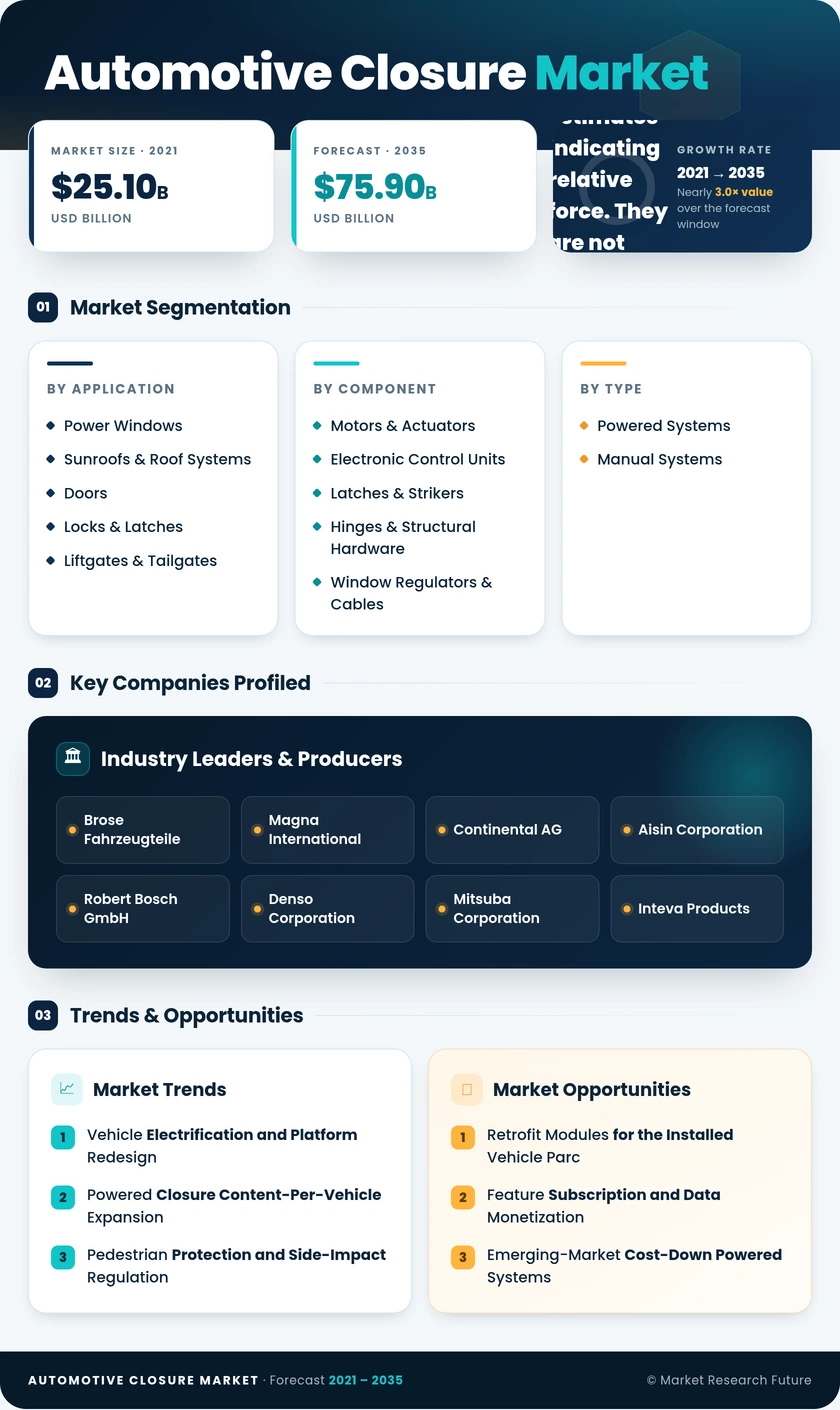
Automotive Closure Market Research Report By Application (Power Windows, Sunroofs & Roof Systems, Doors, Locks & Latches, Liftgates & Tailgates, Hoods, Fuel Filler & Charge Doors), By Component (Motors & Actuators, Electronic Control Units, Latches & Strikers, Hinges & Structural Hardware, Window Regulators & Cables, Sensors & Switches), By Type (Powered Systems, Manual Systems), By Vehicle Type (Passenger Cars, Sports Utility Vehicles (SUVs), Light Commercial Vehicles, Heavy Commercial Vehicles), By Distribution Channel (OEM, Aftermarket) - Forecast to 2035
Automotive Closure Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.3%
2025 Market SizeUSD 34.18 Billion
2035 Market SizeUSD 75.90 Billion
Key Players
Brose Fahrzeugteile
Magna International
Continental AG
Aisin Corporation
Robert Bosch GmbH
Denso Corporation
Opportunities
  • Retrofit Modules for the Installed Vehicle Parc
  • Feature Subscription and Data Monetization
  • Emerging-Market Cost-Down Powered Systems
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Report Takeaways | |
    1. 2.1 Takeaways by Technology | |
    2. 2.2 Takeaways by Sector | |
    3. 2.3 Takeaways by Geography | |
  3. 3 Global Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Drivers Analysis | |
    1. 4.1 Vehicle Electrification and Platform Redesign | |
    2. 4.2 Powered Closure Content-Per-Vehicle Expansion | |
    3. 4.3 Pedestrian Protection and Side-Impact Regulation | |
    4. 4.4 Software-Defined Vehicle and OTA Monetization | |
    5. 4.5 Lightweighting and Material Substitution | |
    6. 4.6 Premiumization of SUV and Crossover Interiors | |
    7. 4.7 Autonomous and Shared-Fleet Door Architectures | |
  5. 5 Market Restraints Analysis | |
    1. 5.1 OEM Cost-Down Pressure on Tier-1 Pricing | |
    2. 5.2 Cybersecurity Certification and Validation Cost | |
    3. 5.3 Warranty Exposure from Electromechanical Failure | |
    4. 5.4 Semiconductor and Rare-Earth Magnet Supply Risk | |
    5. 5.5 Entry-Segment Affordability Ceilings | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Retrofit Modules for the Installed Vehicle Parc | |
    2. 6.2 Feature Subscription and Data Monetization | |
    3. 6.3 Emerging-Market Cost-Down Powered Systems | |
    4. 6.4 Circular Materials and Recycled-Content Validation | |
    5. 6.5 Sensor-Integrated Access for Autonomous Fleets | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Closure Systems as Software Endpoints | |
    2. 8.2 The Electrification Supercycle | |
    3. 8.3 Circularity and Reporting Obligations | |
    4. 8.4 Autonomy Reshaping Access Design | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Application | | |
      1. 9.1.1 Power Windows | | |
      2. 9.1.2 Sunroofs & Roof Systems | | |
      3. 9.1.3 Doors, Locks & Latches | | |
      4. 9.1.4 Liftgates & Tailgates | | |
      5. 9.1.5 Hoods | | |
      6. 9.1.6 Fuel Filler & Charge Doors | |
    2. 9.2 By Component | | |
      1. 9.2.1 Motors & Actuators | | |
      2. 9.2.2 Electronic Control Units | | |
      3. 9.2.3 Latches & Strikers | | |
      4. 9.2.4 Hinges & Structural Hardware | | |
      5. 9.2.5 Window Regulators & Cables | | |
      6. 9.2.6 Sensors & Switches | |
    3. 9.3 By Type | | |
      1. 9.3.1 Powered Systems | | |
      2. 9.3.2 Manual Systems | |
    4. 9.4 By Vehicle Type | | |
      1. 9.4.1 Passenger Cars | | |
      2. 9.4.2 Sports Utility Vehicles (SUVs) | | |
      3. 9.4.3 Light Commercial Vehicles | | |
      4. 9.4.4 Heavy Commercial Vehicles | |
    5. 9.5 By Distribution Channel | | |
      1. 9.5.1 OEM | | |
      2. 9.5.2 Aftermarket | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Brose Fahrzeugteile | | |
      2. 10.3.2 Magna International | | |
      3. 10.3.3 Continental AG | | |
      4. 10.3.4 Aisin Corporation | | |
      5. 10.3.5 Robert Bosch GmbH | | |
      6. 10.3.6 Denso Corporation | | |
      7. 10.3.7 Mitsuba Corporation | | |
      8. 10.3.8 Inteva Products | | |
      9. 10.3.9 Valeo SA | | |
      10. 10.3.10 Pyeong Hwa Automotive | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Automotive Closure Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Automotive Closure Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Market Driver Impact Analysis – Global Automotive Closure Market | |
  18. TABLE 4 Market Restraint Impact Analysis – Global Automotive Closure Market | |
  19. TABLE 5 Global Automotive Closure Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Automotive Closure Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Automotive Closure Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Automotive Closure Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Automotive Closure Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Automotive Closure Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Automotive Closure Market Size, by Application, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Automotive Closure Market Size, by Component, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Automotive Closure Market Size, by Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Automotive Closure Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  29. TABLE 15 Global Automotive Closure Market Size, by Distribution Channel, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Automotive Closure Market Size, by Application, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Automotive Closure Market Size, by Component, 2021–2035 (USD Billion) | |
  32. TABLE 18 North America Automotive Closure Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Automotive Closure Market Size, by Application, 2021–2035 (USD Billion) | |
  34. TABLE 20 Europe Automotive Closure Market Size, by Component, 2021–2035 (USD Billion) | |
  35. TABLE 21 Europe Automotive Closure Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Automotive Closure Market Size, by Application, 2021–2035 (USD Billion) | |
  37. TABLE 23 Asia-Pacific Automotive Closure Market Size, by Component, 2021–2035 (USD Billion) | |
  38. TABLE 24 Asia-Pacific Automotive Closure Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  39. TABLE 25 South America Automotive Closure Market Size, by Application, 2021–2035 (USD Billion) | |
  40. TABLE 26 South America Automotive Closure Market Size, by Distribution Channel, 2021–2035 (USD Billion) | |
  41. TABLE 27 Middle East & Africa Automotive Closure Market Size, by Application, 2021–2035 (USD Billion) | |
  42. TABLE 28 Middle East & Africa Automotive Closure Market Size, by Distribution Channel, 2021–2035 (USD Billion) | |
  43. TABLE 29 US Automotive Closure Market Size, by Component, 2021–2035 (USD Billion) | |
  44. TABLE 30 China Automotive Closure Market Size, by Component, 2021–2035 (USD Billion) | |
  45. TABLE 31 India Automotive Closure Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  46. TABLE 32 Germany Automotive Closure Market Size, by Application, 2021–2035 (USD Billion) | |
  47. TABLE 33 Competitive Benchmarking Matrix – Global Automotive Closure Market, 2026 | |
  48. TABLE 34 Company Profiles – Key Players, Global Automotive Closure Market | |
  49. TABLE 35 Recent Developments & Strategic Announcements, 2023–2025 | |
  50. TABLE 36 Report Scope & Methodology Summary | |
  51. TABLE 37 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  52. FIGURE 1 Global Automotive Closure Market Dynamics – Drivers, Restraints, Opportunities | |
  53. FIGURE 2 Industry Value Chain Analysis – Automotive Closure Systems | |
  54. FIGURE 3 Porter's Five Forces Analysis – Global Automotive Closure Market | |
  55. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  56. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) | |
  57. FIGURE 6 Market Share by Application, 2025 vs 2035 (%) | |
  58. FIGURE 7 Market Share by Component, 2025 vs 2035 (%) | |
  59. FIGURE 8 Powered vs Manual Systems Share Evolution, 2021–2035 (%) | |
  60. FIGURE 9 Market Share by Vehicle Type, 2025 (%) | |
  61. FIGURE 10 OEM vs Aftermarket Channel Split, 2025 vs 2035 (%) | |
  62. FIGURE 11 Regional Market Share Distribution, 2025 (%) | |
  63. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) | |
  64. FIGURE 13 Asia-Pacific Country-Level Share Breakdown, 2025 (%) | |
  65. FIGURE 14 Europe Country-Level Share Breakdown, 2025 (%) | |
  66. FIGURE 15 Competitive Landscape – Estimated Revenue Share Ranges, 2026 | |
  67. FIGURE 16 Competitive Positioning Matrix – Capability vs Global Reach | |
  68. FIGURE 17 Content-Per-Vehicle Evolution by Powertrain Type, 2021–2035 (USD)

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ApplicationPower Windows; Sunroofs & Roof Systems; Doors, Locks & Latches; Liftgates & Tailgates; Hoods; Fuel Filler & Charge DoorsPower WindowsSunroofs & Roof Systems
By ComponentMotors & Actuators; Electronic Control Units; Latches & Strikers; Hinges & Structural Hardware; Window Regulators & Cables; Sensors & SwitchesMotors & ActuatorsElectronic Control Units
By TypePowered Systems; Manual SystemsPowered SystemsPowered Systems
By Vehicle TypePassenger Cars; Sports Utility Vehicles (SUVs); Light Commercial Vehicles; Heavy Commercial VehiclesPassenger CarsSports Utility Vehicles (SUVs)
By Distribution ChannelOEM; AftermarketOEMAftermarket
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Application

Sub-SegmentKey Trend
Power WindowsUniversal fitment sustains volume; value shifts to quieter, lower-current motor designs.
Sunroofs & Roof SystemsPanoramic and switchable-tint glass raise unit value sharply in China and premium Europe.
Doors, Locks & LatchesElectronic actuation and cybersecurity certification redefine supplier qualification.
Liftgates & TailgatesPowered operation migrating from optional to standard on volume SUV trims
HoodsDeployable pedestrian protection systems add actuator and sensor content.
Fuel Filler & Charge DoorsCharge-port actuation and locking emerge as distinct EV-specific requirements


Application mix is the clearest indicator of where revenue is heading. Windows and doors deliver the volume base, but roof systems and liftgates deliver the margin, because both command higher unit values and both are still climbing their adoption curves in major markets.

By Component

Sub-SegmentKey Trend
Motors & ActuatorsBrushless designs and ferrite alternatives reduce rare-earth dependency
Electronic Control UnitsConsolidation into zonal controllers running certified, updatable firmware
Latches & StrikersElectronic release with mechanical redundancy becomes the default architecture.
Hinges & Structural HardwareAluminum and composite door structures drive redesign and material qualification.
Window Regulators & CablesMature, cost-competitive category with incremental weight and noise improvements
Sensors & SwitchesAnti-pinch, approach detection, and obstacle sensing expand per-opening content.


Component economics increasingly favor suppliers who span both mechanical and electronic domains. A firm supplying only hinges competes on cost; a firm supplying the actuator, the controller, and the firmware competes on system performance and captures a materially larger share of program value.

By Type

Sub-SegmentKey Trend
Powered SystemsStandard-fit migration down the trim ladder across all major regions
Manual SystemsPersistent in entry-price passenger vehicles and commercial fleet applications


Type segmentation captures the market's central transition. Powered content grows through both new fitment and richer specification per opening, while manual hardware sustains a stable niche wherever price sensitivity outweighs convenience expectations.

By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsLargest volume base; content growth driven by trim-level upgrades
Sports Utility Vehicles (SUVs)Highest content per vehicle through liftgates, panoramic roofs, premium hardware
Light Commercial VehiclesDelivery fleet growth drives sliding-door durability and rapid-access specification
Heavy Commercial VehiclesCab access ergonomics and extended-life durability requirements


Vehicle mix explains regional revenue divergence better than production volume alone. Two markets building identical unit counts can differ by 40% in closure revenue purely on body-style mix and trim specification.

By Distribution Channel

Sub-SegmentKey Trend
OEMMulti-year platform contracts with growing software and service components
AftermarketRetrofit connectivity modules and replacement actuators serve an ageing vehicle parc


Channel dynamics reward different capabilities. Original equipment supply demands validation depth and capital scale; aftermarket success depends on distribution reach and installation simplicity, which lets smaller specialists compete profitably without winning a single platform award.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.