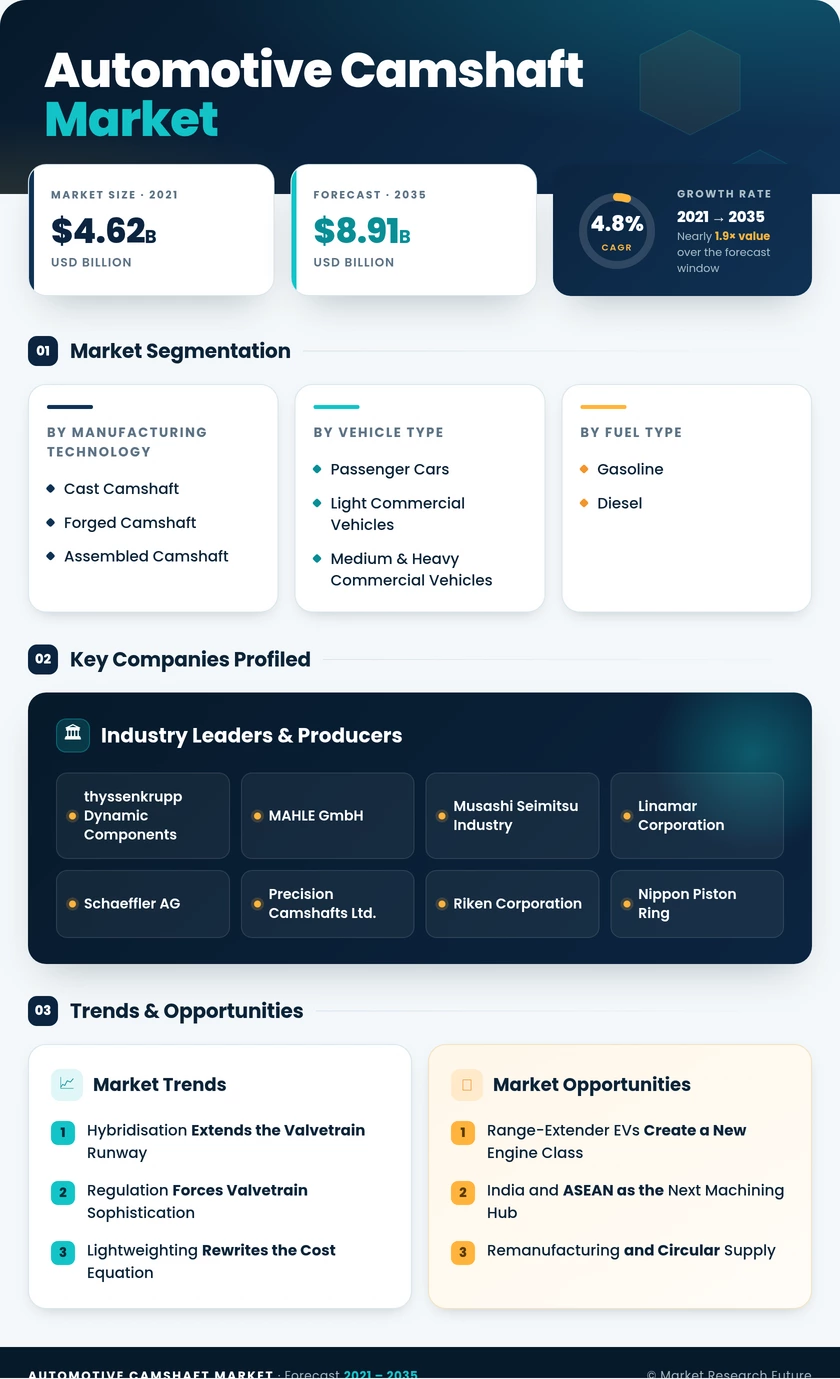
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| Manufacturing Technology | Cast Camshaft; Forged Camshaft; Assembled Camshaft | Cast Camshaft | Assembled Camshaft |
| Vehicle Type | Passenger Cars; Light Commercial Vehicles; Medium & Heavy Commercial Vehicles | Passenger Cars | Light Commercial Vehicles |
| Fuel Type | Gasoline; Diesel | Gasoline | Gasoline |
| Sales Channel | OEM; Aftermarket | OEM | Aftermarket |
| Geography | North America; South America; Europe; Asia-Pacific; Middle East & Africa | Asia-Pacific | South America |
Market Segmentation Overview
By Manufacturing Technology
| Sub-Segment | Key Trend |
| Cast Camshaft | Remains the cost benchmark for high-volume gasoline engines; chilled iron and ductile iron grades diverging by application |
| Forged Camshaft | Anchored in diesel and heavy-duty where bending loads rule out hollow construction; steady rather than spectacular |
| Assembled Camshaft | Fastest expansion as hollow tube plus press-fitted lobes cuts rotating mass and enables integrated actuator packaging |
Technology mix is shifting faster in Europe and Japan than anywhere else, driven by mass-reduction targets and hybrid refinement requirements. Cast construction will still ship the most units in 2035, but assembled will capture a disproportionate share of incremental value.
By Vehicle Type
| Sub-Segment | Key Trend |
| Passenger Cars | Largest base by volume; hybrid programmes offset battery-electric substitution through the early 2030s |
| Light Commercial Vehicles | High-mileage delivery fleets sustain both original equipment and replacement demand |
| Medium & Heavy Commercial Vehicles | Least exposed to electrification near-term; premium forged content per engine |
Passenger cars carry the volume story while commercial vehicles carry the durability story. Fleet operators renewing on five-to-seven-year cycles create a more predictable order book than retail demand.
By Fuel Type
| Sub-Segment | Key Trend |
| Gasoline | Benefits from hybrid pairing and Atkinson-cycle profile complexity |
| Diesel | Retreating in passenger cars but entrenched in freight, agriculture, and marine auxiliaries |
Gasoline extends its lead as diesel exits European light vehicles. The diesel base that remains is higher-value, since heavy-duty applications specify forged shafts with tighter metallurgical requirements.
By Sales Channel
| Sub-Segment | Key Trend |
| OEM | Contract-driven, price-down pressure annually, tied directly to engine production volumes |
| Aftermarket | Higher margin, insulated from new-vehicle electrification, growing with parc age |
Channel economics diverge sharply. OEM business builds scale and credibility; aftermarket business builds cash. Suppliers positioning for the 2030s are deliberately rebalancing toward the latter.
By Geography
| Sub-Segment | Key Trend |
| North America | Nearshoring under USMCA content rules; strong performance and replacement channel |
| South America | Fastest growth on flex-fuel engine specificity and Rota 2030 localisation incentives |
| Europe | Technology leadership in assembled construction, offset by early battery-electric substitution |
| Asia-Pacific | Largest regional base; China volume risk balanced by India and ASEAN expansion |
| Middle East & Africa | Small base, import-substitution policy creating first local machining capability |
Geographic strategy now hinges on matching electrification timing to asset life. Investing in a new grinding line in Western Europe demands a different payback assumption than the same line in Chennai or Saltillo.
just now
Opus 5 High

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA