Automotive Camshaft Market (2026 - 2035)

Automotive Camshaft Market Research Report By Manufacturing Technology (Cast Camshaft, Forged Camshaft, Assembled Camshaft), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Medium & Heavy Commercial Vehicles), By Fuel Type (Gasoline, Diesel), By Sales Channel (OEM, Aftermarket) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/AT/10056-HCR
100 Pages
Shubham Munde, Garvit Vyas
Last Updated: August 28, 2026
Automotive Camshaft Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.8%
2025 Market SizeUSD 5.58 Billion
2035 Market SizeUSD 8.91 Billion
Key Players
thyssenkrupp Dynamic Components
MAHLE GmbH
Musashi Seimitsu Industry
Linamar Corporation
Schaeffler AG
Precision Camshafts Ltd.
Opportunities
  • Range-Extender EVs Create a New Engine Class
  • India and ASEAN as the Next Machining Hub
  • Remanufacturing and Circular Supply

Automotive Camshaft Market Summary

The Automotive Camshaft Market was valued at USD 5.58 Billion in 2025 and opens its forecast window at USD 5.85 Billion in 2026, climbing to USD 8.91 Billion by 2035 at a 4.8% CAGR. That trajectory surprises people who assume the internal combustion engine is already finished. It is not. Hybrid mandates under the EU's revised CO2 framework and the U.S. EPA's 2027–2032 light-duty rules [1][3] keep valvetrain content in production for at least another two decades, and hybrid engines demand more precise cam profiles, not fewer.

Hollow assembled shafts with sintered lobes press-fitted onto thin-wall tubes are consistently gaining ground over chilled cast iron blanks, which are cheap, heavy, and forgiving. This process reduces the rotating mass by 30–40% per unit. Since 2022, thyssenkrupp has allocated more than EUR 250 million to the expansion of its assembled-shaft and camshaft phaser VCT actuator capacity in its European and Chinese plants [12]. Consequently, the Automotive Camshaft Market is consolidating around a smaller number of suppliers who are more capital-intensive.

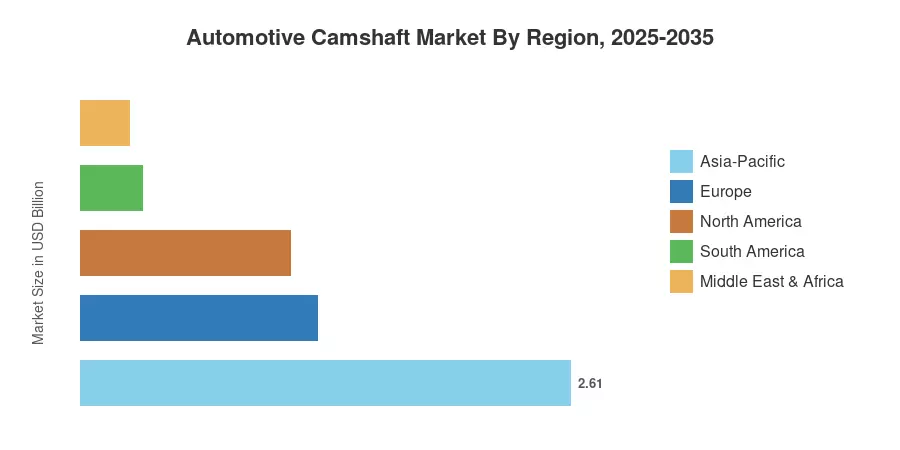
Based on India's rapidly expanding engine plants and China's 26-million-unit annual output, the Asia-Pacific region anchors global demand with a 46.8% share [5][6]. Brazil's Rota 2030 incentives have drawn powertrain manufacturing back onshore, resulting in South America's fastest growth rate of approximately 6.0% CAGR. Premium DOHC programs are the primary defense of Europe's second-place position, which amounts to USD 1.26 billion. Through 2035, anticipate that the Automotive Camshaft Market will prioritize precision over volume.


Key Report Takeaways

• By Technology

  • Cast camshafts hold 52.4% of the Automotive Camshaft Market in 2025, still the default for high-volume gasoline blocks
  • Assembled camshafts post the strongest segment growth at 7.1% CAGR through 2035
  • Forged camshafts generate USD 1.77 billion in 2025 revenue, concentrated in diesel and heavy-duty.


• By Vehicle

  • Passenger cars account for 63.5% of global demand.
  • Light commercial vehicles expanded at 5.9% CAGR on last-mile delivery fleet renewal.


• By Sales Channel

  • The aftermarket channel is worth USD 1.53 billion in 2025, buoyed by a 12.6-year average vehicle age in the U.S.

• By Region

  • Asia-Pacific commands 46.8% of the Automotive Camshaft Market
  • South America is the fastest-growing region at 6.0% CAGR
  • North America contributes USD 1.12 Billion in 2025


Market Size and Forecast (2021–2035)

Figures below blend OICA and national registration data, engine-plant capacity audits across 140 machining facilities, supplier revenue disaggregation from annual filings, and 46 primary interviews with powertrain purchasing leads. Volume-to-value bridges use regional average selling prices adjusted for alloy content and finishing operations. Historical years are actuals; 2026 onward is modelled.
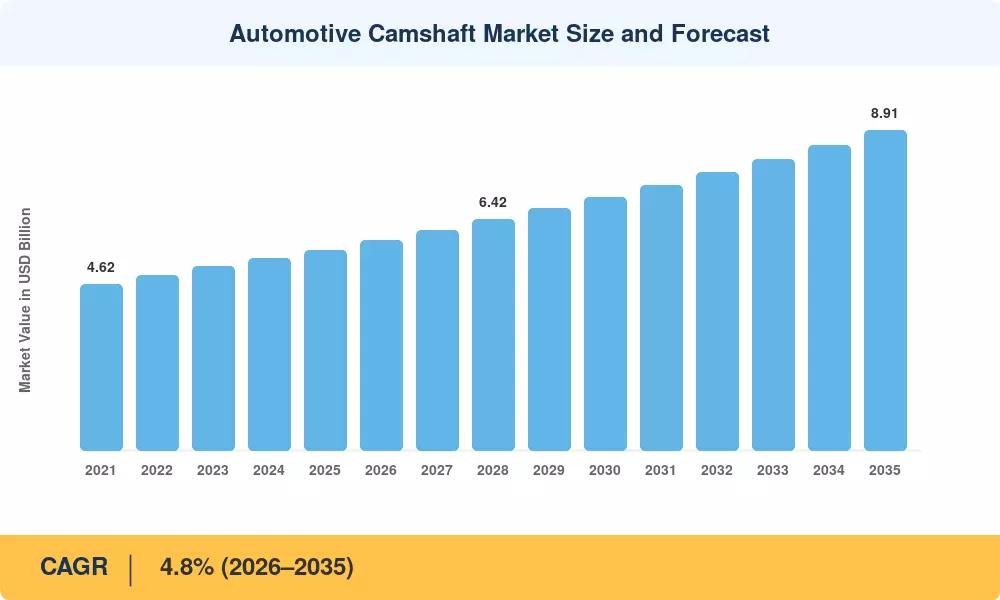
Automotive Camshaft Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Hybrid powertrain expansion sustaining ICE valvetrain content +0.9 Global Medium-term (2–4 yr)
Tightening CO2 and fuel-economy regulation +0.8 Europe, North America, China Short-term (≤2 yr)
Lightweighting via hollow and assembled shaft designs +0.6 Europe, Japan Medium-term (2–4 yr)
Commercial vehicle fleet renewal in emerging economies +0.5 Asia-Pacific, South America Long-term (≥4 yr)
Aftermarket demand from an ageing vehicle parc +0.5 North America, Europe, Brazil Short-term (≤2 yr)
Localization of precision machining capacity +0.4 India, Mexico, ASEAN Long-term (≥4 yr)
Performance and motorsport rebuild demand +0.3 North America Medium-term (2–4 yr)


Hybridisation Extends the Valvetrain Runway

Hybrids are the single best thing that has happened to the Automotive Camshaft Market this decade. The IEA counted 5.3 million plug-in hybrid sales globally in 2024, roughly 30% of all electrified vehicles [2], and every one of them still carries a combustion engine tuned for Atkinson or Miller cycle operation. Those cycles depend on aggressive late-intake-valve-closing profiles that only a purpose-ground cam can deliver. Toyota's fifth-generation hybrid system, launched across the Prius and Camry lines, uses a dedicated intake profile with 42% more duration than the equivalent conventional engine [14].

Regulation Forces Valvetrain Sophistication

Euro 7, adopted in 2024 with phase-in from November 2026, holds NOx limits flat but extends compliance to 200,000 km — double the previous durability window [1]. Meeting that on a gasoline engine means tighter cold-start control, which in turn means variable valve timing on both cams rather than one. The EPA's parallel MY2027–2032 rule projects an industry compliance cost of USD 1,200 per vehicle, with roughly 8% attributable to valvetrain and air-handling upgrades [3].

Lightweighting Rewrites the Cost Equation

Weight reduction has moved from nice-to-have to contractual. A hollow assembled shaft removes 700–900 grams per engine versus a solid cast unit, and at the EUR 3–5 per kilogram shadow price European OEMs apply to mass, the business case closes even at a 25% higher piece price [12]. Mahle reported that its assembled camshaft line at Rottweil reached 92% capacity utilisation in 2024 [13].

The Replacement Parc Keeps Paying

Vehicles are lasting longer everywhere. Put the average U.S. light-vehicle age at 12.6 years in 2024, a record. Brazil's parc averages 11.2 years, and Rota 2030 tax credits explicitly favour domestically machined replacement components [9].


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Battery-electric penetration eliminating valvetrains entirely −1.4 Europe, China, North America Long-term (≥4 yr)
Engine downsizing reducing lobes per vehicle −0.6 Global Medium-term (2–4 yr)
Alloy steel and chromium price volatility −0.4 Global Short-term (≤2 yr)
OEM in-house vertical integration of machining −0.3 Japan, Germany Medium-term (2–4 yr)
Stranded capital in cast iron foundry capacity −0.3 Europe, North America Long-term (≥4 yr)


Electrification Is the Structural Ceiling

No amount of hybrid enthusiasm changes the endpoint. The IEA's Stated Policies Scenario has battery-electric vehicles at 40% of global new sales by 2030 [2], and a BEV contains zero camshafts. Europe feels this first: EU new-car BEV share reached 15.4% in 2024 and Norway effectively completed the transition [1]. Suppliers with more than 70% revenue exposure to pure-ICE programmes face a genuine terminal-value problem, which is why Schaeffler and thyssenkrupp both restructured their powertrain divisions in 2024.

Fewer Cylinders, Fewer Lobes

Downsizing quietly removes content. A three-cylinder replacing a four-cylinder deletes four lobes and shortens both shafts by roughly 25%. Three-cylinder engines reached 21% of European gasoline production in 2024, up from 12% in 2019 [4].

Input Cost Whiplash

Chromoly bar stock and ferroalloy prices swung more than 35% peak-to-trough between 2022 and 2024 [10]. Camshaft contracts typically run three to five years with annual price-down clauses, leaving suppliers absorbing much of the variance.


Automotive Camshaft Market Opportunities

Range-Extender EVs Create a New Engine Class

Range-extender architectures — a small, constant-speed engine driving a generator — are gaining traction in China, where they made up 31% of new energy vehicle sales in 2024 [6]. These engines run in narrow load bands, which lets designers specify simpler, single-profile cams optimised purely for thermal efficiency. That is a lower-cost, higher-margin part than a full VVT assembly, and it opens a segment nobody modelled five years ago.

India and ASEAN as the Next Machining Hub

India produced 6.0 million passenger vehicles in FY2025 and the Production Linked Incentive scheme for auto components has approved over USD 3.5 billion in disbursements [7]. Precision Camshafts and Musashi have both added grinding capacity in Maharashtra and Tamil Nadu, targeting export supply to Europe at 20–25% landed cost advantage.

Remanufacturing and Circular Supply

Reground and renitrided camshafts carry 60–70% lower embodied carbon than new units, and EU End-of-Life Vehicle regulation revisions proposed in 2023 push OEMs toward certified remanufactured parts [1]. Independent remanufacturers in Poland and Mexico are scaling fast.

Data-Attached Service Models

Grinding lines now generate lobe-profile telemetry on every part. Suppliers are beginning to sell that data back to OEMs as a warranty-defence and predictive-quality service, priced per program rather than per piece. Two European Tier-1s piloted such contracts in 2025, an early sign the Automotive Camshaft Market can monetise something beyond steel.

Heavy-Duty and Off-Highway Resilience

Class 8 trucks, agricultural equipment, and marine auxiliaries will run diesel well past 2040. Forged camshafts for these applications carry premium pricing and face almost no electrification threat before the mid-2030s.


Automotive Camshaft Market Future Outlook

Precision Manufacturing Meets Machine Learning

Grinding lines are becoming self-correcting. Closed-loop systems that measure lobe profile in-process and adjust wheel dress compensation in real time have cut scrap rates by 40–55% at early adopters [13]. Over the forecast decade this shifts competitive advantage in the Automotive Camshaft Market from labour cost to process data maturity, favouring suppliers who instrumented their plants before 2025.

Contract Economics Shift Toward Modules

Buyers increasingly want a complete valvetrain module — shaft, phaser, bearing frame, and cover — from one source. Module contracts carry 15–20% higher content per engine but demand assembly capability most pure grinders lack. Expect consolidation as mid-tier machining houses either partner upward or exit.

The Hybrid Plateau, Then the Decline

Global ICE and hybrid engine production peaks around 2029 at roughly 78 million units before declining toward 62 million by 2035 under IEA policy scenarios [2]. Value holds up better than volume because content per engine keeps rising. Suppliers who assume flat unit demand will be wrong; those who assume flat revenue may be right.

Carbon Accounting Becomes a Purchase Criterion

CBAM reporting obligations became binding for EU importers in 2026, and cast iron camshafts imported from coal-heavy grids now carry a measurable duty [1]. Electric arc furnace steel and remanufactured units gain a pricing edge. Over the decade, the Automotive Camshaft Market will price embodied carbon the way it once priced hardness specifications.


Automotive Camshaft Market Segmentation

Segment structure in the Automotive Camshaft Market follows Mordor's established taxonomy across manufacturing technology, vehicle type, fuel type, and sales channel.

By Manufacturing Technology

Segment Metric Primary Demand Driver
Cast Camshaft 52.4% share Low unit cost for high-volume gasoline engines
Forged Camshaft USD 1.77 Billion Diesel and heavy-duty load requirements
Assembled Camshaft 7.1% CAGR Mass reduction and integrated phaser packaging


Cast remains the volume workhorse and will stay so through 2035. Chilled cast iron with induction-hardened lobes costs 30–40% less than a comparable assembled unit and satisfies most naturally aspirated applications. Assembled is where growth concentrates: hollow tube construction with press-fitted sintered lobes cuts rotating inertia enough to measurably improve start-stop refinement, which matters intensely in hybrids. European premium OEMs already specify assembled construction on more than half of new engine programmes [12].

By Vehicle Type

Segment Metric Primary Demand Driver
Passenger Cars 63.5% share Global fleet volume, hybrid programme launches
Light Commercial Vehicles 5.9% CAGR E-commerce delivery fleet expansion
Medium & Heavy Commercial Vehicles USD 0.85 Billion Long-haul freight, minimal electrification near-term


Light commercial vehicles deserve more attention than they get. Delivery van registrations in Europe grew 8.4% in 2024 [4], and these vehicles run high annual mileage, which drives both original equipment and replacement demand.

By Fuel Type

Segment Metric Primary Demand Driver
Gasoline 61.7% share Hybrid pairing, global passenger car dominance
Diesel USD 2.14 Billion Commercial vehicle and off-highway durability needs


By Sales Channel

Segment Metric Primary Demand Driver
OEM 72.6% share New engine production contracts
Aftermarket 6.3% CAGR Ageing vehicle parc, performance rebuilds


Aftermarket margins run roughly double OEM levels, and the channel is far more resilient to electrification because it serves the installed base rather than new production[17].


Regional Market Share Analysis

Region 2025 Metric Primary Investment Themes
Asia-Pacific 46.8% share Capacity localisation, hybrid engine programmes
Europe USD 1.26 Billion Assembled-shaft conversion, Euro 7 compliance
North America 20.1% share Aftermarket distribution, performance segment
South America 6.0% CAGR Rota 2030 onshoring, flex-fuel engines
Middle East & Africa USD 0.26 Billion Replacement parts import substitution
Total USD 5.58 Billion

Regional performance in the Automotive Camshaft Market tracks engine production geography almost exactly, with one twist: aftermarket intensity redistributes value toward older parcs in Brazil, Russia, and the U.S. Midwest.


North America

Country Metric Key Driver
US 68.0% of region Truck and SUV engine volumes, performance aftermarket
Canada USD 0.13 Billion Linamar machining footprint in Ontario
Mexico 5.9% CAGR Tier-1 nearshoring under USMCA rules of origin


Pickup trucks keep this region unusually cam-intensive. The Ford 5.0-litre and GM small-block V8 families each consume four camshafts per engine, and both were confirmed for production through at least 2031 [15]. USMCA's 75% regional value content threshold has pulled grinding and induction-hardening work from Asia into Querétaro and Saltillo, with more than USD 900 million in announced powertrain machining investment across 2023–2025 [16].

Europe

Country Metric Key Driver
Germany 27.0% of region Premium DOHC programmes, thyssenkrupp and Mahle capacity
UK USD 0.16 Billion Engine exports, motorsport supply chain
France 3.9% CAGR Stellantis hybrid engine families
Italy 9.8% of region Commercial vehicle diesel engines
Spain USD 0.11 Billion High-volume small-car engine plants
Nordic Countries 2.6% of region Marine and off-highway applications
Russia 4.1% CAGR Domestic aftermarket substitution
Rest of Europe USD 0.14 Billion Central European machining clusters


Germany's position rests on process technology rather than volume. The country hosts the majority of global assembled-shaft joining capacity, and its suppliers export finished modules to China and Mexico. Euro 7's extended durability requirement plays to that strength, since assembled shafts hold profile tolerance better over 200,000 km than chilled cast iron [1][12].

Asia-Pacific

Country Metric Key Driver
China 41.5% of region World's largest engine output, range-extender growth
India 6.4% CAGR PLI scheme, export machining contracts
Japan USD 0.47 Billion Hybrid engine leadership, Musashi and Riken
South Korea 8.2% of region Hyundai-Kia Smartstream engine families
ASEAN 5.5% CAGR Thailand pickup production, Indonesia assembly
Rest of Asia-Pacific USD 0.15 Billion Aftermarket and two-wheeler crossover demand


China dominates the Automotive Camshaft Market by volume but is also its biggest long-term risk, since domestic BEV share passed 45% of new sales in 2025 [6]. Range-extenders soften the blow. India offers cleaner upside: engine production is still growing in absolute terms, and the PLI scheme's USD 3.5 billion disbursement pool explicitly targets precision machining exports [7].

South America

Country Metric Key Driver
Brazil 58.0% of region Rota 2030 incentives, flex-fuel engine platforms
Argentina USD 0.06 Billion Pickup production for regional export
Rest of South America 5.2% CAGR Ageing parc replacement demand


Brazil's flex-fuel fleet is the structural reason this region grows fastest. Ethanol's higher octane permits more aggressive cam timing, and engines calibrated for E100 operation require dedicated profiles rather than shared global parts [9]. Rota 2030 grants tax credits worth up to 10.2% of qualifying R&D and local content spend, and Volkswagen, Stellantis, and Toyota have all cited it in Brazilian powertrain investment announcements since 2023.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 24.0% of region Vision 2030 automotive localisation
UAE USD 0.05 Billion Re-export hub for replacement parts
South Africa 4.6% CAGR Established OEM assembly base
Egypt 11.0% of region Local assembly incentive programme
Rest of MEA USD 0.06 Billion Commercial fleet maintenance demand


South Africa remains the only country in the region with genuine engine machining capability, supplying BMW and Mercedes-Benz local plants alongside exports [20]. Saudi Arabia's Vision 2030 targets 300,000 units of annual vehicle assembly by 2030, which would create the first meaningful Gulf demand for locally sourced powertrain components.


Automotive Camshaft Market By Region, 2025-2035

Competitive Benchmarking

Concentration sits in the moderate band. The estimated HHI falls between 780 and 900, with the top five suppliers holding roughly 35–42% of global revenue. Below that tier, hundreds of regional machining houses serve local OEMs and the aftermarket, which keeps the long tail unusually fat. Barriers to entry are real but not insurmountable — a competitive grinding cell costs USD 4–6 million — while barriers to winning global platform business are much higher, requiring metallurgical labs, PPAP capability, and multi-continent footprint.

Company Est. Revenue Share Range Key Offerings for Automotive Camshaft Market Strategic Positioning
thyssenkrupp Dynamic Components ~9–12% Assembled camshafts, valvetrain modules, phaser integration Technology leader in hollow-shaft joining
MAHLE GmbH ~7–10% Cast and assembled camshafts, complete valvetrain systems Broad powertrain portfolio, hybrid-focused pivot
Musashi Seimitsu Industry ~6–9% Forged and machined camshafts, gear components Japanese OEM alignment, India expansion
Linamar Corporation ~5–8% Precision machined camshafts, engine components North American nearshoring beneficiary
Schaeffler AG ~4–7% Phasers, cam-in-cam systems, valvetrain assemblies Systems supplier with strong VVT IP
Precision Camshafts Ltd. ~4–6% Chilled cast iron and ductile iron camshafts Low-cost export base from India
Riken Corporation ~3–5% Cast camshafts, piston rings, sintered components Materials science depth in sintered lobes
Nippon Piston Ring ~3–5% Assembled camshafts, sintered lobe technology Sintering specialist, Japan and ASEAN
Melling Engine Parts ~2–4% Aftermarket and performance camshafts Independent aftermarket channel strength
COMP Performance Group ~2–4% Performance and racing camshaft profiles Motorsport and enthusiast niche leadership


Recent News & Developments

  • thyssenkrupp Dynamic Components (March 2024): Opened an expanded assembled camshaft line in Hungary serving European premium OEMs, adding capacity for approximately 2.5 million units annually [12]
  • European Commission (November 2024): Confirmed Euro 7 phase-in dates with extended 200,000 km durability requirements, raising valvetrain specification thresholds across gasoline programmes [1]
  • Musashi Seimitsu (June 2024): Announced a new precision machining facility in Tamil Nadu targeting export supply to European and North American customers [7]
  • MAHLE GmbH (September 2023): Restructured its powertrain division into a dedicated hybrid components unit, retaining camshaft operations under a growth mandate [13]
  • Linamar Corporation (February 2025): Secured a multi-year contract for machined valvetrain components supporting a North American hybrid truck programme [16]
  • Precision Camshafts (August 2024): Commissioned additional ductile iron casting capacity in Solapur, India, expanding export volumes by an estimated 18% [7]
  • U.S. EPA (April 2024): Finalised MY2027–2032 light-duty greenhouse gas standards, preserving a substantial hybrid pathway to compliance [3]
  • Schaeffler AG (January 2025): Completed integration of Vitesco Technologies, consolidating phaser and actuator portfolios under one powertrain organisation [18]


Automotive Camshaft Market Report Scope

Parameter Detail
Market Scope Global automotive camshafts across manufacturing technology, vehicle type, fuel type, sales channel, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 4.8% (2026–2035)
Market Size Checkpoints USD 5.58 Billion (2025); USD 5.85 Billion (2026); USD 7.05 Billion (2030); USD 8.91 Billion (2035)
Fastest Growing Segments Assembled Camshaft (technology); Light Commercial Vehicles (vehicle type); Aftermarket (channel); South America (region)
Companies Profiled 10 leading suppliers spanning OEM and aftermarket channels
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

How should procurement teams evaluate supplier risk in the Automotive Camshaft Market?
Weight terminal-value exposure heavily. Suppliers with over 70% pure-ICE revenue face restructuring risk within the contract term. Ask for hybrid and off-highway revenue splits before awarding multi-year business [12].
What tolerance specifications separate premium suppliers from commodity grinders?
Lobe profile accuracy below 8 microns and journal roundness under 3 microns mark the premium tier. Most regional grinders hold 15–20 microns, adequate for aftermarket but not modern OEM programmes [13].
Is the Automotive Camshaft Market attractive for private equity entry?
Selectively. Aftermarket and off-highway assets offer resilient cash flows with limited electrification exposure. Pure OEM light-vehicle machining carries a genuine terminal-value discount [17].
How does ethanol fuel change camshaft design requirements?
Higher octane permits more aggressive timing and increased overlap. Brazilian flex-fuel engines therefore need dedicated profiles rather than shared global parts, which raises tooling costs but protects local suppliers [9].
What integration challenges arise when converting from cast to assembled construction in the Automotive Camshaft Market?
Joining process validation is the bottleneck. Thermal or hydroforming interference fits require new metallurgical qualification and typically add nine to twelve months to programme timing [12].
Which certifications matter most for cross-border camshaft supply?
IATF 16949 is table stakes. CBAM carbon reporting readiness now determines EU import economics, and suppliers without verified emissions data face duty exposure from 2026 [1].
Do remanufactured camshafts meet original equipment durability standards?
Properly reground and renitrided units restore full surface hardness and typically match new-part fatigue life. Acceptance depends on base-material thickness remaining after grinding, which limits reuse to roughly two cycles [1].    
Author
Author
Author Profile
Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author
Co-Author Profile
Garvit Vyas LinkedIn Vice President - Operations
Garvit Vyas is a Research Analyst with experience in working across multiple industry domains in the market research sector. Over the past four years, he has been actively involved in analyzing diverse markets, gathering industry insights, and contributing to the development of comprehensive research reports. His work includes studying market trends, evaluating competitive landscapes, and supporting data-driven business insights. In the early phase of his career, Garvit worked on cross-domain research projects, which helped him build a strong foundation in market analysis, data interpretation, and industry intelligence across various sectors. Later, he transitioned into the Quality Control (QC) function, where he focuses on reviewing and refining research reports and marketing collaterals to ensure accuracy, consistency, and high editorial standards. His responsibilities include validating research data, improving report structure, and maintaining the overall quality of published content. Garvit is committed to maintaining strong research integrity and delivering reliable insights that support informed business decision-making.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, automotive industry publications, peer-reviewed engineering journals, technical standards documentation, and authoritative transportation organizations. Key sources included the US Environmental Protection Agency (EPA), National Highway Traffic Safety Administration (NHTSA), US Department of Transportation (DOT), European Automobile Manufacturers' Association (ACEA), Japan Automobile Manufacturers Association (JAMA), Society of Automotive Engineers (SAE International), International Organization for Standardization (ISO), Organisation Internationale des Constructeurs d'Automobiles (OICA), International Energy Agency (IEA), World Economic Forum (WEF) - Future of Mobility, EU European Environment Agency, China Association of Automobile Manufacturers (CAAM), India Society of Indian Automobile Manufacturers (SIAM), and national automotive ministry reports from key manufacturing markets.

Vehicle production statistics, data on compliance with emission regulations, material technology studies, engine efficiency benchmarks, and an analysis of the competitive landscape for cast, forged, assembled, and variable valve timing technologies were all gathered from these sources.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Manufacturing Operations, R&D directors, and procurement directors from tier-1 and tier-2 camshaft producers, automakers, and suppliers of engine parts were examples of supply-side sources. Chief engineers, powertrain directors, vehicle program managers, and sourcing leads from large automakers, commercial vehicle manufacturers, and aftermarket distributors were examples of demand-side suppliers. Primary research verified production capacity expansion schedules, validated market segmentation across product kinds (cast, forged, and assembled), and acquired information on supply chain dynamics, material adoption trends, and lightweighting tactics.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (29%), Asia-Pacific (34%), Rest of World (5%)


Market Size Estimation

production volume mapping and revenue analysis across OEM and aftermarket channels were used to determine the global market valuation. The methodology comprised:

Finding more than fifty-five major manufacturers in North America, Europe, Asia-Pacific, and Latin America

Product mapping for camshaft sub-systems (including variable valve timing components), cast camshafts, forged camshafts, and completed camshafts

Examination of stated and projected yearly income for camshaft manufacturing portfolios

coverage of producers accounting for 75–80% of the world market in 2024

Extrapolation of segment-specific valuations for passenger cars, light commercial vehicles, and heavy commercial vehicles utilizing top-down (manufacturer revenue validation) and bottom-up (vehicle production volume × camshaft units per engine × ASP by region) techniques

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.