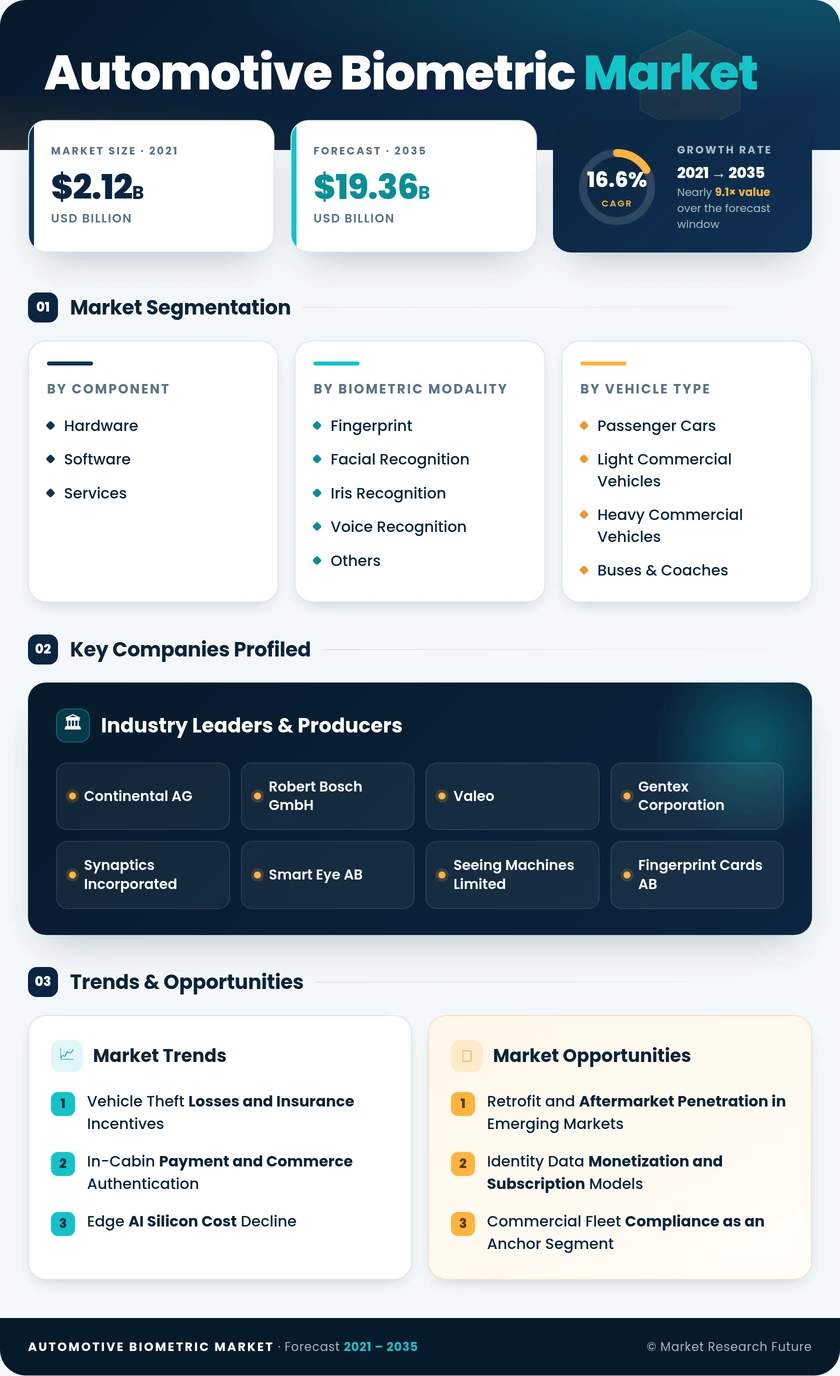
Automotive Biometric Market (2026 - 2035)

ID: MRFR/AT/7055-CR 188 Pages Triveni Bhoyar Last Updated: October 16, 2026
Automotive Biometric Market Research Report By Component (Hardware, Software, Services), By Biometric Modality (Fingerprint, Facial Recognition, Iris Recognition, Voice Recognition, Others (Vein, Gait, Cardiac)), By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Buses & Coaches), By Application (Driver Identification & Access, Driver Monitoring & Alertness, In-Car Payments, Personalization & Comfort, Fleet Management & Telematics), By Sales Channel (OEM-Fitted, Aftermarket) - Forecast to 2035
Automotive Biometric Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)16.6%
2025 Market SizeUSD 4.16 Billion
2035 Market SizeUSD 19.36 Billion
Key Players
Continental AG
Robert Bosch GmbH
Valeo
Gentex Corporation
Synaptics Incorporated
Smart Eye AB
Opportunities
  • Retrofit and Aftermarket Penetration in Emerging Markets
  • Identity Data Monetization and Subscription Models
  • Commercial Fleet Compliance as an Anchor Segment
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Market Size by Revenue (USD Billion) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Market Dynamics — Drivers | |
    1. 4.1 Mandatory Driver-Monitoring Regulation | |
    2. 4.2 Vehicle Theft Losses and Insurance Incentives | |
    3. 4.3 In-Cabin Payment and Commerce Authentication | |
    4. 4.4 Edge AI Silicon Cost Decline | |
    5. 4.5 Fleet and Shared-Mobility Identity Requirements | |
    6. 4.6 China Data-Localization and Domestic Feature Race | |
    7. 4.7 Software-Defined Vehicle and OTA Identity Updates | |
  5. 5 Market Dynamics — Restraints | |
    1. 5.1 Biometric Privacy Law and Litigation Exposure | |
    2. 5.2 False Rejection Under Real Cabin Conditions | |
    3. 5.3 Bill-of-Materials Pressure in Entry Segments | |
    4. 5.4 Spoofing, Template Theft and Cyber Exposure | |
    5. 5.5 Fragmented Standards and Certification Burden | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Retrofit and Aftermarket Penetration in Emerging Markets | |
    2. 6.2 Identity Data Monetization and Subscription Models | |
    3. 6.3 Commercial Fleet Compliance as an Anchor Segment | |
    4. 6.4 Multimodal Fusion with Occupant Wellness Sensing | |
    5. 6.5 Robotaxi and Keyless Shared-Fleet Access | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomy Redefines What Identity Is For | |
    2. 8.2 Platform Economics Displace Component Margins | |
    3. 8.3 Electrification and Zonal Architecture Accelerate Attach Rates | |
    4. 8.4 Privacy-by-Design Becomes a Procurement Filter | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Component | | |
      1. 9.1.1 Hardware | | |
      2. 9.1.2 Software | | |
      3. 9.1.3 Services | |
    2. 9.2 By Biometric Modality | | |
      1. 9.2.1 Fingerprint | | |
      2. 9.2.2 Facial Recognition | | |
      3. 9.2.3 Iris Recognition | | |
      4. 9.2.4 Voice Recognition | | |
      5. 9.2.5 Others (Vein, Gait, Cardiac) | |
    3. 9.3 By Vehicle Type | | |
      1. 9.3.1 Passenger Cars | | |
      2. 9.3.2 Light Commercial Vehicles | | |
      3. 9.3.3 Heavy Commercial Vehicles | | |
      4. 9.3.4 Buses & Coaches | |
    4. 9.4 By Application | | |
      1. 9.4.1 Driver Identification & Access | | |
      2. 9.4.2 Driver Monitoring & Alertness | | |
      3. 9.4.3 In-Car Payments | | |
      4. 9.4.4 Personalization & Comfort | | |
      5. 9.4.5 Fleet Management & Telematics | |
    5. 9.5 By Sales Channel | | |
      1. 9.5.1 OEM-Fitted | | |
      2. 9.5.2 Aftermarket | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Continental AG | | |
      2. 10.3.2 Robert Bosch GmbH | | |
      3. 10.3.3 Valeo | | |
      4. 10.3.4 Gentex Corporation | | |
      5. 10.3.5 Synaptics Incorporated | | |
      6. 10.3.6 Smart Eye AB | | |
      7. 10.3.7 Seeing Machines Limited | | |
      8. 10.3.8 Fingerprint Cards AB | | |
      9. 10.3.9 Aware, Inc. | | |
      10. 10.3.10 Hyundai Mobis | | |
      11. 10.3.11 Denso Corporation | | |
      12. 10.3.12 Cerence Inc. | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Conventions | |
    3. 12.3 CAGR Driver Disclaimer | |
  13. 13 Detailed Sources & Citations | |
    1. 13.1 Regulatory & Standards Sources | |
    2. 13.2 Company & Industry Sources | |
    3. 13.3 Abbreviations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Automotive Biometric Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Automotive Biometric Market – Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis – Estimated Contribution to CAGR, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis – Estimated Drag on CAGR, 2026–2035 | |
  19. TABLE 5 Global Automotive Biometric Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Automotive Biometric Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Automotive Biometric Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Automotive Biometric Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Automotive Biometric Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Automotive Biometric Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Automotive Biometric Market Size, by Component, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Automotive Biometric Market Size, by Biometric Modality, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Automotive Biometric Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Automotive Biometric Market Size, by Application, 2021–2035 (USD Billion) | |
  29. TABLE 15 Global Automotive Biometric Market Size, by Sales Channel, 2021–2035 (USD Billion) | |
  30. TABLE 16 North America Automotive Biometric Market Size, by Component, 2021–2035 (USD Billion) | |
  31. TABLE 17 North America Automotive Biometric Market Size, by Biometric Modality, 2021–2035 (USD Billion) | |
  32. TABLE 18 North America Automotive Biometric Market Size, by Application, 2021–2035 (USD Billion) | |
  33. TABLE 19 Europe Automotive Biometric Market Size, by Component, 2021–2035 (USD Billion) | |
  34. TABLE 20 Europe Automotive Biometric Market Size, by Biometric Modality, 2021–2035 (USD Billion) | |
  35. TABLE 21 Europe Automotive Biometric Market Size, by Application, 2021–2035 (USD Billion) | |
  36. TABLE 22 Asia-Pacific Automotive Biometric Market Size, by Component, 2021–2035 (USD Billion) | |
  37. TABLE 23 Asia-Pacific Automotive Biometric Market Size, by Biometric Modality, 2021–2035 (USD Billion) | |
  38. TABLE 24 Asia-Pacific Automotive Biometric Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  39. TABLE 25 South America Automotive Biometric Market Size, by Application, 2021–2035 (USD Billion) | |
  40. TABLE 26 Middle East & Africa Automotive Biometric Market Size, by Application, 2021–2035 (USD Billion) | |
  41. TABLE 27 Competitive Benchmarking Matrix – Global Automotive Biometric Market, 2026 | |
  42. TABLE 28 Company Profiles – Key Players, Global Automotive Biometric Market | |
  43. TABLE 29 Recent Developments & Strategic Announcements, 2023–2025 | |
  44. TABLE 30 Report Scope & Methodology Summary | |
  45. TABLE 31 Detailed Sources & Citations Index | | LIST OF FIGURES | |
  46. FIGURE 1 Global Automotive Biometric Market – Market Dynamics Overview (Drivers, Restraints, Opportunities) | |
  47. FIGURE 2 Industry Value Chain Analysis – Sensor to Certified Identity Platform | |
  48. FIGURE 3 Porter's Five Forces Analysis – Automotive Biometric Market | |
  49. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) | |
  50. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) | |
  51. FIGURE 6 Market Share by Component, 2025 vs 2035 (%) | |
  52. FIGURE 7 Market Share by Biometric Modality, 2025 (%) | |
  53. FIGURE 8 Market Share by Vehicle Type, 2025 (%) | |
  54. FIGURE 9 Market Share by Application, 2025 (%) | |
  55. FIGURE 10 Market Share by Sales Channel, 2025 vs 2035 (%) | |
  56. FIGURE 11 Regional Market Share Distribution, 2025 (%) | |
  57. FIGURE 12 Regional CAGR Comparison, 2026–2035 (%) | |
  58. FIGURE 13 Country-Level Share Within Asia-Pacific, 2025 (%) | |
  59. FIGURE 14 Competitive Landscape – Estimated Revenue Share Bands, 2026 | |
  60. FIGURE 15 Competitive Positioning Matrix – Capability Breadth vs Certification Depth | |
  61. FIGURE 16 Regulatory Timeline Impact Map, 2024–2032

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By ComponentHardware, Software, ServicesHardwareSoftware
By Biometric ModalityFingerprint, Facial Recognition, Iris Recognition, Voice Recognition, OthersFingerprintFacial Recognition
By Vehicle TypePassenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles, Buses & CoachesPassenger CarsLight Commercial Vehicles
By ApplicationDriver Identification & Access, Driver Monitoring & Alertness, In-Car Payments, Personalization & Comfort, Fleet Management & TelematicsDriver Identification & AccessIn-Car Payments
By Sales ChannelOEM-Fitted, AftermarketOEM-FittedAftermarket
By RegionNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Component

Sub-SegmentKey Trend
HardwareSensor content consolidating into cockpit domain controllers rather than dedicated ECUs
SoftwareLicensing shifts from one-time integration fees toward per-vehicle subscription renewals
ServicesCertification and calibration work expands with multi-jurisdiction launch programs


Component mix is the clearest indicator of where value migrates over the forecast. Hardware retains majority revenue throughout, but its share erodes as sensor ASPs compress and algorithm licensing compounds. Services grow quietly alongside both, because every new jurisdiction adds a conformance workload that neither silicon nor software eliminates.

By Biometric Modality

Sub-SegmentKey Trend
FingerprintStart-button and door-handle integration remains the lowest-friction entry point
Facial RecognitionRegulatory camera requirements deliver the sensor; identity becomes incremental
Iris RecognitionConcentrates in high-assurance premium and commercial applications
Voice RecognitionExploits microphone arrays already fitted for hands-free and voice assistants
Others (Vein, Gait, Cardiac)Research-stage modalities tied to continuous wellness monitoring


By Vehicle Type

Sub-SegmentKey Trend
Passenger CarsPersonalization and safety-rating scores drive standard-fit migration down-market
Light Commercial VehiclesCompliance and driver-attribution payback accelerates fleet adoption
Heavy Commercial VehiclesFatigue detection justified by single-incident avoidance economics
Buses & CoachesPublic-safety regulation and operator liability set a steady adoption floor


Vehicle-type dynamics split cleanly along buyer motivation. Consumers weigh convenience and rating badges; fleet operators weigh insurance premiums and regulatory exposure. That difference explains why commercial categories grow faster despite far smaller unit volumes.

By Application

Sub-SegmentKey Trend
Driver Identification & AccessLayered authentication supplements rather than replaces key-fob systems
Driver Monitoring & AlertnessMandate-driven, with scope widening beyond Europe through 2030
In-Car PaymentsStrong customer authentication rules make inherence factors the practical choice
Personalization & ComfortMulti-driver households and shared fleets sustain profile-recall demand
Fleet Management & TelematicsVerified identity upgrades telematics from vehicle-level to driver-level analytics


Applications sit on a maturity gradient. Access and monitoring are established and mandate-backed; payments and fleet analytics are earlier but growing faster because each attaches a recurring revenue stream to hardware that was justified by something else entirely.

By Sales Channel

Sub-SegmentKey Trend
OEM-FittedType-approval integration and warranty coverage keep factory fitment dominant
AftermarketRetrofit modules serve installed fleets facing near-term compliance deadlines


Channel share reflects a timing mismatch. Regulation arrives faster than replacement cycles, so operators with large existing fleets buy retrofit capability now rather than waiting a decade for compliant vehicles. That mismatch keeps aftermarket growth ahead of factory fitment even as OEM channels retain the larger revenue base.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.