Automotive Adaptive Lighting Market (2026 - 2035)

ID: MRFR/AT/2679-CR 98 Pages Shubham Munde Last Updated: September 15, 2026
Automotive Adaptive Lighting Market Research Report By Vehicle Type (Passenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles), By Application (Exterior Lighting, Interior Lighting), By Component (Lamp Assemblies, Sensors and Cameras, Control Modules and ECUs, Light Sources and Drivers, Software and Algorithms), By Technology (LED, Halogen, Xenon / HID, Laser, Micro-LED / OLED), By Sales Channel (OEM, Aftermarket), By Functionality (Automatic High Beam, Adaptive Front Lighting, Cornering and Bending Lights, Adaptive Driving Beam, Others) - Forecast to 2035
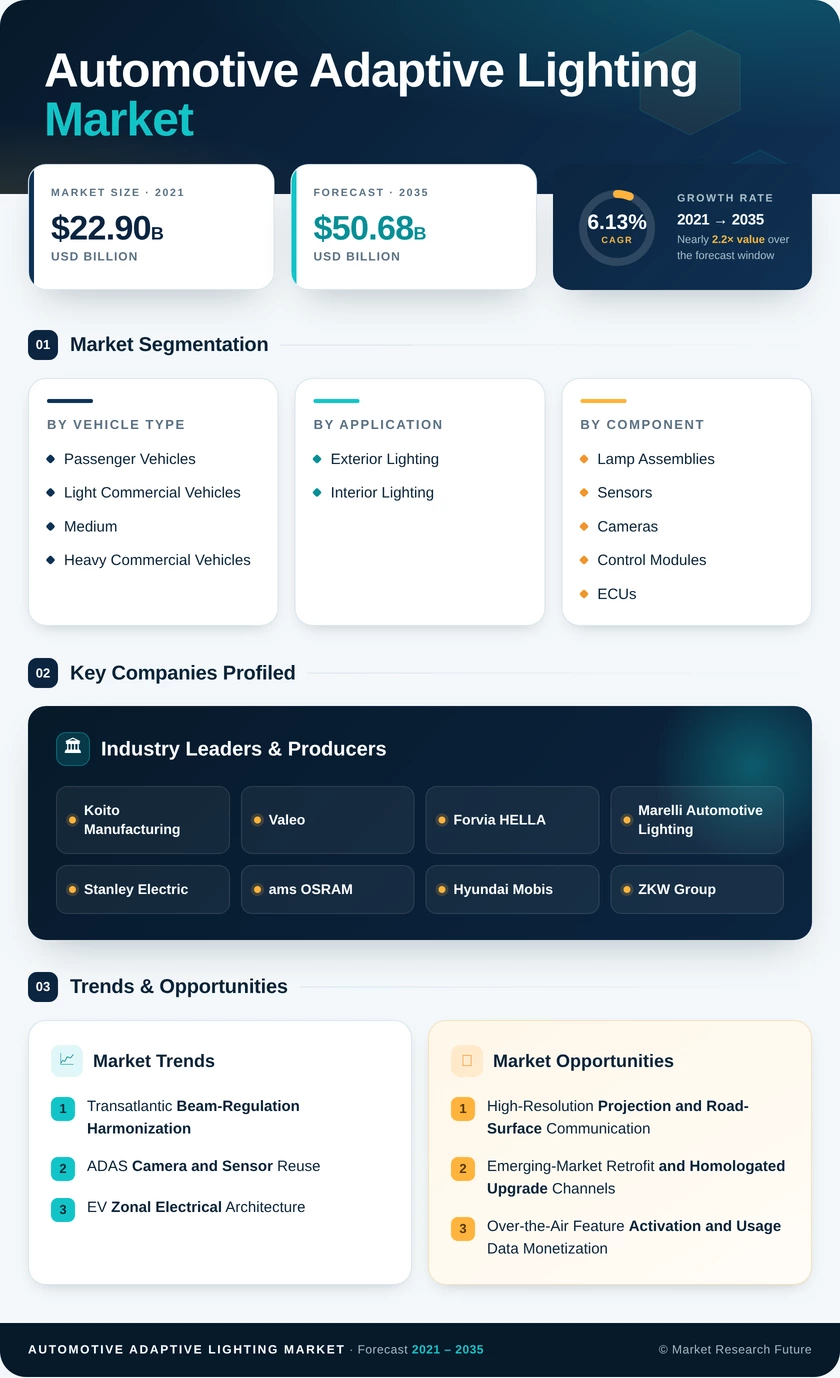
Automotive Adaptive Lighting Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.13%
2025 Market SizeUSD 27.95 Billion
2035 Market SizeUSD 50.68 Billion
Key Players
Koito Manufacturing
Valeo
Forvia HELLA
Marelli Automotive Lighting
Stanley Electric
ams OSRAM
Opportunities
  • High-Resolution Projection and Road-Surface Communication
  • Emerging-Market Retrofit and Homologated Upgrade Channels
  • Over-the-Air Feature Activation and Usage Data Monetization
  1. 1 Market Summary | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Technology | |
    2. 2.2 By Sector | |
    3. 2.3 By Geography | |
  3. 3 Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year Estimate (2025) | |
    3. 3.3 Forecast Market Size (2026–2035) | |
    4. 3.4 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Transatlantic Beam-Regulation Harmonization | |
    2. 4.2 LED and Driver-IC Cost Decline | |
    3. 4.3 ADAS Camera and Sensor Reuse | |
    4. 4.4 EV Zonal Electrical Architecture | |
    5. 4.5 Pedestrian-Protection Safety Ratings | |
    6. 4.6 Chinese Premium Feature Democratization | |
    7. 4.7 Software-Defined Feature Monetization | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Module Cost Premium Over Halogen Baseline | |
    2. 5.2 Homologation and Certification Fragmentation | |
    3. 5.3 Repair Cost and Insurance Total-Loss Pressure | |
    4. 5.4 Semiconductor and Phosphor Supply Volatility | |
    5. 5.5 Thermal Derating in High-Ambient Markets | |
  6. 6 Opportunities | |
    1. 6.1 High-Resolution Projection and Road-Surface Communication | |
    2. 6.2 Emerging-Market Retrofit and Homologated Upgrade Channels | |
    3. 6.3 Over-the-Air Feature Activation and Usage Data Monetization | |
    4. 6.4 India and ASEAN Manufacturing Localization | |
    5. 6.5 Commercial-Vehicle Fleet Safety Economics | |
  7. 7 Regional Market Share & Country-Level Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 US | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 UK | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Italy | | |
      5. 7.2.5 Spain | | |
      6. 7.2.6 Nordic Countries | | |
      7. 7.2.7 Russia | | |
      8. 7.2.8 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 India | | |
      3. 7.3.3 Japan | | |
      4. 7.3.4 South Korea | | |
      5. 7.3.5 ASEAN | | |
      6. 7.3.6 Rest of Asia-Pacific | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Argentina | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 Saudi Arabia | | |
      2. 7.5.2 UAE | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Egypt | | |
      5. 7.5.5 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Perception-Led Beam Control and Autonomy Convergence | |
    2. 8.2 Electrification Supercycle | |
    3. 8.3 Platform Economics and Software-Defined Lighting | |
    4. 8.4 Materials Circularity and Regulatory Reporting | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Vehicle Type | | |
      1. 9.1.1 Passenger Vehicles | | |
      2. 9.1.2 Light Commercial Vehicles | | |
      3. 9.1.3 Medium and Heavy Commercial Vehicles | |
    2. 9.2 By Application | | |
      1. 9.2.1 Exterior Lighting | | |
      2. 9.2.2 Interior Lighting | |
    3. 9.3 By Component | | |
      1. 9.3.1 Lamp Assemblies | | |
      2. 9.3.2 Sensors and Cameras | | |
      3. 9.3.3 Control Modules and ECUs | | |
      4. 9.3.4 Light Sources and Drivers | | |
      5. 9.3.5 Software and Algorithms | |
    4. 9.4 By Technology | | |
      1. 9.4.1 LED | | |
      2. 9.4.2 Halogen | | |
      3. 9.4.3 Xenon / HID | | |
      4. 9.4.4 Laser | | |
      5. 9.4.5 Micro-LED / OLED | |
    5. 9.5 By Sales Channel | | |
      1. 9.5.1 OEM | | |
      2. 9.5.2 Aftermarket | |
    6. 9.6 By Functionality | | |
      1. 9.6.1 Automatic High Beam | | |
      2. 9.6.2 Adaptive Front Lighting | | |
      3. 9.6.3 Cornering and Bending Lights | | |
      4. 9.6.4 Adaptive Driving Beam | | |
      5. 9.6.5 Others | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Koito Manufacturing | | |
      2. 10.3.2 Valeo | | |
      3. 10.3.3 Forvia HELLA | | |
      4. 10.3.4 Marelli Automotive Lighting | | |
      5. 10.3.5 Stanley Electric | | |
      6. 10.3.6 ams OSRAM | | |
      7. 10.3.7 Hyundai Mobis | | |
      8. 10.3.8 ZKW Group | | |
      9. 10.3.9 OPmobility (Varroc Lighting Systems) | | |
      10. 10.3.10 HASCO Vision | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Valuation Currency & Assumptions | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources & Citations | |
  14. 14 Frequently Asked Questions | | LIST OF TABLES | |
  15. TABLE 1 Global Automotive Adaptive Lighting Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Automotive Adaptive Lighting Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis — Estimated Contribution to CAGR, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis — Estimated Drag on CAGR, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Application, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by Component, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Market Size, by Technology, 2021–2035 (USD Billion) | |
  29. TABLE 15 Global Market Size, by Sales Channel, 2021–2035 (USD Billion) | |
  30. TABLE 16 Global Market Size, by Functionality, 2021–2035 (USD Billion) | |
  31. TABLE 17 Competitive Benchmarking Matrix — Estimated Revenue Share Ranges, 2026 | |
  32. TABLE 18 Company Profiles — Key Players and Strategic Positioning | |
  33. TABLE 19 Recent Developments & Strategic Announcements, 2023–2025 | |
  34. TABLE 20 Report Scope & Methodology Summary | |
  35. TABLE 21 Detailed Sources & Citations Index | |
  36. TABLE 22 North America Market Size, by Technology, 2021–2035 (USD Billion) | |
  37. TABLE 23 Europe Market Size, by Functionality, 2021–2035 (USD Billion) | |
  38. TABLE 24 Asia-Pacific Market Size, by Vehicle Type, 2021–2035 (USD Billion) | |
  39. TABLE 25 Global Attach-Rate Assumptions, by Vehicle Segment, 2021–2035 | | LIST OF FIGURES | |
  40. FIGURE 1 Market Dynamics — Drivers, Restraints, and Opportunities Framework | |
  41. FIGURE 2 Industry Value Chain Analysis — Emitter to Vehicle Integration | |
  42. FIGURE 3 Porter's Five Forces Analysis | |
  43. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 (USD Billion) | |
  44. FIGURE 5 Year-over-Year Growth Rate Trend, 2022–2035 (%) | |
  45. FIGURE 6 Market Share by Vehicle Type, 2025 vs 2035 (%) | |
  46. FIGURE 7 Market Share by Application, 2025 (%) | |
  47. FIGURE 8 Market Share by Component, 2025 (%) | |
  48. FIGURE 9 Market Share by Technology, 2025 vs 2035 (%) | |
  49. FIGURE 10 Market Share by Sales Channel, 2025 (%) | |
  50. FIGURE 11 Market Share by Functionality, 2025 (%) | |
  51. FIGURE 12 Regional Market Share Distribution, 2025 (%) | |
  52. FIGURE 13 Regional CAGR Comparison, 2026–2035 (%) | |
  53. FIGURE 14 Country-Level Share within Asia-Pacific, 2025 (%) | |
  54. FIGURE 15 Country-Level Share within Europe, 2025 (%) | |
  55. FIGURE 16 Competitive Landscape — Estimated Revenue Share Positioning, 2026 | |
  56. FIGURE 17 Market Concentration Index Trend, 2021–2035 | |
  57. FIGURE 18 Technology Adoption S-Curve — LED, Laser, and Micro-LED

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Vehicle TypePassenger Vehicles; Light Commercial Vehicles; Medium and Heavy Commercial VehiclesPassenger VehiclesMedium and Heavy Commercial Vehicles
By ApplicationExterior Lighting; Interior LightingExterior LightingInterior Lighting
By ComponentLamp Assemblies; Sensors and Cameras; Control Modules and ECUs; Light Sources and Drivers; Software and AlgorithmsLamp AssembliesSensors and Cameras
By TechnologyLED; Halogen; Xenon / HID; Laser; Micro-LED / OLEDLEDLaser
By Sales ChannelOEM; AftermarketOEMAftermarket
By FunctionalityAutomatic High Beam; Adaptive Front Lighting; Cornering and Bending Lights; Adaptive Driving Beam; OthersAutomatic High BeamAdaptive Driving Beam
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Vehicle Type

Sub-SegmentKey Trend
Passenger VehiclesOption-package bundling moves adaptive systems from premium trims into mid-segment nameplates.
Light Commercial VehiclesDelivery-fleet safety specifications lift attach rates on urban duty cycles.
Medium and Heavy Commercial VehiclesQuantified night-collision cost drives total-cost-of-ownership justification within three years.


By Application

Sub-SegmentKey Trend
Exterior LightingRegulatory mandates on glare control and beam performance make advanced systems near-universal in regulated markets.
Interior LightingCabin illumination gains a safety role in signalling autonomy handover and hazard direction.


Exterior applications remain the regulated core, but interior lighting is quietly shifting budget category. Once cabin illumination carries a functional-safety role rather than a styling role, it is specified by engineering teams and validated to different standards — which raises both content value and supplier qualification barriers.

By Component

Sub-SegmentKey Trend
Lamp AssembliesOptical, housing, and thermal integration resists commoditization better than electronics.
Sensors and CamerasDetection ranges extend beyond 250 metres as resolution requirements climb.
Control Modules and ECUsFunctional-safety compliance and pixel addressing drive electronics content
Light Sources and DriversMulti-channel current control costs fall steadily with semiconductor scaling.
Software and AlgorithmsOwnership of beam-shaping logic determines who captures post-sale activation revenue.


Hardware still holds the value today, but the strategic contest is over software rights. Suppliers negotiating new platform contracts are trading build-margin concessions for participation in over-the-air activation revenue, a structural change in how lighting programs are priced.

By Technology

Sub-SegmentKey Trend
LEDMature supply chain and falling emitter pricing keep it the volume default through 2035
HalogenRetreats to entry-price fitment and aftermarket replacement in unregulated markets
Xenon / HIDDeclines to installed-base servicing as new-program specification ceases
LaserExtends usable beam range on unlit highways, justifying premium positioning
Micro-LED / OLEDEnables road projection and thin-panel rear signatures that older technologies cannot perform


LED dominance is durable, but the technology mix at the margin is where differentiation lives. Laser and micro-LED are not competing with LED on cost — they are enabling functions that create new specification categories entirely.

By Sales Channel

Sub-SegmentKey Trend
OEMType approval attached to the delivered vehicle keeps factory fitment structurally dominant.
AftermarketCollision-replacement volume and regulated retrofit programs expand the addressable pool.


Factory channels will keep the majority share, yet the aftermarket offers better unit economics. Suppliers that secure regional type approval for retrofit modules access an installed parc that will otherwise never generate adaptive-lighting revenue.

By Functionality

Sub-SegmentKey Trend
Automatic High BeamLowest-cost entry function with the broadest regulatory acceptance globally
Adaptive Front LightingSpeed- and steering-linked beam adjustment becomes standard on mid-segment vehicles.
Cornering and Bending LightsValued in dense urban and winding rural environments; stable mid-tier demand
Adaptive Driving BeamPixel-level masking scales rapidly following North American regulatory approval
OthersProjection, welcome sequences, and vehicle-to-pedestrian communication functions emerge.


Function mix is migrating upward through the stack. Vehicles that shipped with automatic high beam five years ago now specify pixel-level masking, and the functions currently grouped under Others are the leading candidates for the next specification tier.


Write a message…

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.