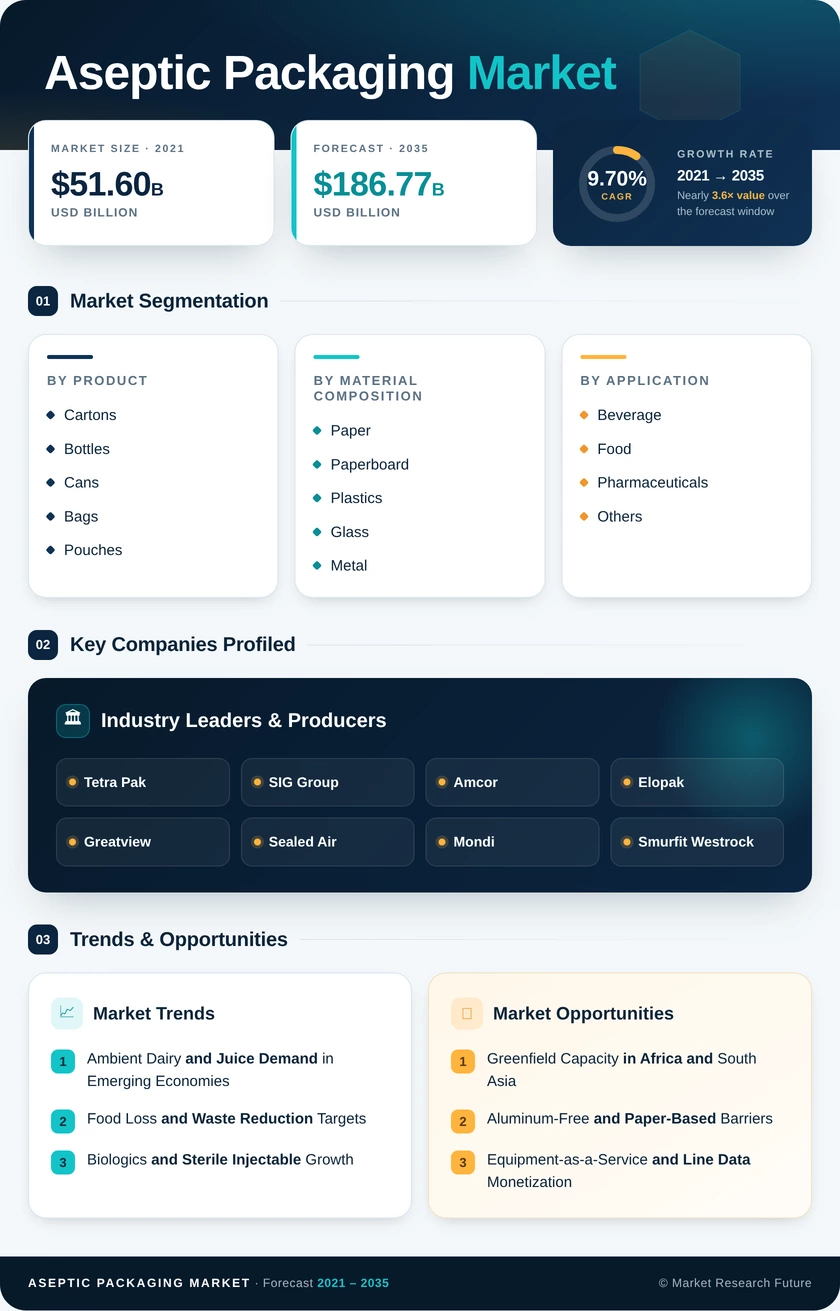
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product | Cartons; Bottles; Cans; Bags and Pouches; Others | Cartons (41.0% share) | Bags and Pouches (10.64% CAGR) |
| By Material Composition | Paper and Paperboard; Plastics; Glass; Metal; Composite Laminates | Paper and Paperboard (44.3% share) | Composite Laminates (10.72% CAGR) |
| By Application | Beverage; Food; Pharmaceuticals; Others | Beverage (55.4% share) | Pharmaceuticals (10.47% CAGR) |
| By Filling Technology | Form-Fill-Seal (FFS); Blow-Fill-Seal (BFS); Injection Aseptic Filling; Others | Form-Fill-Seal (FFS) (39.8% share) | Injection Aseptic Filling (10.51% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific (38.6% share) | Middle East & Africa (11.40% CAGR) |
Market Segmentation Overview
Each dimension below summarizes the sub-segment trends that shape competitive strategy in the Aseptic Packaging Market.
By Product
| Sub-Segment | Key Trend |
|---|---|
| Cartons | Foil-free barrier redesign to meet 2030 recyclability rules |
| Bottles | Premium coffee and probiotic drinks sustain higher pack values. |
| Cans | Energy and functional beverages favor metal's barrier and recyclability. |
| Bags and Pouches | Spouted, resealable formats gain in direct-to-consumer channels. |
| Others | Bag-in-box and cups serve food-service and bulk users. |
Cartons lead with a 41.0% share because UHT milk and juice processors run large installed bases of carton fillers under long material contracts. Bags and Pouches grow fastest at a 10.64% CAGR, since they cut freight weight, allow short-run digital print and now offer resealable spouts. Bottles and Cans hold defensible niches where perceived quality or carbonation-adjacent positioning justifies higher pack costs.
By Material Composition
| Sub-Segment | Key Trend |
|---|---|
| Paper and Paperboard | Natural and brown board variants support renewable-content claims |
| Plastics | Mono-material polyethylene structures replace mixed polymers. |
| Glass | Confined to ultra-premium beverages and select vials |
| Metal | Aluminum demand tied to energy drinks and nutrition products |
| Composite Laminates | Vapor-deposited coatings deliver foil-level oxygen barriers. |
Paper and Paperboard dominate with a 44.3% share, tracking carton leadership in dairy and juice. Composite Laminates grow fastest at a 10.72% CAGR because stacked polyethylene and EVOH layers, or silicon oxide coatings, match aluminum foil's barrier while easing recycling under PPWR. Glass and Metal stay tied to specific premium or energy-drink formats rather than broad substitution.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Beverage | Ready-to-Drink (RTD) Beverages lead growth within the category |
| Food | Preservative-free soups, sauces and baby food expand ambient ranges. |
| Pharmaceuticals | Biologics and single-dose vaccines move to BFS and polymer formats. |
| Others | Personal care uses remain small and specialized. |
Beverage holds a 55.4% share, driven by dairy, juice and the fast-growing Ready-to-Drink (RTD) Beverages sub-segment. Pharmaceuticals grow fastest at a 10.47% CAGR as biologic approvals and Annex 1 compliance push drugmakers toward closed, contact-free filling. Food benefits from clean-label demand, where ambient packs replace chemical preservatives.
By Filling Technology
| Sub-Segment | Key Trend |
|---|---|
| Form-Fill-Seal (FFS) | High-speed roll-fed lines anchor dairy-scale production |
| Blow-Fill-Seal (BFS) | Closed-cycle molding and filling preferred for sterile drugs |
| Injection Aseptic Filling | Modular heads enable sub-hour changeovers for premium SKUs |
| Others | Rotary systems serve large dairies needing very high throughput. |
Form-Fill-Seal (FFS) leads with a 39.8% share because roll-fed carton and pouch lines deliver the lowest cost per pack at dairy volumes. Injection Aseptic Filling grows fastest at a 10.51% CAGR as co-packers handling many short runs value quick changeovers and viscous-product capability. Blow-Fill-Seal (BFS) retains its role in pharmaceuticals, where eliminating human contact outweighs higher per-unit equipment cost.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA