Aptamers Market (2026 - 2035)

ID: MRFR/LS/5167-HCR 85 Pages Rahul Gotadki Last Updated: September 10, 2026
Aptamers Market Research Report By Technology (Systematic Evolution of Ligands by Exponential Enrichment, SELEX, Aptamer-based Biosensors), By Application (Diagnostics, Therapeutics, Research Development, Biomedical), By Type (DNA Aptamers, RNA Aptamers, Xeno-nucleic Acid Aptamers), By End Use (Pharmaceutical Industry, Academic Research, Biotechnology Companies) and By Regional (North America, Europe, South America, Asia-Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
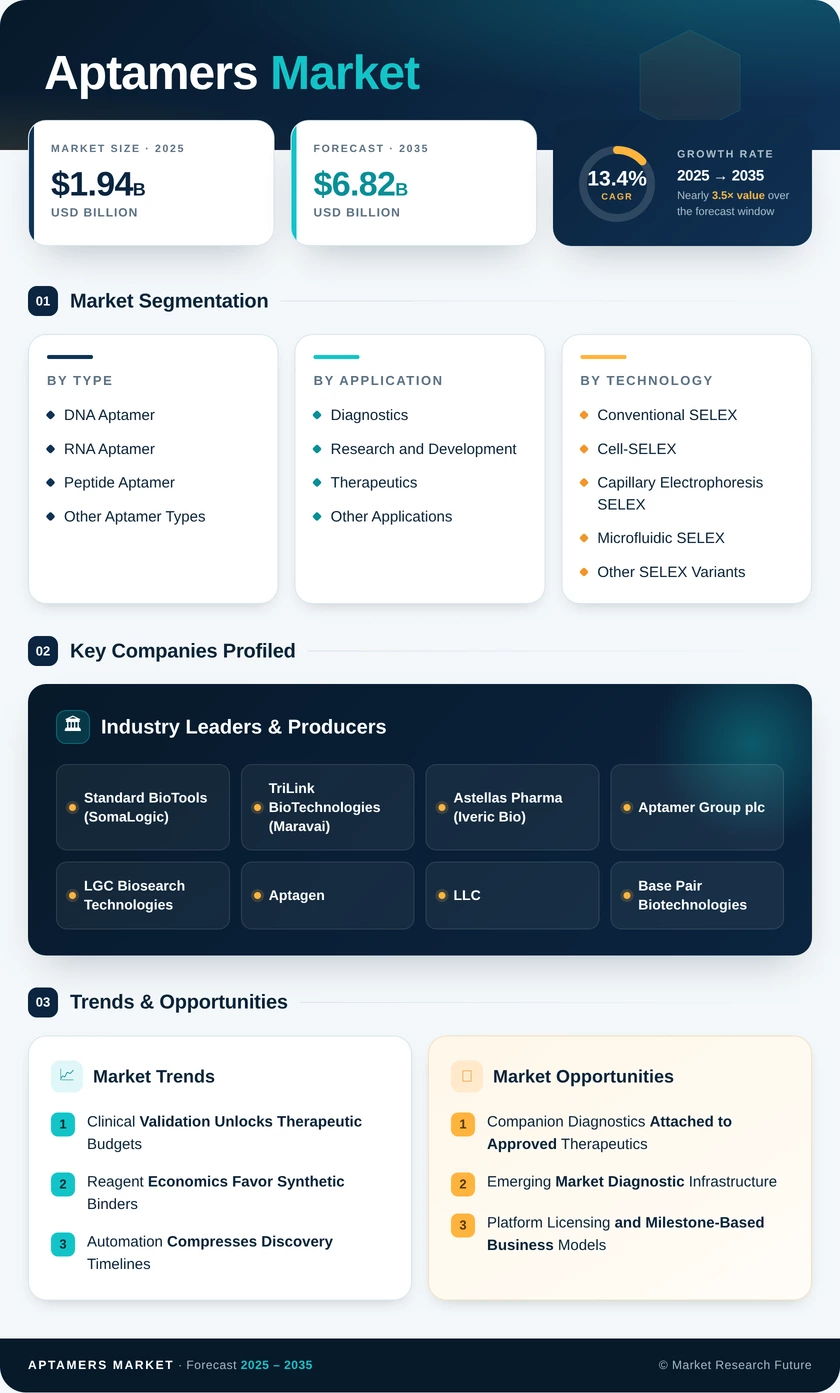
Aptamers Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)13.4%
2025 Market SizeUSD 1.94 Billion
2035 Market SizeUSD 6.82 Billion
Key Players
Standard BioTools
TriLink BioTechnologies
Astellas Pharma
Aptamer Group plc
LGC Biosearch Technologies
Aptagen, LLC
Opportunities
  • Companion Diagnostics Attached to Approved Therapeutics
  • Emerging Market Diagnostic Infrastructure
  • Platform Licensing and Milestone-Based Business Models
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 Takeaways by Technology |
    2. 2.2 Takeaways by Sector |
    3. 2.3 Takeaways by Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Clinical Validation Unlocks Therapeutic Budgets |
    2. 4.2 Reagent Economics Favor Synthetic Binders |
    3. 4.3 Automation Compresses Discovery Timelines |
    4. 4.4 Public Funding Builds the Base Layer
  5. 5 Restraints Impact Analysis |
    1. 5.1 Pharmacokinetics Remain the Hard Problem |
    2. 5.2 Manufacturing Economics Bite Above Gram Scale |
    3. 5.3 Regulatory Precedent Is Narrow
  6. 6 Opportunities |
    1. 6.1 Companion Diagnostics Attached to Approved Therapeutics |
    2. 6.2 Emerging Market Diagnostic Infrastructure |
    3. 6.3 Platform Licensing and Milestone-Based Business Models |
    4. 6.4 Environmental and Food Safety Surveillance |
    5. 6.5 Targeted Payload Delivery Beyond Oncology
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Machine Learning Reshapes Sequence Design |
    2. 8.2 Manufacturing Cost Curves Bend Downward |
    3. 8.3 Decentralized Testing Becomes the Volume Channel |
    4. 8.4 Consolidation Follows Validation
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Product Type | |
      1. 9.1.1 DNA Aptamer | |
      2. 9.1.2 RNA Aptamer | |
      3. 9.1.3 Peptide Aptamer | |
      4. 9.1.4 Other Aptamer Types |
    2. 9.2 By Application | |
      1. 9.2.1 Diagnostics | |
      2. 9.2.2 Therapeutics | |
      3. 9.2.3 Research and Development | |
      4. 9.2.4 Other Applications |
    3. 9.3 By Technology | |
      1. 9.3.1 Conventional SELEX | |
      2. 9.3.2 Cell-SELEX | |
      3. 9.3.3 Capillary Electrophoresis SELEX | |
      4. 9.3.4 Microfluidic SELEX | |
      5. 9.3.5 Other SELEX Variants
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis (2026) |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 Standard BioTools (SomaLogic) | |
      2. 10.3.2 TriLink BioTechnologies (Maravai LifeSciences) | |
      3. 10.3.3 Astellas Pharma (Iveric Bio) | |
      4. 10.3.4 Aptamer Group plc | |
      5. 10.3.5 LGC Biosearch Technologies | |
      6. 10.3.6 Aptagen, LLC | |
      7. 10.3.7 Base Pair Biotechnologies | |
      8. 10.3.8 Aptamer Sciences Inc. | |
      9. 10.3.9 AM Biotechnologies | |
      10. 10.3.10 NeoVentures Biotechnology | |
      11. 10.3.11 Vivonics, Inc.
  11. 11 Recent News & Developments (2023–2025)
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Validation |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions (FAQs)
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Aptamers Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Aptamers Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Aptamers Market Size, by Region, 2021–2035 (USD Billion) |
  21. TABLE 6 North America Aptamers Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Aptamers Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Aptamers Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Aptamers Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Aptamers Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Aptamers Market Size, by Product Type, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Aptamers Market Size, by Technology, 2021–2035 (USD Billion) |
  29. TABLE 14 North America Aptamers Market Size, by Product Type, 2021–2035 (USD Billion) |
  30. TABLE 15 North America Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  31. TABLE 16 North America Aptamers Market Size, by Technology, 2021–2035 (USD Billion) |
  32. TABLE 17 Europe Aptamers Market Size, by Product Type, 2021–2035 (USD Billion) |
  33. TABLE 18 Europe Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  34. TABLE 19 Europe Aptamers Market Size, by Technology, 2021–2035 (USD Billion) |
  35. TABLE 20 Asia-Pacific Aptamers Market Size, by Product Type, 2021–2035 (USD Billion) |
  36. TABLE 21 Asia-Pacific Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  37. TABLE 22 Asia-Pacific Aptamers Market Size, by Technology, 2021–2035 (USD Billion) |
  38. TABLE 23 South America Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  39. TABLE 24 Middle East & Africa Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  40. TABLE 25 US Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  41. TABLE 26 Germany Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  42. TABLE 27 China Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  43. TABLE 28 India Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  44. TABLE 29 Japan Aptamers Market Size, by Application, 2021–2035 (USD Billion) |
  45. TABLE 30 Competitive Benchmarking Matrix – Global Aptamers Market, 2026 |
  46. TABLE 31 Company Profiles – Key Players, Global Aptamers Market |
  47. TABLE 32 Recent Developments & Strategic Announcements, 2023–2025 |
  48. TABLE 33 Report Scope & Methodology Summary |
  49. TABLE 34 Detailed Sources & Citations Index
  50. 16 LIST OF FIGURES |
  51. FIGURE 1 Global Aptamers Market Dynamics – Drivers, Restraints, Opportunities |
  52. FIGURE 2 Industry Value Chain Analysis – Aptamers Market |
  53. FIGURE 3 Porter's Five Forces Analysis – Aptamers Market |
  54. FIGURE 4 Global Aptamers Market Size Trend, 2021–2035 (USD Billion) |
  55. FIGURE 5 Year-over-Year Growth Trajectory, 2022–2035 (%) |
  56. FIGURE 6 Market Share by Product Type, 2025 vs 2035 (%) |
  57. FIGURE 7 Market Share by Application, 2025 vs 2035 (%) |
  58. FIGURE 8 Segment CAGR Comparison by Technology, 2026–2035 (%) |
  59. FIGURE 9 Regional Market Share Distribution, 2025 (%) |
  60. FIGURE 10 Regional Market Share Distribution, 2035 (%) |
  61. FIGURE 11 Regional CAGR Comparison, 2026–2035 (%) |
  62. FIGURE 12 North America Country-Level Share, 2025 (%) |
  63. FIGURE 13 Europe Country-Level Share, 2025 (%) |
  64. FIGURE 14 Asia-Pacific Country-Level Growth Comparison, 2026–2035 (%) |
  65. FIGURE 15 Competitive Landscape – Estimated Revenue Share Distribution, 2026 |
  66. FIGURE 16 Competitive Positioning Quadrant – Discovery vs Manufacturing Capability |
  67. FIGURE 17 Driver Impact Weighting Chart, 2026–2035 |
  68. FIGURE 18 Restraint Impact Weighting Chart, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Product TypeRNA Aptamer, DNA Aptamer, Peptide Aptamer, Other Aptamer TypesDNA AptamerRNA Aptamer
By ApplicationDiagnostics, Therapeutics, Research and Development, Other ApplicationsDiagnosticsTherapeutics
By TechnologyConventional SELEX, Cell-SELEX, Capillary Electrophoresis SELEX, Microfluidic SELEX, Other SELEX VariantsConventional SELEXMicrofluidic SELEX
By GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
DNA AptamerCost-efficient synthesis and handling robustness keep it the default for diagnostic assay development
RNA AptamerConformational diversity supports the therapeutic pipeline; both approved drugs use this backbone
Peptide AptamerGrowing interest in intracellular protein-protein interaction targets
Other Aptamer TypesModified and xeno-nucleic acid backbones address nuclease resistance limitations


Backbone chemistry is the first decision any program makes, and it is largely irreversible once assay validation begins. DNA wins on economics and shelf life; RNA wins on target reach. Modified backbones increasingly blur that line, though each modification adds characterization burden that early-stage teams often underestimate.

By Application

Sub-SegmentKey Trend
DiagnosticsCold-chain independence and lot reproducibility drive substitution away from antibody reagents
TherapeuticsRegulatory precedent from ophthalmology approval is reopening oncology and fibrosis programs
Research and DevelopmentGrant-funded discovery workflows provide stable, counter-cyclical demand
Other ApplicationsFood contaminant screening and environmental monitoring expand the non-clinical base


Revenue today concentrates in diagnostics and research reagents, where purchasing decisions are made monthly rather than across decade-long development cycles. Therapeutics changes the shape of the market rather than its current size — one commercial success can outweigh an entire reagent category, which is why capital allocation increasingly skews toward clinical assets.

By Technology

Sub-SegmentKey Trend
Conventional SELEXRemains the validated reference method across academic and early-stage industrial workflows
Cell-SELEXEnables binder discovery against native membrane targets without prior purification
Capillary Electrophoresis SELEXHigh partitioning stringency reduces the number of required selection rounds
Microfluidic SELEXAutomation and miniaturization compress discovery timelines and lower per-campaign cost
Other SELEX VariantsSpecialized protocols address difficult target classes and non-standard conditions


Selection method determines cost per binder, and cost per binder determines which commercial models are viable. Conventional protocols still carry the installed base, but service providers competing on turnaround are migrating hard toward automated and microfluidic formats. Expect that migration to reshape supplier economics well before it reshapes reported segment shares.

By Region

Sub-SegmentKey Trend
North AmericaTherapeutic commercialization and dense clinical trial infrastructure sustain revenue leadership
EuropeAnimal-free reagent policy and IVDR evidence requirements accelerate substitution
Asia-PacificDomestic synthesis capacity and decentralized diagnostic rollout drive the fastest regional growth
South AmericaPublic laboratory modernization creates procurement demand for shelf-stable reagents
Middle East & AfricaSovereign biotechnology strategies build local manufacturing and surveillance capability


Regional divergence is widening rather than narrowing. North America and Europe compete on validation depth and regulatory sophistication, while Asia-Pacific competes on cost and capacity. That split suggests supply chains will regionalize over the forecast decade rather than consolidate into a single global network.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.