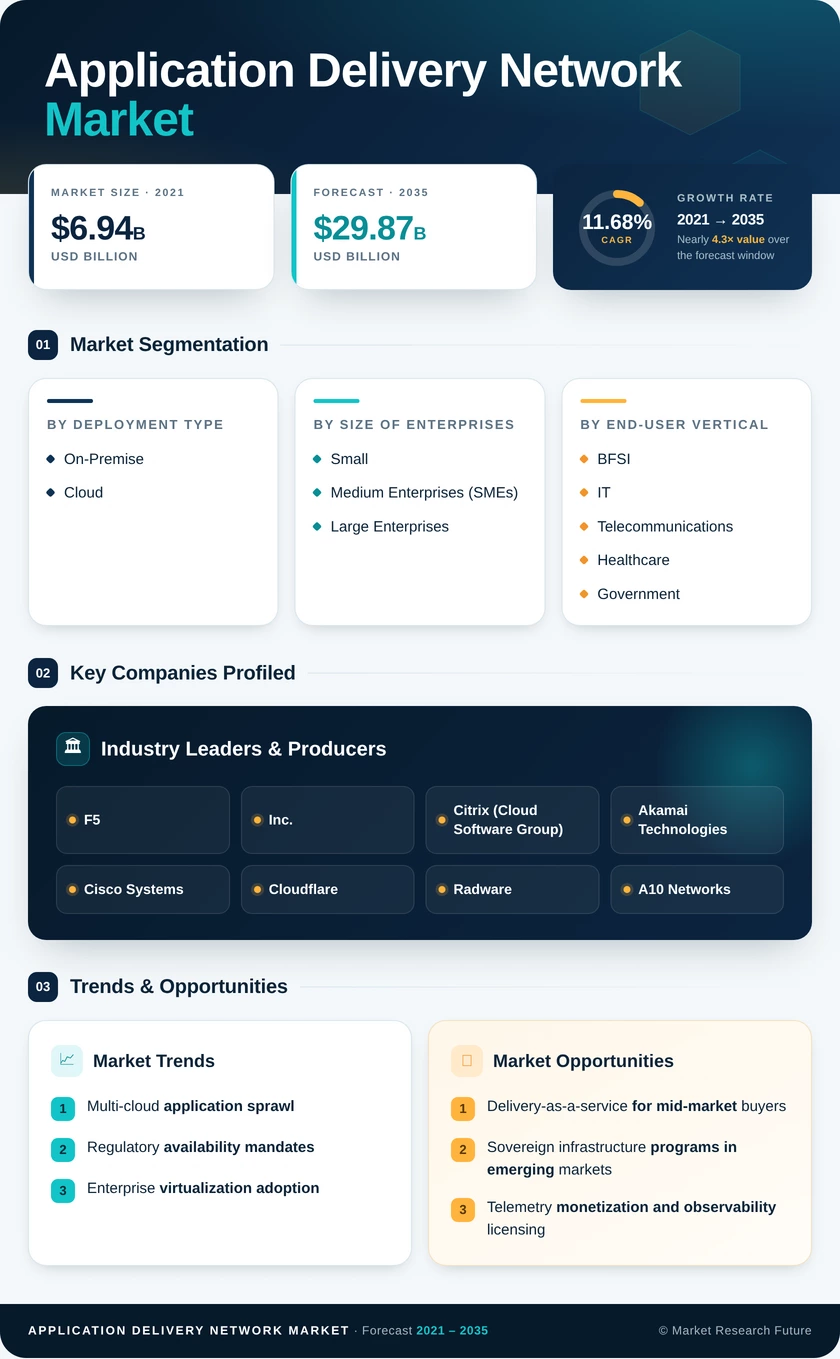
Market Segmentation Analysis
By Deployment Type
9.1.1 On-Premise
9.1.2 Cloud
By Size of Enterprises
9.2.1 Small and Medium Enterprises (SMEs)
9.2.2 Large Enterprises
By End-user Vertical
9.3.1 BFSI
9.3.2 IT and Telecommunications
9.3.3 Healthcare
9.3.4 Government
9.3.5 Media & Entertainment
9.3.6 Other End-user Verticals
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Deployment Type | On-Premise; Cloud | On-Premise (41.2% share) | Cloud (13.9% CAGR) |
| By Size of Enterprises | Small and Medium Enterprises (SMEs); Large Enterprises | Large Enterprises (USD 7.28 Billion) | Small and Medium Enterprises (SMEs) (14.6% CAGR) |
| By End-user Vertical | BFSI; IT and Telecommunications; Healthcare; Government; Media & Entertainment; Other End-user Verticals | BFSI (24.6% share) | Healthcare (13.4% CAGR) |
Market Segmentation Overview
By Deployment Type
| Sub-Segment | Key Trend |
| On-Premise | Retained for deterministic latency, regulated data, and sovereign hosting obligations |
| Cloud | Consumption billing and elastic scaling aligned to multi-cloud application estates |
On-Premise still holds the larger revenue base at 41.2% of 2025 value because trading platforms, clinical systems, and classified government workloads cannot tolerate variable network paths or shared control planes. Cloud grows faster at 13.9% CAGR, driven by buyers who want delivery infrastructure provisioned in the same automation pipeline as the applications it fronts. The practical outcome is hybrid: the same vendor software runs in both places, governed by one policy set, which is why On-Premise decline is gradual rather than abrupt.
By Size of Enterprises
| Sub-Segment | Key Trend |
| Small and Medium Enterprises (SMEs) | Entry cost collapse via consumption pricing and managed offerings |
| Large Enterprises | Multi-region estates requiring centralized policy and audit-grade telemetry |
Large Enterprises lead on absolute revenue at USD 7.28 billion because a single global bank or telecom operator may license hundreds of delivery instances across regions and clouds. Small and Medium Enterprises grow fastest at 14.6% CAGR, since monthly consumption pricing removed the six-figure appliance barrier that previously kept them on provider-default tooling. The buying behavior differs sharply: SMEs favor managed services and template-driven configuration, while Large Enterprises staff dedicated teams and negotiate custom policy frameworks.
By End-user Vertical
| Sub-Segment | Key Trend |
| BFSI | Regulator-mandated availability targets and transaction integrity requirements |
| IT and Telecommunications | 5G core and service platform modernization |
| Healthcare | Telemedicine and patient portal traffic scaling |
| Government | Zero-trust architecture and sovereign hosting mandates |
| Media & Entertainment | Live-event concurrency and streaming session management |
| Other End-user Verticals | Manufacturing and retail digitization programs |
BFSI dominates with 24.6% of 2025 revenue because banking supervisors treat application availability as a prudential control, converting delivery infrastructure from a performance choice into a documented compliance obligation. Healthcare grows fastest at 13.4% CAGR as telemedicine platforms and patient portals absorb consultation volumes that were previously in-person, each requiring session persistence and encrypted termination at scale. IT and Telecommunications remains the second-largest contributor at USD 2.41 billion, where operators rebuild delivery layers to support 5G core functions and distributed edge sites.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA