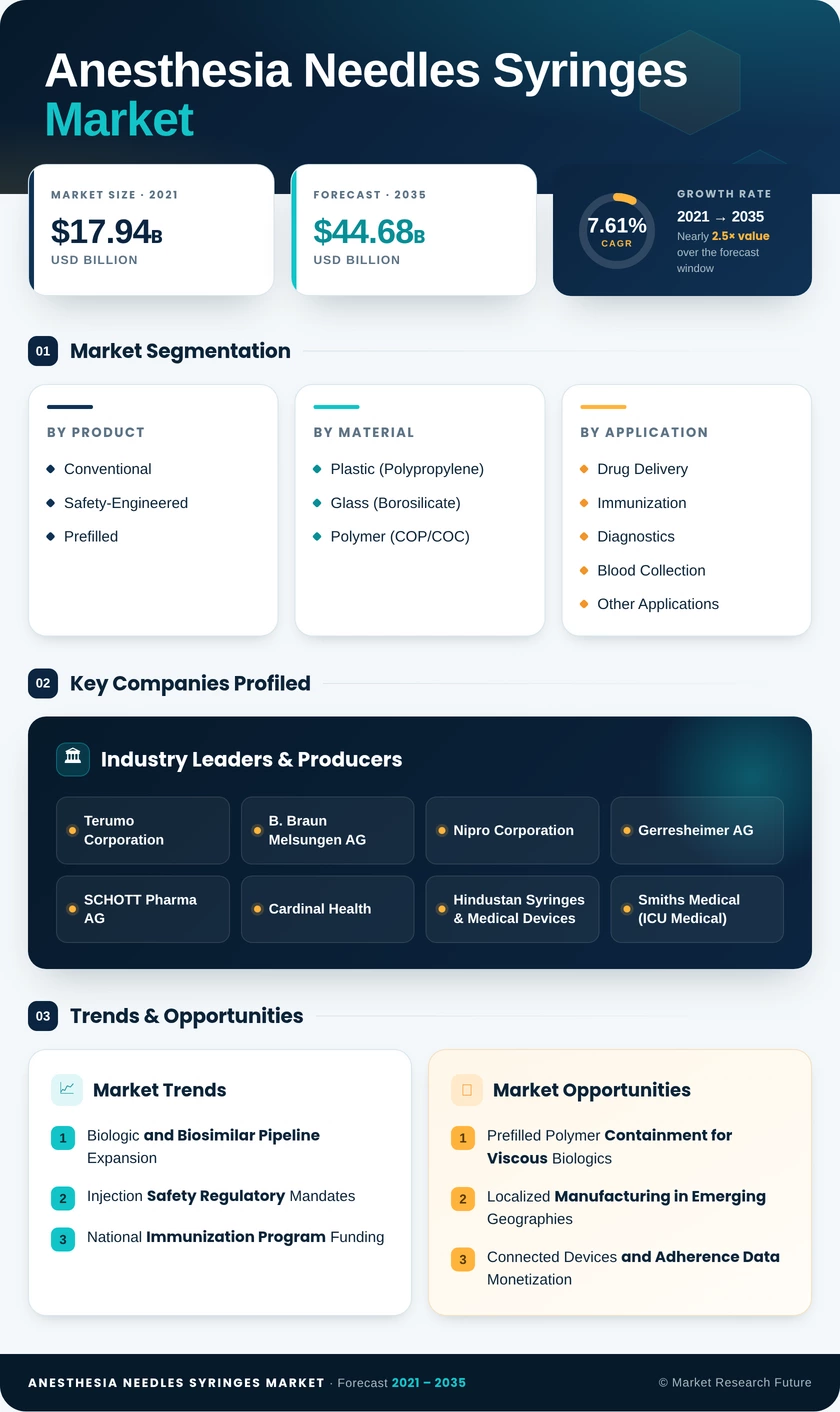
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product | Conventional; Safety-Engineered; Prefilled | Conventional | Safety-Engineered |
| By Material | Plastic (Polypropylene); Glass (Borosilicate); Polymer (COP/COC) | Plastic (Polypropylene) | Polymer (COP/COC) |
| By Application | Drug Delivery; Immunization; Diagnostics and Blood Collection; Other Applications | Drug Delivery | Diagnostics and Blood Collection |
| By End User | Hospitals and Clinics; Home-Care Settings; Diagnostic Laboratories; Ambulatory Surgical Centers | Hospitals and Clinics | Home-Care Settings |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product
| Sub-Segment | Key Trend |
| Conventional | Tender pricing pressure narrows margin even as unit volumes hold across public immunization channels |
| Safety-Engineered | Enforcement of occupational sharps regulation expands beyond North America and Western Europe into Gulf and East Asian systems |
| Prefilled | Biologic launch schedules increasingly dictate container-closure qualification timelines and premium pricing |
Product mix is the clearest indicator of where value is migrating. Conventional formats will retain volume leadership through the forecast window, but revenue growth concentrates in safety-engineered and prefilled tiers where regulation and molecule complexity justify higher specifications.
By Material
| Sub-Segment | Key Trend |
| Plastic (Polypropylene) | Remains the cost benchmark for high-volume disposable applications and donor-funded procurement |
| Glass (Borosilicate) | Sustained by legacy stability data that makes material switching regulatorily expensive |
| Polymer (COP/COC) | Selected at formulation stage for cold-chain and high-viscosity biologics requiring breakage resistance |
Material selection has moved upstream from packaging decisions into formulation science. Manufacturers holding validated polymer platforms are winning decade-long supply agreements that were historically awarded on price alone.
By Application
| Sub-Segment | Key Trend |
| Drug Delivery | Chronic disease regimens and GLP-1 uptake generate recurring high-specification demand |
| Immunization | Donor-funded procurement sets a hard price floor near USD 0.04 per auto-disable unit |
| Diagnostics and Blood Collection | National screening program expansion across Asia-Pacific lifts specimen collection volume |
| Other Applications | Veterinary, dental, and aesthetic procedures provide steady non-clinical demand |
Application mix explains the persistent divergence between unit volume and revenue. Immunization dominates shipment counts while drug delivery dominates value, and procurement strategy differs fundamentally between the two.
By End User
| Sub-Segment | Key Trend |
| Hospitals and Clinics | Safety formulary standards set here propagate outward into other care settings |
| Home-Care Settings | Lay-user human factors validation and robust packaging become qualification requirements |
| Diagnostic Laboratories | Testing throughput growth ties demand to screening policy rather than treatment volume |
| Ambulatory Surgical Centers | Procedural focus supports a premium device mix despite smaller absolute volume |
End-user composition is shifting purchasing authority away from hospital group purchasing organizations toward specialty pharmacies and direct-to-patient channels. Suppliers building logistics and packaging competence for those channels will capture margin previously held by distributors.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA