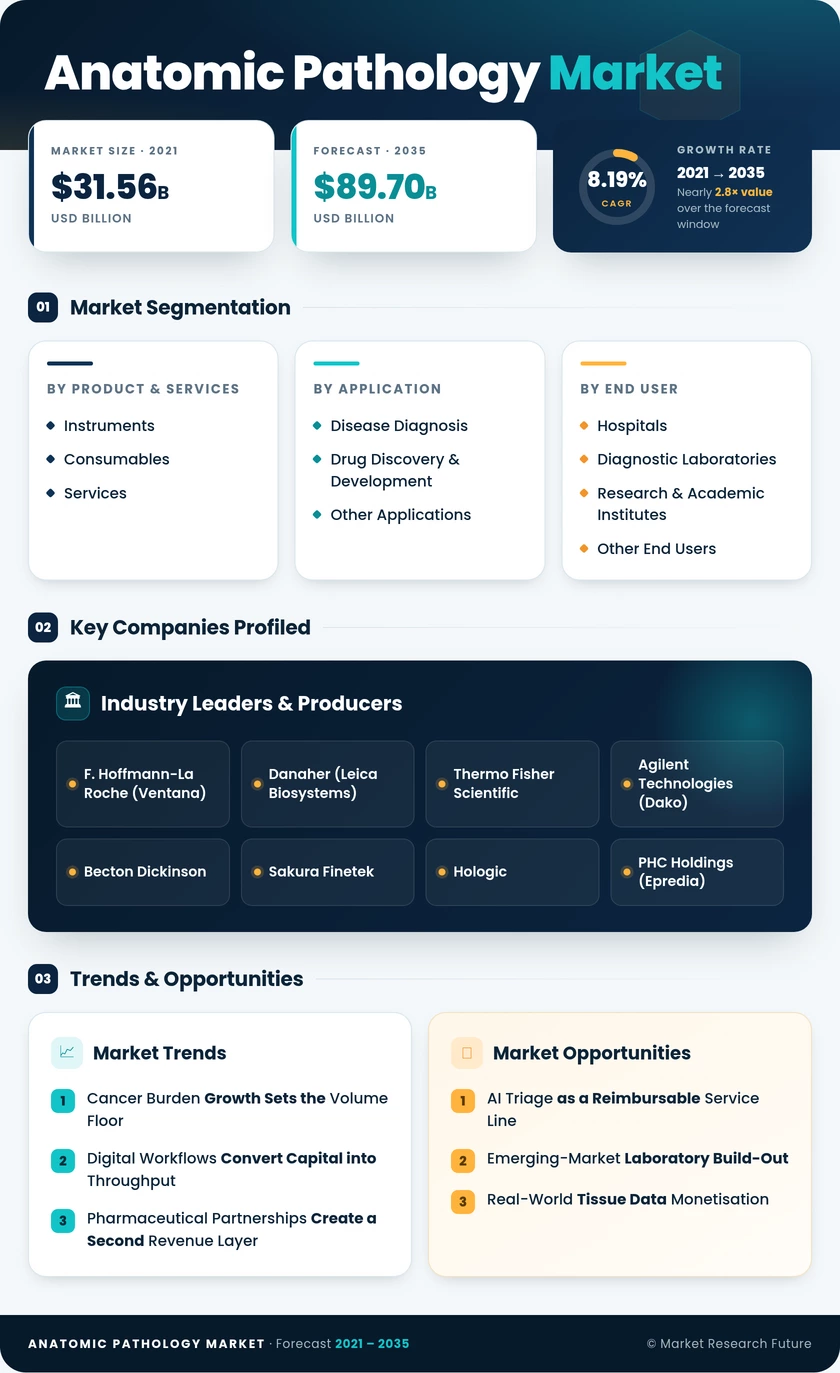
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product & Services | Instruments; Consumables; Services | Consumables | Services |
| By Application | Disease Diagnosis; Drug Discovery & Development; Other Applications | Disease Diagnosis | Drug Discovery & Development |
| By End User | Hospitals; Diagnostic Laboratories; Research & Academic Institutes; Other End Users | Hospitals | Diagnostic Laboratories |
| By Geography | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Product & Services
| Sub-Segment | Key Trend |
| Instruments | Scanner and autostainer refresh cycles tied to digital conversion capital approvals |
| Consumables | Antibody menu expansion and multiplex detection kits lifting spend per case |
| Services | Managed subspecialty reads and cloud archive contracts converting fixed cost to variable |
Recurring consumable spend remains the financial engine of this dimension, while services grow fastest as laboratories rent expertise they cannot hire. Instrument demand is lumpier, rising and falling with hospital capital cycles and grant awards.
By Application
| Sub-Segment | Key Trend |
| Disease Diagnosis | Screening programme expansion and earlier-stage detection lifting slide volumes |
| Drug Discovery & Development | Companion diagnostic co-development contracts tied to biomarker-defined approvals |
| Other Applications | Academic, forensic, and veterinary tissue work expanding on grant and private funding |
Diagnosis supplies the volume; drug development supplies the margin. Sponsor-funded tissue programmes are also structurally insulated from public health budget cycles, which is why suppliers actively court them.
By End User
| Sub-Segment | Key Trend |
| Hospitals | Tumour board turnaround requirements favouring in-house histology retention |
| Diagnostic Laboratories | Hub-and-spoke consolidation absorbing volume hospitals cannot staff |
| Research & Academic Institutes | Translational tissue atlas programmes and biobank-linked studies |
| Other End Users | Contract research organisations and public health reference laboratories |
Volume is migrating from hospital benches to independent networks wherever staffing pressure bites hardest. Academic centres set the protocols that both groups eventually adopt, giving them influence far beyond their revenue share.
By Geography
| Sub-Segment | Key Trend |
| North America | Reimbursement-led consolidation and early digital primary diagnosis adoption |
| Europe | IVDR compliance reshaping assay portfolios and favouring large reference networks |
| Asia-Pacific | Greenfield laboratory construction skipping the analogue equipment generation |
| South America | Public-private partnership models extending oncology diagnostic access |
| Middle East & Africa | Sovereign health investment funding fully digital flagship laboratories |
Mature regions grow through value per case; emerging regions grow through new capacity. That distinction determines which commercial model — premium platform sales versus reagent-rental placement — wins in each geography.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA