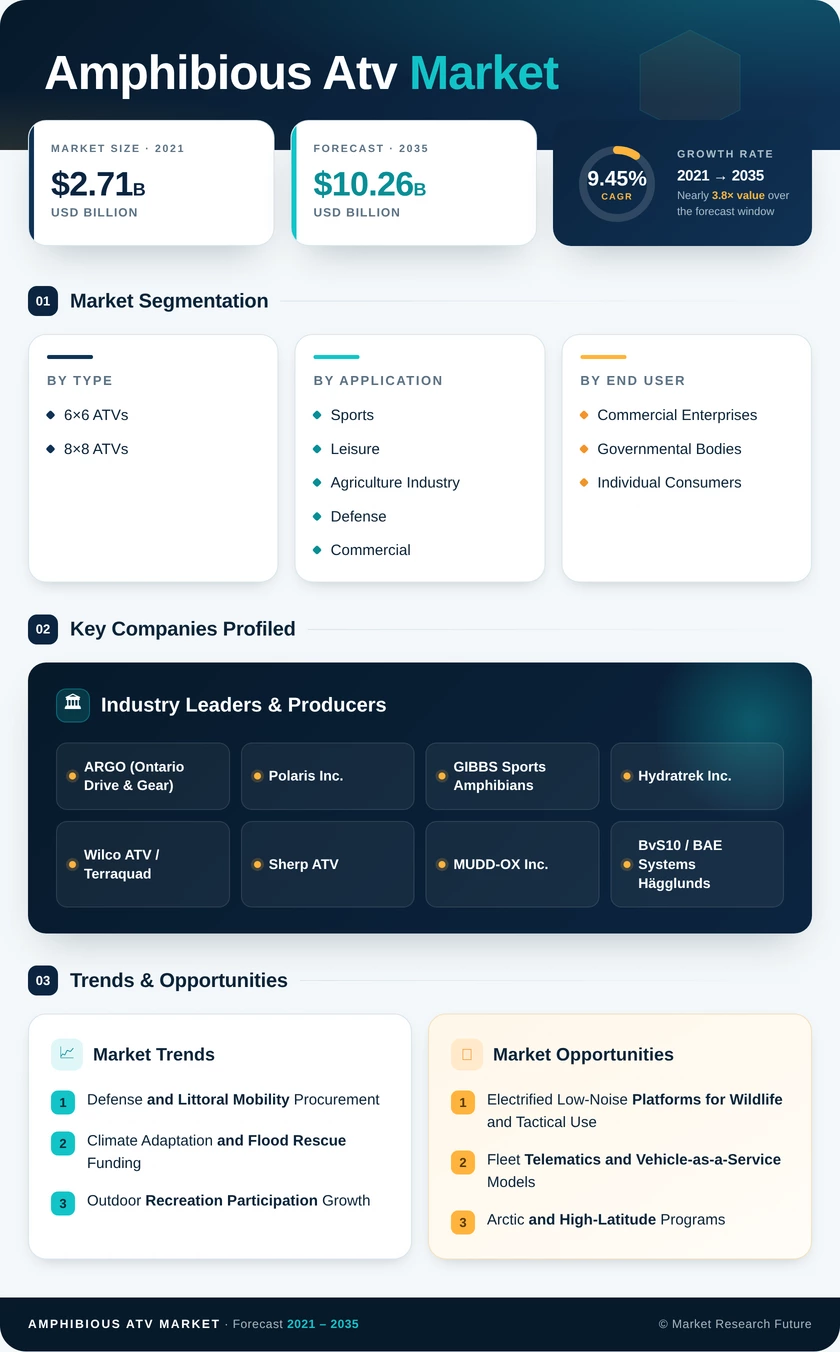
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Type | 6×6 ATVs; 8×8 ATVs | 6×6 ATVs (63.4% share) | 8×8 ATVs (10.2% CAGR) |
| By Application | Sports and Leisure; Agriculture Industry; Defense; Commercial and Industrial | Sports and Leisure (USD 1.62 Billion) | Defense (10.5% CAGR) |
| By End User | Commercial Enterprises; Governmental Bodies; Individual Consumers | Individual Consumers (44.7% share) | Governmental Bodies (10.6% CAGR) |
| By Propulsion Type | Wheel-Based; Track-Based | Wheel-Based (51.2% share) | Track-Based (10.4% CAGR) |
| By Distribution Channel | OEM; Aftermarket | OEM (71.9% share) | Aftermarket (10.4% CAGR) |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | North America (41.8% share) | Asia-Pacific (10.9% CAGR) |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
|---|---|
| 6×6 ATVs | Modular rack, canopy, and rescue-kit ecosystems widen single-platform use |
| 8×8 ATVs | Central tire inflation, winches, and open-architecture electronics standardize |
6×6 ATVs lead on a practical constraint rather than a technical one: the platform fits a pickup bed and a tactical aircraft pallet, which decides purchases for recreation buyers and entry-level government fleets alike. 8×8 ATVs grow fastest because payload requirements near 4,000 lb and redundant wheel-turbine propulsion are non-negotiable for pipeline inspection and armed configurations. Buyers rarely cross-shop the two; the decision is made by mission weight and transport method before price enters the conversation.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Sports and Leisure | Rental fleets in park gateways smooth seasonal demand and seed retail conversion |
| Agriculture Industry | Delta and peatland operators replace tracked tractors for seasonal field access |
| Defense | Littoral maneuver doctrine converts into multi-year turreted and cargo contracts |
| Commercial and Industrial | Right-of-way inspection displaces helicopter survey on short pipeline segments |
Sports and Leisure holds the largest revenue pool because a single amphibious unit replaces a boat and an ATV for anglers and lakeside property owners, and rental exposure keeps conversion flowing. Defense grows fastest, driven by NATO northern-flank capability targets and Arctic mobility programs that specify buoyancy and redundancy no recreational platform carries. Agriculture, Industry, and Commercial and Industrial buyers converge on a different priority set — uptime, telematics, and payload — which is steadily pulling factory specification away from consumer styling and toward fleet durability.
By End User
| Sub-Segment | Key Trend |
|---|---|
| Commercial Enterprises | Telematics and safety upgrades adopted to satisfy occupational and insurance rules |
| Governmental Bodies | Climate adaptation budgets convert rescue purchases into standing categories |
| Individual Consumers | Accessory and retrofit spending sustains dealer margin beyond the initial sale |
Individual Consumers carry unit volume and remain the reason dealer networks exist, since aftermarket accessory attach rates on consumer units far exceed fleet purchases. Governmental Bodies grow fastest as flood-response funding shifts from emergency procurement to scheduled replacement cycles running seven to ten years. Commercial Enterprises act as the specification bridge between the two, demanding hull-integrity documentation and fleet telematics that later filter down into consumer models as standard equipment.
By Propulsion Type
| Sub-Segment | Key Trend |
|---|---|
| Wheel-Based | Road legality in selected jurisdictions supports mixed-surface mission profiles |
| Track-Based | Ultra-low ground pressure near 17 kPa unlocks muskeg and thawing permafrost |
Wheel-Based propulsion leads because most missions include at least one paved segment, and wheel maintenance costs a fraction of track replacement over a service life. Track-Based systems grow fastest in Arctic, mining, and peatland work where sinkage ends a mission outright and speed is irrelevant. State-backed Arctic procurement — tracked units qualified to full grade capability and −40°C cold start — is the specific mechanism behind that faster growth rather than any general shift in buyer preference.
By Distribution Channel
| Sub-Segment | Key Trend |
|---|---|
| OEM | Factory experience centers and dealer consolidation deepen channel control |
| Aftermarket | Lighting, roof conversion, and tele-operation retrofit kits scale with installed base |
OEM channels dominate transaction value because amphibious sealing certification and warranty documentation cannot be replicated by independents, and government tenders require factory compliance paperwork outright. Aftermarket revenue grows faster as an expanding installed base ages into upgrade territory, with retrofit kits carrying gross margins above 45%. The boundary between them is set by hull integrity: cosmetic and electronic modifications flow to independents, while anything touching the sealed hull returns to factory-authorized service.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA