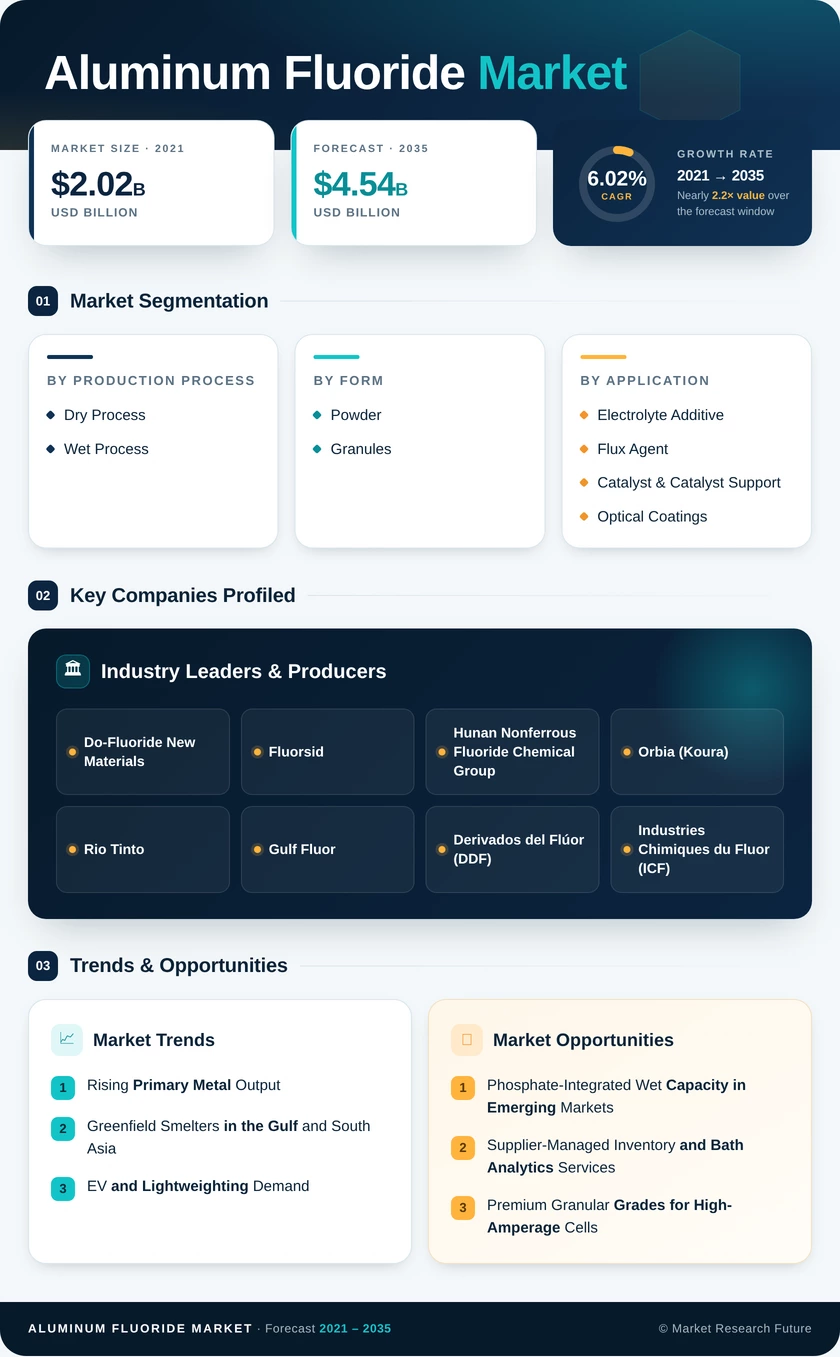
Aluminum Fluoride Market (2026 - 2035)

ID: MRFR/CnM/3872-HCR 111 Pages Chitranshi Jaiswal Last Updated: September 24, 2026
Aluminum Fluoride Market Research Report Information By Production Process (Dry Process and Wet Process), By Form (Powder and Granules), By Application (Electrolyte Additive, Flux Agent, Catalyst & Catalyst Support, and Optical Coatings), and By End-use Industry (Aluminum Smelting, Chemicals, Ceramics & Glass, Electronics & Optics, and Other End-use Industry) – Forecast Till 2035
Aluminum Fluoride Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.02%
2025 Market SizeUSD 2.53 Billion
2035 Market SizeUSD 4.54 Billion
Key Players
Do-Fluoride New Materials
Fluorsid
Hunan Nonferrous Fluoride Chemical Group
Orbia
Rio Tinto
Gulf Fluor
Opportunities
  • Phosphate-Integrated Wet Capacity in Emerging Markets
  • Supplier-Managed Inventory and Bath Analytics Services
  • Premium Granular Grades for High-Amperage Cells
  1. 1 Market Summary | |
  2. 2 Key Report Takeaways | |
    1. 2.1 By Production Process | |
    2. 2.2 By Form | |
    3. 2.3 By Application | |
    4. 2.4 By End-use Industry | |
    5. 2.5 By Region | |
  3. 3 Market Size and Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2024) | |
    2. 3.2 Base Year and Forecast Market Size (2025–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Driver Impact Analysis | |
    1. 4.1 Rising Primary Metal Output | |
    2. 4.2 Greenfield Smelters in the Gulf and South Asia | |
    3. 4.3 EV and Lightweighting Demand | |
    4. 4.4 Low-Carbon Smelting Incentives | |
    5. 4.5 Feedstock Diversification Toward Wet Routes | |
    6. 4.6 Automated Dosing and Granular Grades | |
  5. 5 Restraints Impact Analysis | |
    1. 5.1 Fluorspar Supply Concentration and Price Volatility | |
    2. 5.2 Capacity Ceiling on the Largest Smelting Base | |
    3. 5.3 Tightening Fluoride Emission Regulations | |
    4. 5.4 Fluoride Recycling via Dry Scrubbing | |
    5. 5.5 Energy-Driven Smelter Curtailments | |
  6. 6 Opportunities | |
    1. 6.1 Phosphate-Integrated Wet Capacity in Emerging Markets | |
    2. 6.2 Supplier-Managed Inventory and Bath Analytics Services | |
    3. 6.3 Premium Granular Grades for High-Amperage Cells | |
    4. 6.4 Fluoride Recovery from Spent Pot Lining | |
    5. 6.5 High-Purity Grades for Optical and Electronic Uses | |
  7. 7 Regional Market Share and Country-Level Analysis | |
    1. 7.1 Asia Pacific | |
    2. 7.2 North America | |
    3. 7.3 Europe | |
    4. 7.4 South America | |
    5. 7.5 Middle East | |
    6. 7.6 Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Decarbonized Smelting and Inert Anodes | |
    2. 8.2 Digital Potline Control | |
    3. 8.3 Fluorine Security and Circularity | |
    4. 8.4 ESG Reporting and Carbon Border Rules | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Production Process | | |
      1. 9.1.1 Dry Process | | |
      2. 9.1.2 Wet Process | |
    2. 9.2 By Form | | |
      1. 9.2.1 Powder | | |
      2. 9.2.2 Granules | |
    3. 9.3 By Application | | |
      1. 9.3.1 Electrolyte Additive | | |
      2. 9.3.2 Flux Agent | | |
      3. 9.3.3 Catalyst & Catalyst Support | | |
      4. 9.3.4 Optical Coatings | |
    4. 9.4 By End-use Industry | | |
      1. 9.4.1 Aluminum Smelting | | |
      2. 9.4.2 Chemicals | | |
      3. 9.4.3 Ceramics & Glass | | |
      4. 9.4.4 Electronics & Optics | | |
      5. 9.4.5 Other End-use Industry | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Concentration Analysis | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Do-Fluoride New Materials | | |
      2. 10.3.2 Fluorsid | | |
      3. 10.3.3 Hunan Nonferrous Fluoride Chemical Group | | |
      4. 10.3.4 Orbia (Koura) | | |
      5. 10.3.5 Rio Tinto | | |
      6. 10.3.6 Gulf Fluor | | |
      7. 10.3.7 Derivados del Flúor (DDF) | | |
      8. 10.3.8 Industries Chimiques du Fluor (ICF) | | |
      9. 10.3.9 PhosAgro | | |
      10. 10.3.10 Tanfac Industries | | |
      11. 10.3.11 Alufluor AB | |
  11. 11 Recent News & Developments | |
  12. 12 Report Scope and Methodology | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Report Summary — Key Market Metrics | |
  16. TABLE 2 Global Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis | |
  18. TABLE 4 Restraints Impact Analysis | |
  19. TABLE 5 Regional Summary, 2025 | |
  20. TABLE 6 Asia Pacific Demand by End-use Industry, 2025 | |
  21. TABLE 7 North America Demand by End-use Industry, 2025 | |
  22. TABLE 8 Europe Demand by End-use Industry, 2025 | |
  23. TABLE 9 South America Demand by End-use Industry, 2025 | |
  24. TABLE 10 Middle East Demand by End-use Industry, 2025 | |
  25. TABLE 11 Africa Demand by End-use Industry, 2025 | |
  26. TABLE 12 Global Market, by Production Process, 2025–2035 | |
  27. TABLE 13 Global Market, by Form, 2025–2035 | |
  28. TABLE 14 Global Market, by Application, 2025–2035 | |
  29. TABLE 15 Global Market, by End-use Industry, 2025–2035 | |
  30. TABLE 16 Competitive Benchmarking Matrix | |
  31. TABLE 17 Report Scope and Methodology | |
  32. TABLE 18 Detailed Sources and Citations | | LIST OF FIGURES | |
  33. FIGURE 1 Market Dynamics Overview — Drivers, Restraints, Opportunities | |
  34. FIGURE 2 Industry Value Chain — Fluorspar and Fluorosilicic Acid to Smelter | |
  35. FIGURE 3 Porter's Five Forces Analysis | |
  36. FIGURE 4 Global Market Size Trend, 2021–2035 (USD Billion) | |
  37. FIGURE 5 Market Share by Production Process, 2025 | |
  38. FIGURE 6 Market Share by Form, 2025 | |
  39. FIGURE 7 Market Share by Application, 2025 | |
  40. FIGURE 8 Market Share by End-use Industry, 2025 | |
  41. FIGURE 9 Regional Market Share, 2025 | |
  42. FIGURE 10 Regional Growth Comparison, 2026–2035 | |
  43. FIGURE 11 Competitive Landscape — Estimated Revenue Share Ranges

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By Production ProcessDry Process, Wet ProcessDry Process (68.5% share)Wet Process (6.5% CAGR)
By FormPowder, GranulesPowder (58.6% share)Granules (6.3% CAGR)
By ApplicationElectrolyte Additive, Flux Agent, Catalyst & Catalyst Support, Optical CoatingsElectrolyte Additive (80.2% share)Optical Coatings (7.1% CAGR)
By End-use IndustryAluminum Smelting, Chemicals, Ceramics & Glass, Electronics & Optics, Other End-use IndustryAluminum Smelting (83.0% share)Electronics & Optics (7.4% CAGR)
By RegionAsia Pacific, North America, Europe, South America, Middle East, AfricaAsia Pacific (61.2% share)Middle East (7.2% CAGR)


Market Segmentation Overview

By Production Process

Sub-SegmentKey Trend
Dry ProcessRetains qualified smelter supply, exposed to fluorspar pricing
Wet ProcessExpands on phosphate-derived fluorosilicic acid feedstock


Dry Process leads because smelters have tuned bath control and material handling around its familiar grades over decades. Wet Process grows fastest, since fluorosilicic acid from phosphate plants avoids fluorspar concentration risk and produces a lower hydrogen fluoride off-gas burden. Qualification trials at existing potlines keep the transition gradual, and new plants adopt the wet route first.

By Form

Sub-SegmentKey Trend
PowderSupported by legacy pneumatic conveying and dosing systems
GranulesSpecified in new automated high-amperage pot rooms


Powder holds the larger share because older smelters built storage and feeders around it. Granules grow fastest as greenfield plants specify low-dust, free-flowing material for point feeders at design stage, which avoids retrofit costs. Reduced feeder blockages and cleaning time support a granular price premium.

By Application

Sub-SegmentKey Trend
Electrolyte AdditiveTracks primary metal output and bath ratio control needs
Flux AgentStable casthouse and ceramic flux demand
Catalyst & Catalyst SupportGrowing use in fluorination chemistry
Optical CoatingsHigh-purity demand for anti-reflective and UV films


Electrolyte Additive dominates because every reduction cell needs AlF3 to lower bath melting point and replace fluoride losses. Optical Coatings grows fastest, as precision optics makers pay premium prices for low-impurity grades. Flux Agent and Catalyst & Catalyst Support provide diversified, steadier demand outside potline cycles.

By End-use Industry

Sub-SegmentKey Trend
Aluminum SmeltingDriven by Gulf and South Asian greenfield capacity
ChemicalsSpecialty synthesis and catalyst demand
Ceramics & GlassEnamel and specialty glass formulations
Electronics & OpticsSemiconductor and display film requirements
Other End-use IndustryWelding fluxes and secondary metallurgy


Aluminum Smelting accounts for the dominant share, covering both bath additive and casthouse flux use at primary plants. Electronics & Optics grows fastest because semiconductor and display manufacturers need ultra-low-impurity grades that command much higher prices per tonne. Chemicals and Ceramics & Glass add diversified demand that cushions producers against smelter curtailments.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.