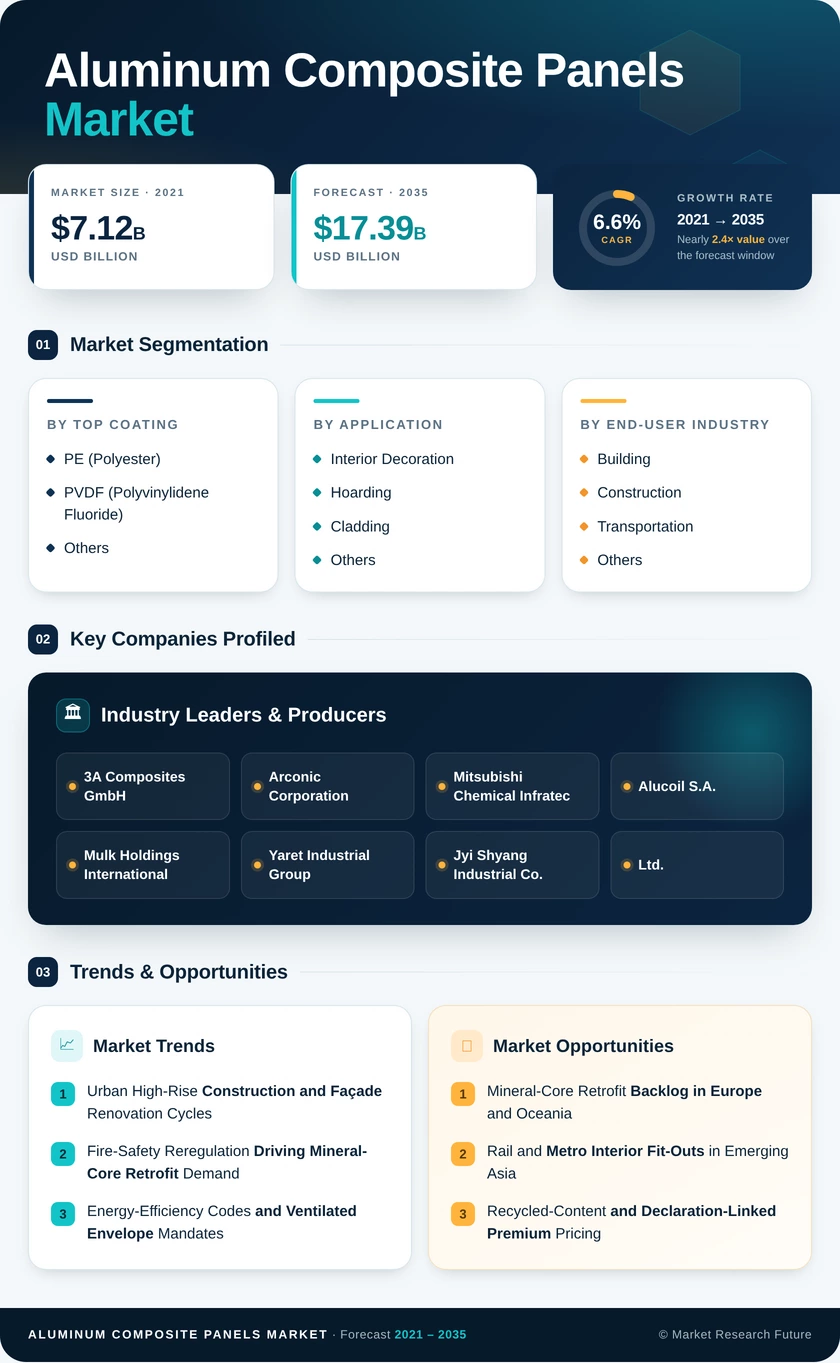
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Top Coating | PE (Polyester); PVDF (Polyvinylidene Fluoride); Others | PVDF (Polyvinylidene Fluoride) — 60.6% share (2025) | Others — 7.1% CAGR (2026–2035) |
| By Application | Interior Decoration; Hoarding; Cladding; Others | Cladding — 58.4% share (2025) | Hoarding — 7.4% CAGR (2026–2035) |
| By End-User Industry | Building and Construction; Transportation; Others | Building and Construction — 57.1% share (2025) | Transportation — 6.8% CAGR (2026–2035) |
| By Region | Asia-Pacific; Europe; North America; Middle East & Africa; South America | Asia-Pacific — 54.8% share (2025) | Asia-Pacific — 7.3% CAGR (2026–2035) |
Market Segmentation Overview
By Top Coating
| Sub-Segment | Key Trend |
|---|---|
| PE (Polyester) | Retreating to budget residential and short-life signage as commercial specification moves upmarket |
| PVDF (Polyvinylidene Fluoride) | Premium of 20–24% sustained by 25-year colour-retention warranties and coastal durability |
| Others | Nano-ceramic, anti-microbial and photocatalytic finishes entering healthcare and urban tower work |
PVDF (Polyvinylidene Fluoride) leads this dimension at 60.6% of 2025 revenue because ultraviolet stability determines whole-life façade cost on towers that will not be re-clad for two decades. PE (Polyester) retains a genuine value tier, but its share erodes wherever fire and durability certification is tendered together. Others grows fastest at 7.1% as hospital and laboratory specifiers request anti-microbial surface films that neither standard chemistry provides.
By Application
| Sub-Segment | Key Trend |
|---|---|
| Interior Decoration | Formability and non-directional metallic finishes drive hospitality and healthcare lobby adoption |
| Hoarding | UV inkjet printing shortens replacement cycles to 9–18 months, multiplying square-metre consumption |
| Cladding | Remediation mandates convert compliance spend into guaranteed replacement volume |
| Others | Column covers, beam wraps and railway liners diversify revenue away from new-build cycles |
Cladding carries 58.4% of application revenue and sets every technical requirement that matters, because fire, wind-load and cavity-drainage testing apply there first. Hoarding is the growth story at 7.4%, since printed site fences are consumed rather than amortised and are reprinted with each campaign. Interior Decoration occupies a stable middle position where formability outranks weathering, and Others absorbs the structural-concealment work that keeps converters busy between construction cycles.
By End-User Industry
| Sub-Segment | Key Trend |
|---|---|
| Building and Construction | Envelope renovation mandates and high-rise delivery sustain the largest demand pool |
| Transportation | Metro, intercity rail and electric bus programmes substitute composites for steel to cut mass |
| Others | Marine cabins, refrigerated trailer skins and clean-room enclosures add incremental tonnage |
Building and Construction holds 57.1% of end-user demand, and its composition is shifting from new-build toward regulated replacement as remediation registers in Britain, Australia and the Gulf work through their backlogs. Transportation grows fastest at 6.8% because every kilogram removed from a metro car or electric bus interior converts directly into range or payload. Others remains small but defensible, since marine and clean-room buyers value hygiene and temperature stability over first cost.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA