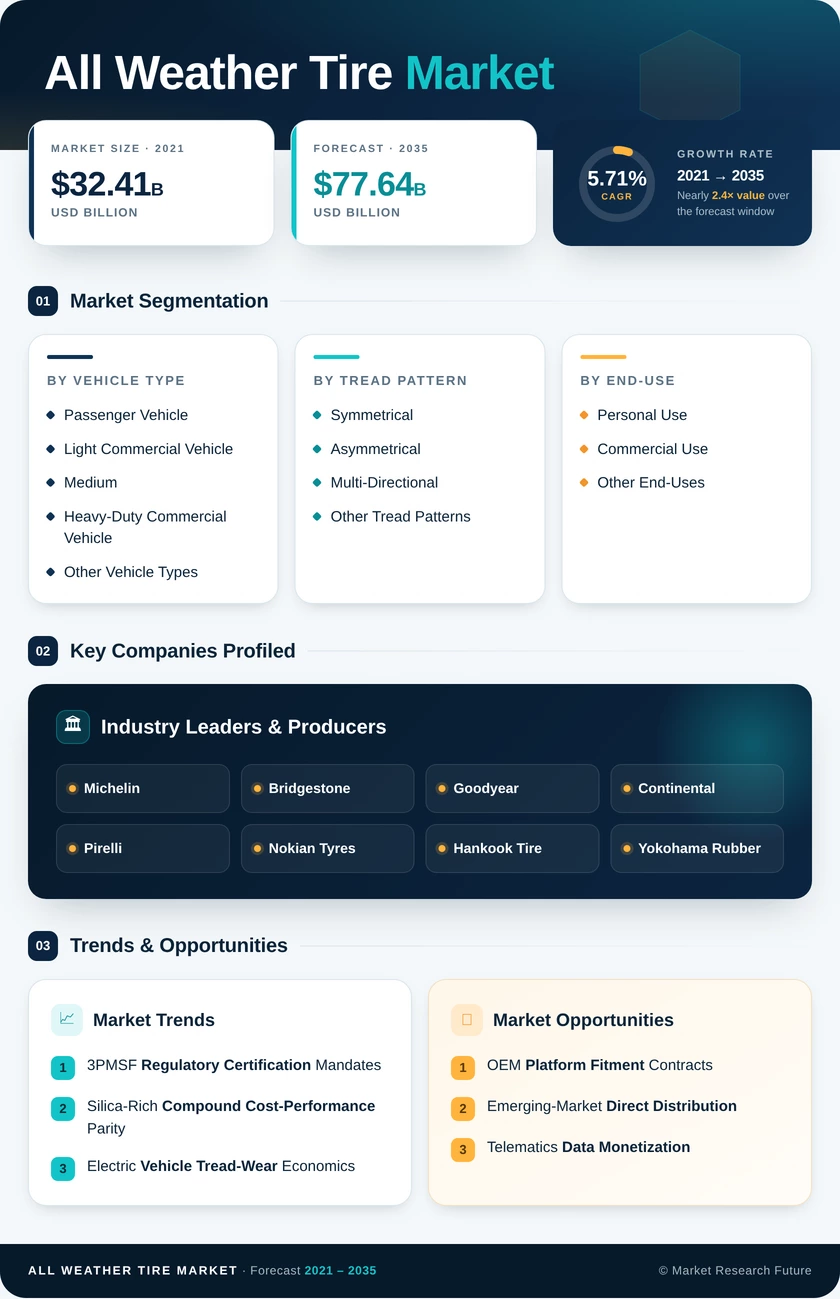
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Vehicle Type | Passenger Vehicle; Light Commercial Vehicle; Medium and Heavy-Duty Commercial Vehicle; Other Vehicle Types | Passenger Vehicle — 53.6% share (2024) | Light Commercial Vehicle — 7.38% CAGR |
| By Tread Pattern | Symmetrical; Asymmetrical; Multi-Directional; Other Tread Patterns | Symmetrical — USD 17.05 Billion (2024) | Multi-Directional — 5.63% CAGR |
| By End-Use | Personal Use; Commercial Use; Other End-Uses | Personal Use — 51.9% share (2024) | Commercial Use — 7.06% CAGR |
| By Sales Channel | Online; Offline | Offline — 79.4% share (2024) | Online — 15.71% CAGR |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific — 47.3% share (2025) | Middle East & Africa — 7.42% CAGR (2026–2035) |
Market Segmentation Overview
By Vehicle Type
| Sub-Segment | Key Trend |
|---|---|
| Passenger Vehicle | Lengthening replacement cycles offset by mixed-climate single-fitment conversion |
| Light Commercial Vehicle | Parcel delivery mileage compressing replacement intervals |
| Medium and Heavy-Duty Commercial Vehicle | Inventory consolidation across variable route networks |
| Other Vehicle Types | Two- and three-wheeler ride-hailing adoption in Southeast Asia |
Passenger Vehicle leads on installed parc scale, but Light Commercial Vehicle grows fastest because delivery vans run 180–240 km per shift and a seasonal changeover costs USD 95–140 per unit in labor and depot storage. Medium and Heavy-Duty Commercial Vehicle operators adopt more cautiously, since axle-position regulations still mandate specialized retreads that all-weather casings do not yet support. Electric van torque and mass accelerate tread wear by roughly 20%, which pushes commercial buyers toward premium compounds rather than away from them.
By Tread Pattern
| Sub-Segment | Key Trend |
|---|---|
| Symmetrical | Uniform block geometry minimizing mold cost and rotation restrictions |
| Asymmetrical | Lateral stiffness retained for performance and premium SUV fitments |
| Multi-Directional | Orientation-free designs specified for global vehicle platforms |
| Other Tread Patterns | Directional aquaplaning designs losing share to mounting-error risk |
Symmetrical holds the largest revenue pool because its tooling economics suit family sedans and budget crossovers. Multi-Directional grows fastest: computer-aided block sequencing now achieves snow-siping density and noise cancellation without directional mounting rules, which matters to online buyers who self-install and to fleets that rotate front-to-rear freely. Asymmetrical remains commercially healthy in performance fitments where wet-cornering precision justifies higher mold investment, but it will not penetrate economy tiers at current cost structures.
By End-Use
| Sub-Segment | Key Trend |
|---|---|
| Personal Use | Urban storage scarcity favoring single year-round fitment |
| Commercial Use | Predictive maintenance platforms replacing calendar-based changeover |
| Other End-Uses | Rental and municipal tenders specifying year-round compounds |
Personal Use dominates volume, sustained by apartment-dwelling owners across Europe and Asia-Pacific with no off-season storage option. Commercial Use expands faster because fleet asset managers quantify downtime precisely and tie tire-pressure monitoring data to auto-generated work orders synchronized with driver schedules. Other End-Uses, particularly rental agencies rebalancing vehicles between depots in different climate zones, increasingly write all-weather specification directly into procurement tenders to eliminate multi-depot storage liability.
By Sales Channel
| Sub-Segment | Key Trend |
|---|---|
| Online | Mobile installation networks decoupling purchase from physical retail |
| Offline | Installer-attached balancing, alignment and fitment service bundling |
Offline retains roughly four-fifths of transactions because most buyers still want fitment, balancing, and alignment handled in one visit by a technician they can question. Online grows several times faster as mobile installation removes the last logistical objection and certification marks substitute for in-store advice. The channel shift structurally favors 3PMSF-rated products, since digital storefronts expose certification as a filterable specification while physical shelves rely on salesperson framing.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA